Mortgage
How Debt-to-Income and Affordability Checks Work for UK Mortgages
Understand how UK lenders assess your affordability through debt-to-income ratios, income multiples, and stress testing before approving your mortgage application.
Articles about credit under Mortgage.
Understand how UK lenders assess your affordability through debt-to-income ratios, income multiples, and stress testing before approving your mortgage application.
Your credit score directly affects mortgage approval and the interest rate you are offered. Learn how UK lenders assess creditworthiness and what steps you can take to strengthen your position before applying.
Missed payments do not automatically disqualify you from getting a mortgage in the UK. Specialist adverse credit lenders assess applications individually and may still approve you, though typically at higher rates and with a larger deposit required.
Self-employed borrowers face different mortgage application requirements. Discover what documentation and evidence lenders require when you cannot provide traditional payslips.
A practical checklist to help you strengthen your credit file and boost your chances of mortgage approval in the UK.
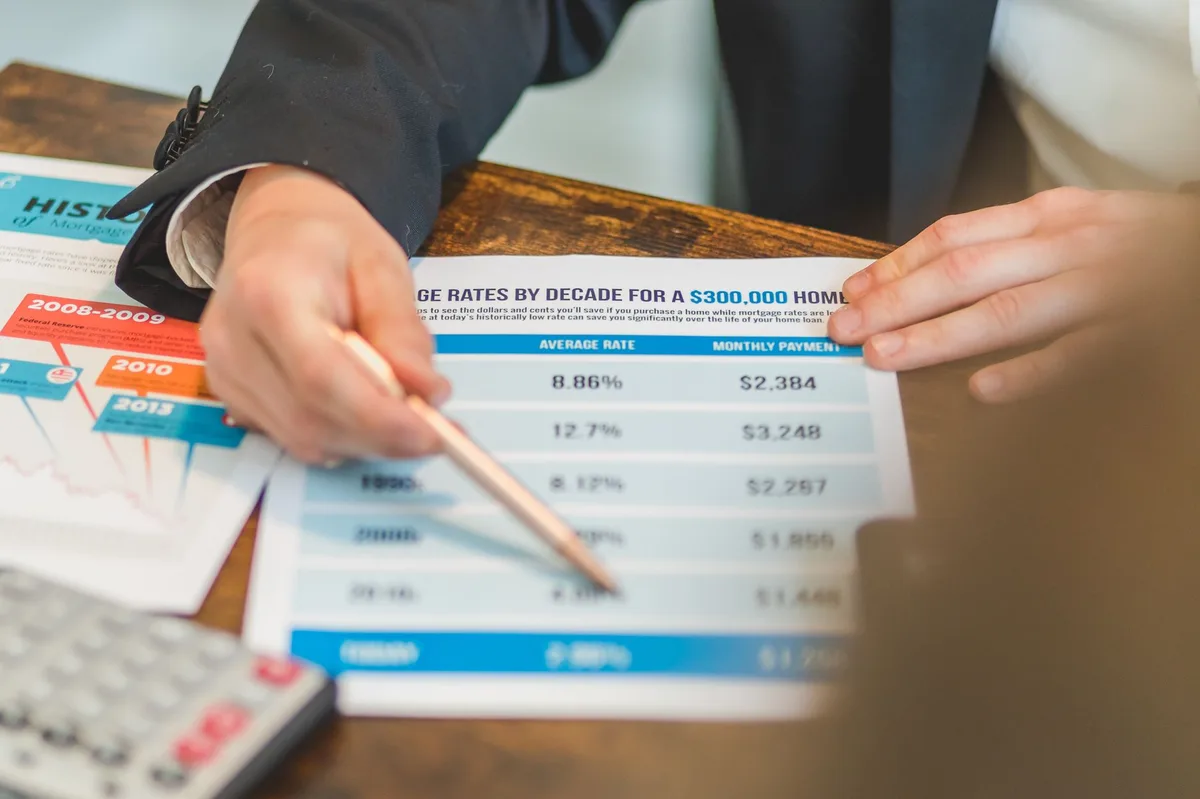
Learn how UK lenders use stress testing to assess whether you can afford your mortgage if interest rates rise, and what it means for your borrowing power.
Nationwide Building Society now offers up to six times income for home movers and remortgage customers, expanding access to higher loan amounts for existing homeowners.
Rising interest rates reduce how much you can borrow by tightening lenders' affordability calculations and stress tests, even when rates are still lower than historical averages.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.
