Should You Remortgage This Autumn Before the Bank of England November Meeting in the UK
Autumn is traditionally peak remortgage season in the UK. With the Bank of England's November interest rate decision looming, here is what you need to know about switching deals now.
Pexels - RDNE Stock project · original
In this article
Key Takeaway
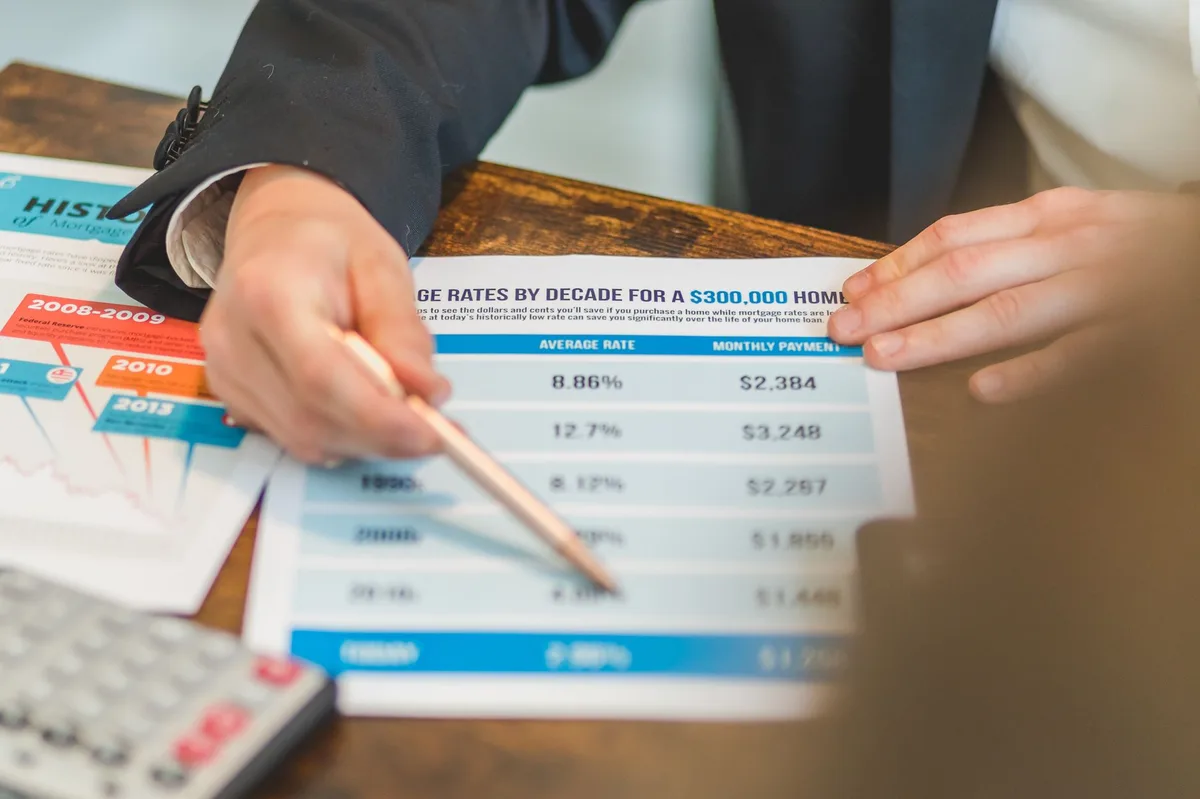
Autumn is peak remortgage season in the UK because many fixed-rate deals taken out two or five years ago are ending now. If your current deal is expiring soon, you can typically secure a new rate up to six months in advance, letting you lock in terms before the Bank of England’s November interest rate decision. However, rushing to remortgage early may trigger early repayment charges (ERCs) if you are still inside your deal period, so check your end date and compare the cost of any ERC against potential rate changes.
Why Autumn Matters for Remortgaging
Autumn has long been the busiest time of year for remortgaging in the UK. According to MoneyHelper, many borrowers took out two-year or five-year fixed-rate mortgages in late 2021 through early 2024, and those deals are now reaching their end. When your initial deal period finishes, your mortgage automatically reverts to your lender’s standard variable rate (SVR), which is typically much higher than the rate you were paying during your fixed or discounted term.
For most borrowers, remortgaging onto a new deal (either with your current lender via a product transfer or by switching to a new lender) is cheaper than staying on the SVR. Because so many deals expire in September, October and November, lenders and brokers see a surge in remortgage applications during these months.
The Bank of England November Meeting Context
The Bank of England’s Monetary Policy Committee meets eight times a year to decide the base rate, which influences the interest rates lenders charge on mortgages. The November meeting is one of the scheduled decision points, and the outcome can affect mortgage pricing across the market (Bank of England, 2026).
If the base rate rises, tracker mortgages and SVRs typically go up immediately, and new fixed-rate deals may become more expensive. If the base rate falls or holds steady, lenders may reduce new fixed rates or keep them stable. The base rate does not directly change your existing fixed-rate mortgage (your rate is locked for the deal period), but it does influence the cost of any new deal you take out.
As foundational texts such as Principles of Finance explain, interest rate expectations drive borrowing decisions: when rates are expected to rise, borrowers rush to lock in fixed terms, and when rates are expected to fall, some wait for better offers.
Should You Remortgage Before the November Meeting?
The answer depends on your personal situation:
If your deal ends in the next six months: Most lenders let you apply for a new mortgage up to six months before your current deal expires, and you can lock in the rate when you apply. Securing your new rate now protects you from any rate increases announced at the November meeting. However, rates as of September 2026 may not be the lowest available over the next few months, so speak to an FCA-authorised mortgage adviser to compare current offers against the risk of waiting.
If your deal has already ended: You are almost certainly on the SVR, which is significantly higher than fixed or tracker deals. Remortgaging now is usually the right move, regardless of what the Bank of England does in November. Delaying further will cost you more in interest each month.
If you are still inside your deal period: Breaking your mortgage early to remortgage will usually trigger an early repayment charge (ERC). ERCs are typically a percentage of your outstanding loan (often 1 per cent to 5 per cent, depending on how much time remains), so the cost can run into thousands of pounds. Only consider this if mortgage rates have dropped so much that the savings over the remainder of your term outweigh the ERC, or if your circumstances have changed (for example, you need to move home or release equity). An FCA-authorised mortgage adviser can model the numbers for you.
Read also: UK Remortgage Guide: When to Switch Deals and How to Get the Best Rate
If rates fall after November: You cannot retrospectively change the rate you have locked in. However, if you have applied but not yet completed your remortgage, some lenders allow a one-time rate reduction if they lower their own rates before completion. Check your lender’s policy when you apply.
What to Do Now
-
Check your mortgage end date. Look at your most recent annual statement or call your lender. If your deal ends within the next six months, you can start the remortgage process now.
-
Compare offers. Speak to an FCA-authorised mortgage adviser or use a whole-of-market broker to see what fixed, tracker or discount deals are available. Consider the rate, the deal period (two, three, five or ten years), any product fees, and whether the deal allows overpayments or portability if you move home.
-
Understand the true cost. The annual percentage rate of charge (APRC) includes the interest rate and the lender’s fees spread over the loan term, giving you a fuller picture of the deal’s cost.
-
Act before your deal ends. The typical remortgage takes four to eight weeks from application to completion. Starting early avoids the risk of reverting to the SVR while your new mortgage is being processed.
-
Avoid breaking your deal early unless the maths works. ERCs are expensive. Only exit your current deal early if you have modelled the cost and confirmed the long-term savings justify it.
Disclaimers
This article provides general educational information about remortgaging in the UK and is not regulated mortgage advice. It is not personalised financial or lending advice. Refisage is not authorised by the Financial Conduct Authority (FCA). Your home may be repossessed if you do not keep up repayments on your mortgage. Mortgage rates, products, eligibility criteria, fees and early repayment charges vary by lender, product and your personal circumstances. Always speak to an FCA-authorised mortgage adviser before making any remortgaging decision. For free, impartial guidance, visit MoneyHelper.
Conclusion
Autumn is the traditional remortgage peak in the UK, and if your deal is ending soon, securing a new rate before the Bank of England’s November meeting can protect you from potential rate rises. However, do not rush to break your current deal early without understanding the cost of any early repayment charge. Speak to an FCA-authorised mortgage adviser, compare whole-of-market offers, and act early enough that your new mortgage completes before your current deal ends and you revert to a higher SVR.
Sources
- Remortgaging (accessed )
- Bank of England Monetary Policy (accessed )
- Financial Conduct Authority (accessed )
- Principles of Finance (accessed )
Related articles
When to Remortgage and How to Get the Best Rate in the UK
Learn when to remortgage in the UK, how to compare deals, and whether switching lenders will save you money after fees and early repayment charges.
7 Key Steps to Remortgaging in the UK: When to Switch and How to Get the Best Rate
Discover when to remortgage in the UK and how to secure the best rate. A 7-step guide covering deal periods, early repayment charges, and comparison tips.
A Complete Guide to Remortgaging in the UK: When to Switch and How to Get the Best Rate
Learn when to remortgage in the UK, how to compare deals, avoid early repayment charges, and secure the best rate for your circumstances.
