How to Remortgage Before Year-End in the UK: Avoiding Your Lender's Standard Rate
Your mortgage deal is ending soon, and you want to avoid reverting to your lender's expensive standard variable rate. Learn how to remortgage before year-end and secure a better rate in time.
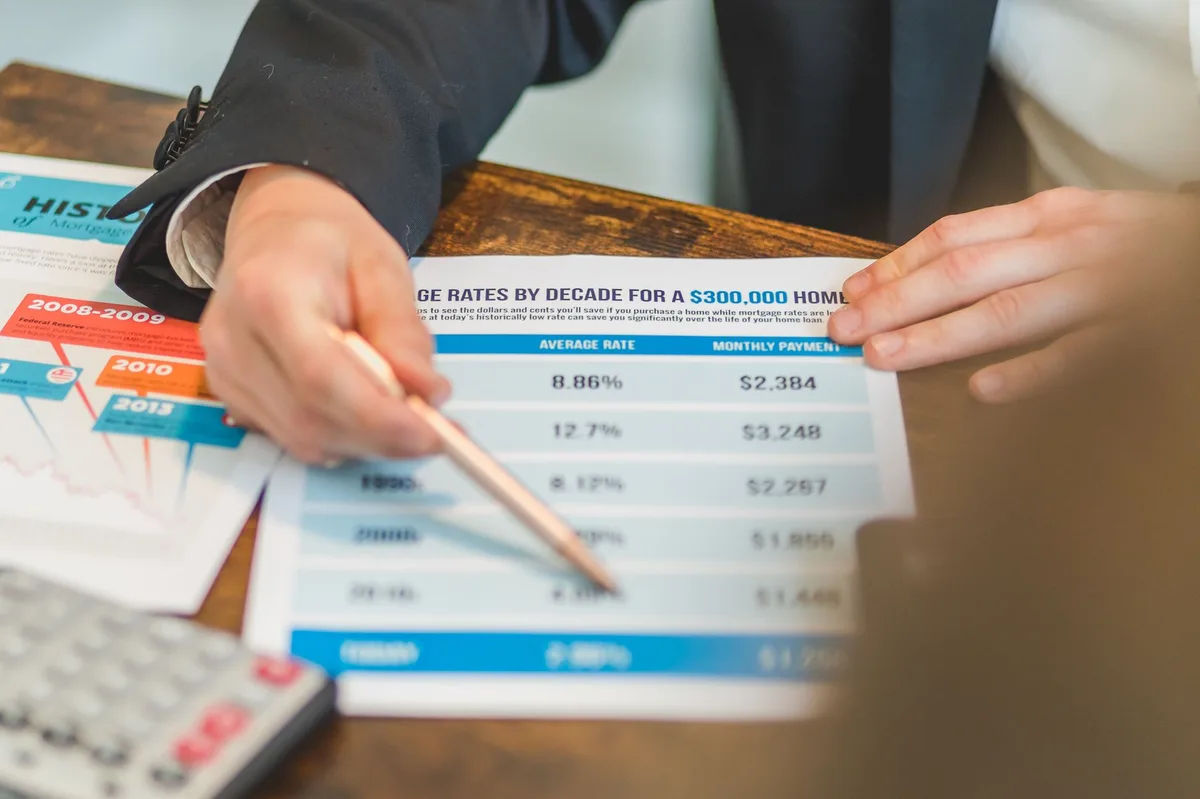
Pexels - RDNE Stock project · original
In this article
If your mortgage deal is ending before or around the new year, act now. Remortgaging before you revert to your lender’s standard variable rate (SVR) can save you hundreds of pounds per month. Start the process 3 to 6 months before your deal ends to ensure you switch to a new rate before the SVR kicks in.
When your fixed-rate, tracker, or discount mortgage deal period ends, your lender automatically moves you onto their SVR. This reversion rate is typically 2 to 3 percentage points higher than competitive remortgage rates, meaning your monthly payments can jump sharply. Remortgaging before year-end, whether by switching lender or taking a product transfer with your current lender, locks in a lower rate and avoids the SVR penalty.
What You Will Learn
This guide walks you through the steps to remortgage before your deal ends, including when to start, how to compare offers, and how to complete the switch in time to avoid reverting to the SVR.
1. Check Your Deal End Date and Early Repayment Charges
Find out exactly when your current deal period ends. Check your mortgage statement, your lender’s online portal, or ring your lender directly. The deal end date is when your fixed-rate, tracker, or discount period expires and you revert to the SVR.
Also confirm whether you face an early repayment charge (ERC) if you remortgage before the deal ends. Most lenders waive the ERC during a window (typically 3 to 6 months before the deal end date), allowing you to remortgage penalty-free. If you are still inside the ERC period, remortgaging early may cost you thousands of pounds, so time your application to fall inside the penalty-free window.
2. Start Shopping for Rates 3 to 6 Months Early
Begin comparing remortgage offers 3 to 6 months before your deal ends. Mortgage offers are typically valid for 3 to 6 months, so applying early means your new rate is locked in and ready to start the day your old deal expires.
Use comparison sites, speak to a mortgage broker, or check rates directly with lenders. Compare:
- Interest rate and APRC: the rate you will pay and the annual percentage rate of charge, which includes fees.
- Product fees: arrangement or product fees can range from zero to £2,000 or more, affecting the true cost.
- Deal length: 2-year, 3-year, 5-year, or 10-year fixed-rate deals, or tracker mortgages that follow the Bank of England base rate.
- Early repayment charges: check the new deal’s ERC terms if you might move or remortgage again soon.
A product transfer (staying with your current lender) is faster and cheaper than switching lender, as it skips the valuation and conveyancing. However, you may find a better rate by switching, so compare both options. According to MoneyHelper, shopping around for remortgage rates can save you significant money over the life of the loan.
3. Apply for Your New Mortgage
Once you have chosen a rate, submit your application. You will need:
- Proof of income (payslips, tax returns, accounts if self-employed).
- Proof of identity and address.
- Details of your current mortgage balance and property value.
- Bank statements showing your spending and affordability.
Your new lender will carry out an affordability assessment and, if you are switching lender, instruct a valuation of your property. The application and underwriting process typically takes 2 to 6 weeks, longer if documentation is incomplete or the valuation is delayed.
If you are taking a product transfer with your current lender, the process is faster (often 1 to 2 weeks) because no new valuation or conveyancing is required.
Read also: When to Remortgage and How to Get the Best Rate in the UK
4. Complete the Switch Before Your Deal Ends
Coordinate the completion date so your new mortgage starts the day your old deal ends. This timing avoids any gap where you revert to the SVR, even for a single day.
If you are switching lender, your solicitor will handle the legal transfer of the mortgage. The new lender pays off your old mortgage on completion day, and your new rate begins. If you are taking a product transfer, your lender simply switches you to the new rate on the agreed date.
Confirm the completion date in writing and check your mortgage statement after the switch to ensure the new rate has been applied correctly.
Tips for a Smooth Remortgage
- Start early: Apply 3 to 6 months before your deal ends to allow time for underwriting, valuation, and any delays.
- Check your credit file: A good credit score improves your chances of approval and may qualify you for better rates. Correct any errors on your credit report before applying.
- Consider overpaying: If your new deal allows penalty-free overpayments (typically up to 10 per cent of the balance per year), overpaying reduces the balance and saves interest.
- Factor in fees: A low rate with high fees may cost more overall than a slightly higher rate with low or no fees. Use a mortgage calculator to compare the total cost over the deal period.
Common Mistakes to Avoid
- Waiting until the deal ends: Applying too late means you may miss the penalty-free window and face ERCs, or you revert to the SVR while your application is processed.
- Not comparing product transfers: Your current lender’s product transfer may not be the best rate available. Always compare it against rates from other lenders.
- Ignoring the total cost: Focusing only on the interest rate and overlooking arrangement fees, valuation fees, and legal fees can mean you choose a more expensive deal.
Frequently Asked Questions
Can I remortgage before my deal ends without paying an ERC?
Yes, if you are inside the penalty-free window (typically 3 to 6 months before your deal ends). Outside this window, you will face an ERC unless your lender waives it.
How long does remortgaging take?
Switching lender takes 4 to 8 weeks on average, while a product transfer with your current lender takes 1 to 2 weeks. Start early to complete the switch before your deal ends.
What if I miss the deadline and revert to the SVR?
You can remortgage at any time, but while on the SVR your monthly payments will be higher. Complete the remortgage as quickly as possible to return to a lower rate.
Conclusion
Remortgaging before year-end protects you from reverting to your lender’s expensive standard variable rate. Start comparing rates 3 to 6 months before your deal ends, apply inside the penalty-free window, and coordinate the completion date to switch seamlessly to a better rate. Whether you choose a product transfer or switch lender, acting early ensures you avoid the SVR and keep your mortgage costs down.
Your home may be repossessed if you do not keep up repayments on your mortgage.
The information in this article is general educational information about remortgaging in the UK and is not regulated mortgage advice, personalised financial advice, or legal advice. Refisage is not authorised by the Financial Conduct Authority. Mortgage rates, products, eligibility, fees, and early repayment charges vary by lender, product, and your personal circumstances. Stamp duty and government schemes differ across England, Scotland, Wales, and Northern Ireland. Rates and terms were current as of October 2026; verify current offers with an FCA-authorised mortgage adviser or lender before making any decision. For personalised guidance on whether to remortgage, which product to choose, or how remortgaging affects your situation, speak to an FCA-authorised mortgage adviser or consult MoneyHelper.
Sources
- Remortgaging (accessed )
- Financial Conduct Authority (accessed )
- Mortgages (accessed )
- Principles of Finance (accessed )
Related articles
When to Remortgage and How to Get the Best Rate in the UK
Learn when to remortgage in the UK, how to compare deals, and whether switching lenders will save you money after fees and early repayment charges.
7 Key Steps to Remortgaging in the UK: When to Switch and How to Get the Best Rate
Discover when to remortgage in the UK and how to secure the best rate. A 7-step guide covering deal periods, early repayment charges, and comparison tips.
A Complete Guide to Remortgaging in the UK: When to Switch and How to Get the Best Rate
Learn when to remortgage in the UK, how to compare deals, avoid early repayment charges, and secure the best rate for your circumstances.
