How Debt-to-Income Ratio Affects Home Loan Approval in Australia
Learn how Australian lenders use your debt-to-income ratio to assess home loan applications and discover practical steps to improve your borrowing capacity.
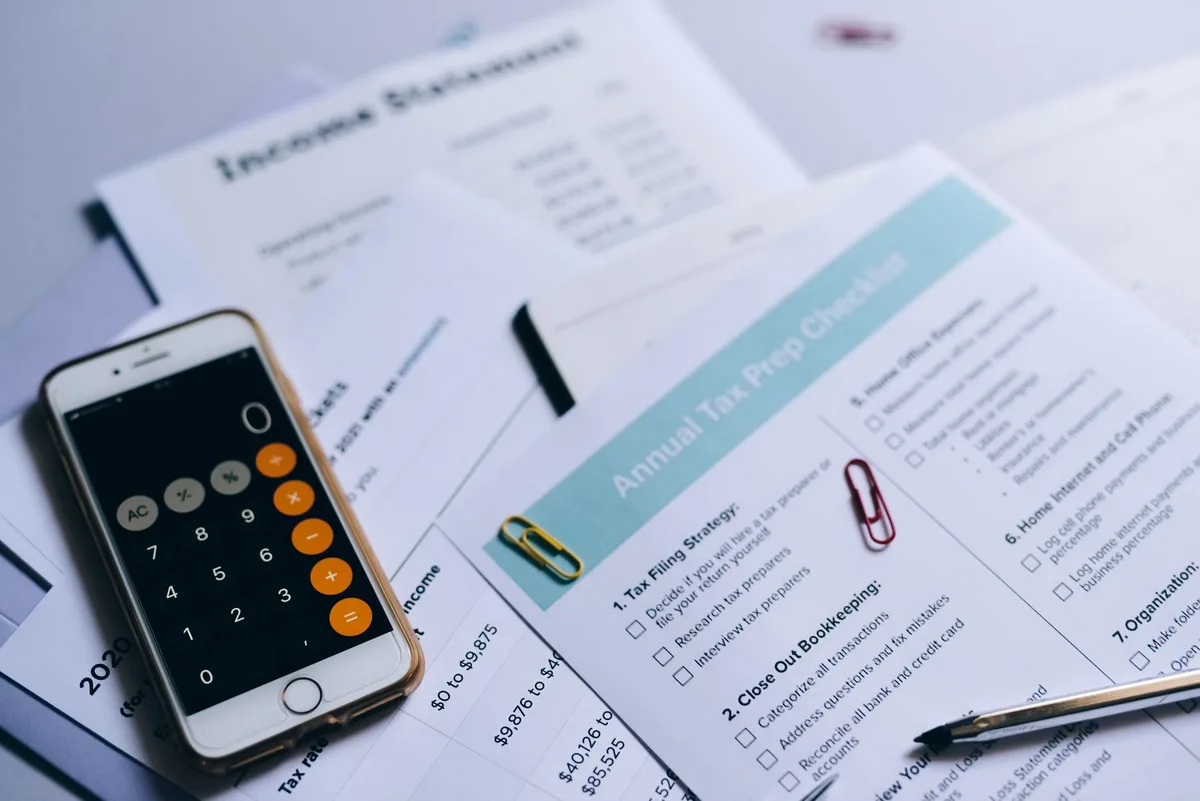
Pexels - Mikhail Nilov · original
In this article
Key Takeaway
Your debt-to-income (DTI) ratio measures how much of your gross income goes towards servicing debt each month. Australian lenders use this ratio, alongside other serviceability measures, to determine whether you can afford a home loan. A lower DTI ratio (typically below 30 to 35 per cent) improves your approval chances, while a higher ratio may limit your borrowing capacity or require a larger deposit.
Introduction
When you apply for a home loan in Australia, lenders assess your ability to repay the loan through a process called serviceability assessment. One of the most important measures in this assessment is your debt-to-income (DTI) ratio. Understanding how this ratio works and what lenders expect can help you prepare a stronger application and potentially increase your borrowing capacity.
What You Will Learn
This guide explains how Australian lenders calculate and use your DTI ratio during the home loan approval process. You will learn what DTI thresholds lenders typically accept, how the ratio interacts with other serviceability measures, and practical steps you can take to improve your DTI before applying for a loan.
Step 1: Understand What Debt-to-Income Ratio Means
Your debt-to-income ratio expresses your total monthly debt repayments as a percentage of your gross monthly income. According to ASIC MoneySmart, lenders use this measure to assess whether you have sufficient income to service a new home loan alongside your existing financial commitments (MoneySmart, 2024).
The calculation includes all recurring debt: credit card minimum repayments, personal loans, car loans, existing home loans, and other credit commitments. It does not include everyday living expenses such as groceries, utilities, or insurance, which are assessed separately through your household expenditure statement.
Step 2: Learn How Lenders Calculate Your DTI
Australian lenders calculate DTI by dividing your total monthly debt obligations by your gross monthly income (before tax). For example, if your gross monthly income is A$8,000 and your total monthly debt repayments amount to A$2,400, your DTI ratio is 30 per cent.
Lenders typically assess DTI on a pre-approval basis using the loan amount you are applying for, not just your current debts. They calculate what your repayments would be on the new home loan at an assessment rate (usually 2 to 3 percentage points above the actual advertised rate) and add this to your existing commitments.
The Australian Prudential Regulation Authority (APRA) has provided guidance to lenders on responsible lending practices, which includes monitoring DTI ratios across their loan portfolios (APRA, 2024). While APRA does not set a universal DTI limit, lenders have their own internal thresholds.
Step 3: Know the DTI Thresholds Lenders Use
Most Australian lenders prefer a DTI ratio below 30 to 35 per cent for standard home loan applications. Applicants with ratios between 35 and 40 per cent may still be approved but could face higher interest rates, lower loan-to-value ratios (requiring a larger deposit), or the requirement to take out lenders mortgage insurance (LMI) if the deposit is under 20 per cent.
Ratios above 40 per cent are generally considered high risk. Lenders may decline the application or require significant compensating factors such as a substantial deposit (30 per cent or more), strong savings history, or additional security.
These thresholds vary by lender and are not fixed regulatory limits. Some lenders apply more conservative criteria, while specialist lenders may accept higher ratios for borrowers with strong income stability or professional qualifications.
Step 4: Improve Your DTI Before Applying
If your DTI ratio is higher than you would like, you can take several steps to improve it before submitting a home loan application:
Pay down existing debts. Reducing the balance on credit cards, personal loans, or car loans lowers your monthly repayment obligations and directly improves your DTI.
Close unused credit accounts. Even if you do not carry a balance, lenders calculate your potential debt based on credit limits. Closing cards or reducing credit limits decreases this assessed liability.
Read also: How to Get a Home Loan as a Self-Employed Borrower in Australia
Increase your income. Taking on additional work, securing a pay rise, or including a second applicant with stable income can lower your DTI by increasing the denominator in the ratio.
Delay the application. If your DTI is borderline, waiting several months while you pay down debt or build savings can improve your serviceability profile and potentially secure better loan terms.
Common Mistakes to Avoid
Underestimating your debt obligations. Lenders assess credit card limits at their full potential, not your current balance. A A$10,000 credit limit with a zero balance is still calculated as if you owe the minimum monthly repayment on the full amount.
Ignoring household living expenses. DTI is only one part of serviceability. Lenders also assess your net surplus income after living expenses, so cutting unnecessary spending improves your overall financial position.
Applying without pre-approval. Submitting a formal application with a high DTI can result in a declined application, which appears on your credit file. Seeking pre-approval or consulting a mortgage broker first allows you to understand your position without a formal credit inquiry.
Frequently Asked Questions
Does DTI include rent or mortgage repayments? Yes, if you currently have a mortgage or are paying rent, lenders factor these into your overall financial commitments, although rent is typically assessed under living expenses rather than the DTI calculation itself.
Can I still get a home loan with a high DTI? It is possible, but you may need a larger deposit, accept a higher interest rate, or seek out a specialist lender. A mortgage broker can help identify lenders with more flexible DTI criteria.
How does DTI differ from the loan-to-value ratio? DTI measures your debt repayments against income, while loan-to-value ratio (LVR) measures the loan amount against the property value. Both are used in serviceability assessment but assess different aspects of risk.
Conclusion
Your debt-to-income ratio is a key factor in Australian home loan approval, and understanding how lenders calculate and use this measure gives you a clearer path to securing finance. By managing existing debts, optimising your credit profile, and preparing your finances before you apply, you can improve your DTI and increase your borrowing capacity. For personalised advice on your situation, consult a licensed mortgage broker or lender who can assess your full financial profile and recommend suitable loan products.
As covered in Principles of Finance, understanding debt ratios is fundamental to responsible borrowing and financial planning (OpenStax, 2024).
General Advice Warning: The information provided in this article is general in nature only and does not consider your objectives, financial situation, or needs. You should consider obtaining personal advice from a licensed mortgage broker or financial professional before acting on any information in this article. This is not personalised financial, lending, or legal advice.
Rates and Terms Disclaimer: Interest rates, loan terms, eligibility criteria, and fees vary by lender, product, and your personal circumstances. Advertised rates differ from the comparison rate, which includes most fees and charges. Information is current as of September 2026; rates and lending criteria change frequently. Always verify current terms with a licensed lender or mortgage broker before making any decision. Lenders mortgage insurance (LMI), deposit requirements, and approval conditions vary. Consult a licensed professional for advice tailored to your situation.
Sources
- Home Loans (accessed )
- APRA Home Loans Information (accessed )
- Principles of Finance (accessed )
- Home Loans Comparison (accessed )
Related articles
How to Get a Home Loan as a Self-Employed Borrower in Australia
Learn how self-employed Australians qualify for home loans with low-doc or full-doc applications, lender serviceability criteria, and required financial proof.
The Impact of Rising Interest Rates on Mortgage Borrowing Capacity in Australia
Rising interest rates reduce how much you can borrow in Australia. Understand serviceability tests, the APRA buffer rate, and how rate changes affect your mortgage capacity.
First Home Buyer Guide to Getting a Home Loan in Australia
Learn the essential steps first home buyers need to follow to secure a home loan in Australia, from deposit savings to government schemes.
