Break Costs on Fixed Home Loans in Australia: How They Are Calculated
Break costs compensate lenders when you exit a fixed-rate home loan early. Learn how Australian lenders calculate these fees and what factors determine the amount you may owe.
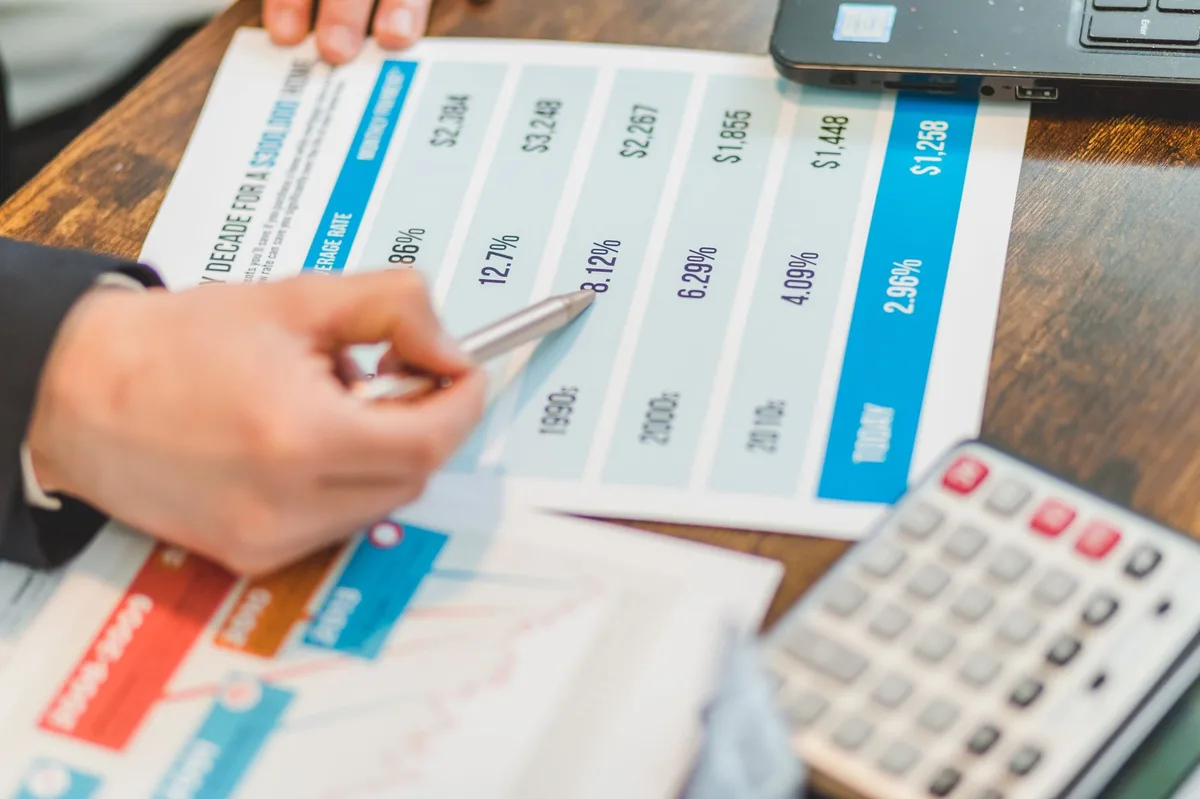
Pexels - RDNE Stock project · original
In this article
Key Takeaway
Break costs (also called economic costs or early repayment adjustments) are fees charged by Australian lenders when you exit a fixed-rate home loan before the fixed term ends. The amount compensates the lender for the interest income they lose, and is calculated based on the difference between your locked rate and current market rates, the remaining loan balance, and time left on your fixed term. Break costs can range from zero to tens of thousands of dollars depending on how much interest rates have moved since you fixed your loan.
Introduction
When you lock in a fixed-rate home loan in Australia, you commit to a set interest rate for a specific period (commonly one to five years). If you need to exit that loan early (by refinancing, selling your property, or making large extra repayments beyond any allowance), your lender may charge break costs to recover the financial loss they incur. Understanding how these costs are calculated helps you make informed decisions about fixed loans and when to refinance.
What Are Break Costs?
Break costs are a fee that compensates the lender for the economic loss they experience when a fixed-rate loan is paid off before the agreed fixed term expires. According to ASIC MoneySmart, lenders fund fixed-rate loans by borrowing money in wholesale markets at a rate that matches your loan term. When you exit early, the lender must reinvest that returned capital at the current (often lower) wholesale rate, creating a shortfall in expected interest income.
The concept of compensating lenders for early contract termination is covered in foundational finance texts such as Principles of Finance, which explain how fixed-income agreements create obligations for both parties and how termination costs reflect the present value of lost cash flows.
Why Break Costs Exist
Lenders offer fixed-rate home loans by locking in their own funding costs for the same period. If you agreed to pay 4.5 per cent for three years but exit after one year, and wholesale rates have since fallen to 3.0 per cent, the lender can only reinvest your repaid principal at that lower rate. The difference between what you would have paid (4.5 per cent) and what the lender can now earn (3.0 per cent) over the remaining two years represents the lender’s loss, which break costs aim to recover.
Importantly, break costs only apply when rates have fallen since you fixed your loan. If rates have risen, there is typically no break cost because the lender can reinvest your principal at a higher rate than your original fixed rate.
How Break Costs Are Calculated
Australian lenders use a formula that considers three main factors:
- The interest rate differential: The difference between your fixed rate and the current wholesale rate (the rate at which the lender can reinvest your funds) for the remaining fixed period.
- The remaining loan balance: The principal amount still outstanding on your loan.
- The remaining time on your fixed term: How many months or years are left until your fixed period would naturally expire.
The general calculation structure is:
Break cost = (Your fixed rate - Current wholesale rate) × Remaining loan balance × Remaining time
The result is then discounted to present value, meaning the lender calculates what that future loss is worth in today’s dollars. Each lender may use a slightly different wholesale rate benchmark or discount method, which is why break costs can vary between lenders for the same scenario.
Read also: How to Refinance Your Australian Home Loan and Save on Interest in Australia
Factors That Affect Break Cost Amounts
Several variables determine whether you will face a large break cost, a small one, or none at all:
- Movement in interest rates: If the RBA has cut the cash rate (as tracked by the Reserve Bank of Australia) and wholesale rates have dropped significantly since you fixed your loan, break costs will be higher. If rates have risen or stayed flat, break costs are typically zero.
- Time remaining: The more time left on your fixed term, the larger the potential break cost, because the lender loses interest income over a longer period.
- Loan size: A larger outstanding balance means more principal being reinvested at a lower rate, increasing the loss to the lender.
- Lender policy and wholesale rate used: Different lenders use different wholesale benchmarks (bank bill swap rates, bond yields, or internal funding costs), which can lead to variation in break cost calculations even under identical circumstances.
Australian Context and Examples
As of August 2026, break costs remain a significant consideration for Australian borrowers with fixed-rate home loans. During periods when the RBA has reduced the cash rate, many borrowers who locked in higher fixed rates one to three years earlier face substantial break costs if they attempt to refinance.
For example, if you have a A$400,000 fixed loan at 5.0 per cent with two years remaining on the fixed term, and current wholesale rates have fallen to 3.5 per cent, your lender might calculate a break cost of A$10,000 to A$15,000 (the exact amount depends on the lender’s formula and discount method). Conversely, if rates have risen since you fixed your loan, your break cost would be zero.
According to Finder Australia, borrowers should request a break cost estimate from their lender before committing to refinance or sell, as the fee can sometimes exceed the savings from switching to a lower rate.
How to Avoid or Minimise Break Costs
- Wait until the fixed term expires: The simplest way to avoid break costs is to remain in your fixed loan until the agreed term ends, then refinance or switch to a variable rate.
- Choose a shorter fixed term initially: Fixing for one or two years instead of three to five years reduces the risk of being locked in if rates fall.
- Check for partial offset or redraw allowances: Some fixed loans permit limited extra repayments (for example, up to A$10,000 or A$20,000 per year) without triggering break costs. Confirm the terms with your lender.
- Consider a split loan: A split loan combines a fixed portion and a variable portion, giving you flexibility to pay extra or refinance the variable portion without incurring break costs on the entire loan.
- Request a break cost estimate before acting: Lenders are required to provide an estimate if you ask, allowing you to compare the cost against the potential benefit of refinancing or exiting early.
Conclusion
Break costs on fixed-rate home loans in Australia are calculated to compensate lenders for the economic loss they incur when borrowers exit a fixed term early. The fee depends on the difference between your locked rate and current wholesale rates, the size of your remaining loan balance, and the time left on your fixed period. Understanding this calculation helps you weigh the true cost of refinancing or selling before your fixed term expires, and informs your choice of loan structure and term length at the outset.
If you are considering exiting a fixed loan early, always request a break cost estimate from your lender first, and compare that cost to the potential savings or benefits of your intended action. Rates, eligibility, and break cost formulas vary by lender and change over time; confirm current terms with a licensed mortgage broker or lender for advice tailored to your circumstances.
General Advice Warning
The information in this article is general in nature only and does not consider your personal objectives, financial situation, or needs. You should consider obtaining personal advice from a licensed mortgage broker or financial professional before acting on any information provided. This article is not personalised financial, lending, or legal advice. Advertised rates differ from the comparison rate, which includes most fees and charges. Rates and loan terms mentioned are illustrative and change frequently; verify current offers with a licensed lender or broker before making any decision. Break cost calculations, eligibility criteria, and lender policies vary by institution and your individual circumstances. Always confirm the specific terms, fees, and break cost estimate with your lender before exiting a fixed-rate loan early.
Sources
- Home Loans (accessed )
- Reserve Bank of Australia (accessed )
- Home Loans Comparison (accessed )
- Principles of Finance (accessed )
Related articles
How to Refinance Your Australian Home Loan and Save on Interest in Australia
Refinance your Australian home loan to save on interest. Learn when it makes sense, how to switch lenders, and what to watch for.
When Does It Make Sense to Refinance Your Mortgage in Australia
Discover when refinancing your home loan makes financial sense in Australia, including break costs, comparison rates, and how to maximise savings.
How to Refinance Your Australian Home Loan and Save on Interest
Learn how refinancing your Australian home loan works, when to refinance, and how to save thousands on interest by switching lenders.
