Compare Big Four Home Loan Interest Rates in Australia: How Do CBA, NAB, ANZ and Westpac Stack Up?
A direct comparison of Commonwealth Bank, NAB, ANZ and Westpac home loan rates, features and what each major lender offers Australian borrowers.
Author
Writes about Australian home loans: offset accounts, lender mortgage insurance (LMI), and comparison rates, helping buyers and refinancers weigh the real cost of borrowing beyond the headline rate.

A direct comparison of Commonwealth Bank, NAB, ANZ and Westpac home loan rates, features and what each major lender offers Australian borrowers.

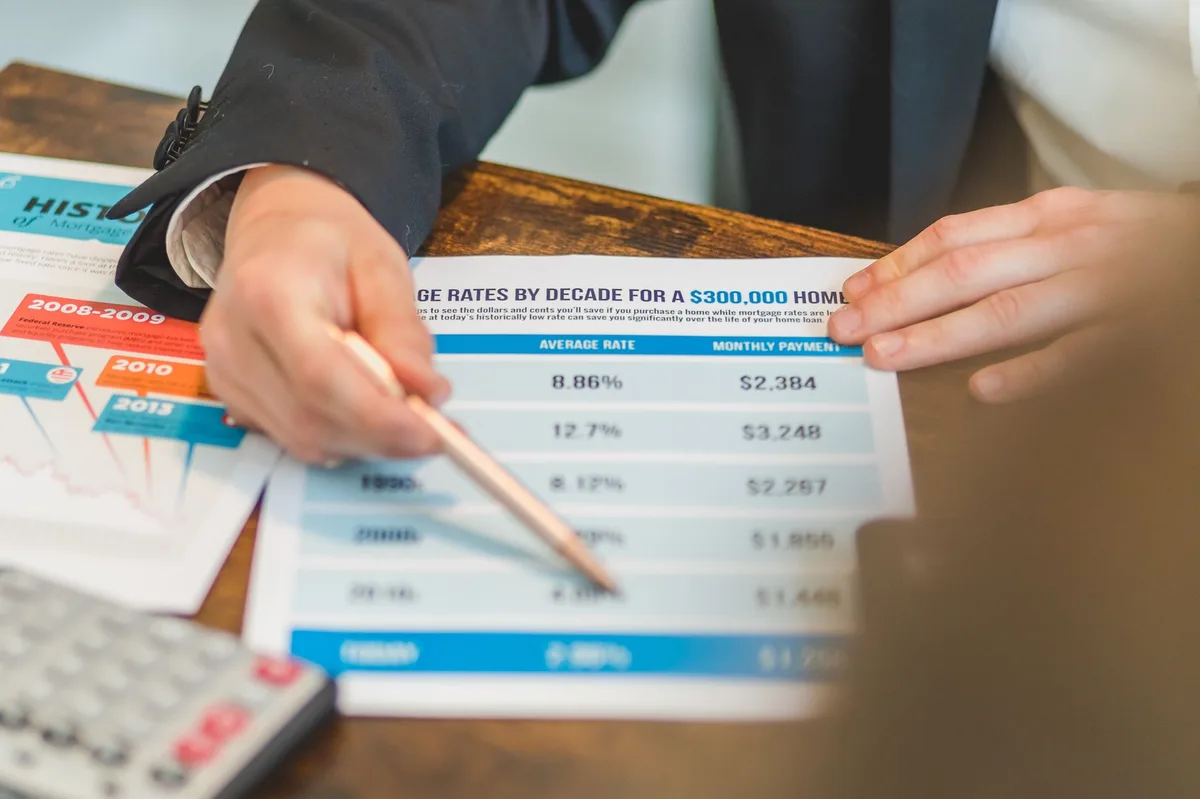
NAB-owned Ubank has launched a home loan requiring just a 10% deposit without lenders mortgage insurance (LMI) for eligible borrowers in Australia.

Understand the key differences between fixed-rate and variable-rate home loans in Australia and how to choose the right option for your circumstances.

Offset accounts and redraw facilities reduce the interest you pay by lowering your loan balance used for interest calculations or letting you access extra repayments.

Compare the best home loan cashback offers and refinance deals available in Australia, including what to look for and common pitfalls to avoid.

Compare the First Home Guarantee scheme against traditional home loans and LMI routes to find the best deposit strategy for your first home purchase.

The First Home Guarantee scheme offers limited places each financial year. Learn how many spots are available for 2027-28, when applications open, and how to secure your place before they run out.

Compare principal and interest loans with interest-only loans to understand repayment structures, costs, and which option suits your financial situation.

Essential checklist covering how construction loans work in Australia, from progress payments to practical completion.

Australian lenders accept gifted deposits from family but require a statutory declaration, proof of funds, and transfer evidence before settlement.

Repayment pauses and hardship arrangements offer short-term relief but can add thousands in interest and extend your loan term by years. Compare the true cost of each option before you choose.

Break costs compensate lenders when you exit a fixed-rate home loan early. Learn how Australian lenders calculate these fees and what factors determine the amount you may owe.

Self-employed Australians can secure home loans through low-doc or full-doc applications by meeting lender serviceability requirements with ABN records, tax returns, and consistent income proof.

Compare reverse mortgages with the government's Home Equity Access Scheme to decide which equity-release option suits your retirement income needs in Australia.

Compare fixed-rate and variable-rate home loans in Australia to decide which suits your budget, risk tolerance, and financial goals.

A clear guide to understanding stamp duty and land tax obligations when buying property in Australia, including state variations and exemptions.

Bridging loans let you buy your next home before selling your current property, but they come with higher costs and risks you need to understand first.

Refinancing your home loan can cut your interest rate and save thousands over the life of the loan. Learn when it makes sense and how to do it.

Learn how rental yield helps you assess investment property performance and what metrics separate strong property investments from weak ones in the Australian market.

Understand how LMI premiums are calculated on high-LVR home loans in Australia and use our calculator to estimate your cost before you apply.

Compare the true cost of paying LMI to enter the market sooner against waiting to save a 20 per cent deposit, with worked examples for Australian home buyers.

Learn how Australian homeowners can access the equity in their property to fund investments or home improvements, and understand the risks and requirements involved.

Learn how to evaluate comparison rates effectively when shopping for a home loan, including what the rate includes, how to use it alongside other factors, and common mistakes to avoid.

Depositing your tax refund into your mortgage offset account can save you thousands in interest while keeping your money accessible.

The Reserve Bank of Australia's July board meeting sets the cash rate, directly influencing variable home loan rates and monthly repayments for Australian borrowers.
The October 31 deadline for individual tax returns is approaching. Here's what rental property owners need to know about claiming deductions and finalising their EOFY claim.

An offset account can reduce the interest you pay on your home loan by thousands of dollars each year. Here's how offset accounts compare to redraw facilities and standard loans, and whether one suits your situation.

Refinancing offers more than just a lower rate. Discover how switching lenders can unlock offset accounts, access equity, remove LMI, consolidate debt, and give you better loan features tailored to your goals.

A mid-year review helps Australian landlords check whether a rental property is still meeting its income, debt, tax and risk goals. Focus on rent, loan costs, deductible expenses, cash flow, equity and the next six months of repairs or refinancing decisions.

Some Australian lenders have cut selected fixed home loan rates, but that does not automatically mean every borrower should fix. Compare the rate, comparison rate, fees and flexibility before switching.

As interest rates rise, many Australian households are facing severe mortgage stress, forcing a dangerous trade-off between keeping their homes and funding essential healthcare.

Stamp duty can be one of the biggest upfront costs when buying property in Australia. Estimate it by state or territory before you set your deposit target or sign a contract.

After months of declines, Australian mortgage and refinance rates rose in June 2026, reversing the downward trend borrowers had grown accustomed to.

Learn how to access and use your home equity responsibly, from calculating available equity to choosing the right method for your financial goals.

Learn how to time your fixed-rate lock when planning summer settlement, protect against rate rises, and avoid costly mistakes during peak property season.

Lenders mortgage insurance (LMI) is a one-off fee that protects your lender if you default on your home loan, typically required when your deposit is less than 20 per cent.

When the Reserve Bank changes the cash rate, a brief refinance window opens. Here is how Australian borrowers can assess whether to switch lenders in the days following an RBA decision.

Learn when refinancing your home loan can save you money and how to decide if switching lenders is the right move for your financial situation.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.