Fixed Versus Variable Home Loans in Australia Explained
Understand the key differences between fixed-rate and variable-rate home loans in Australia and how to choose the right option for your circumstances.
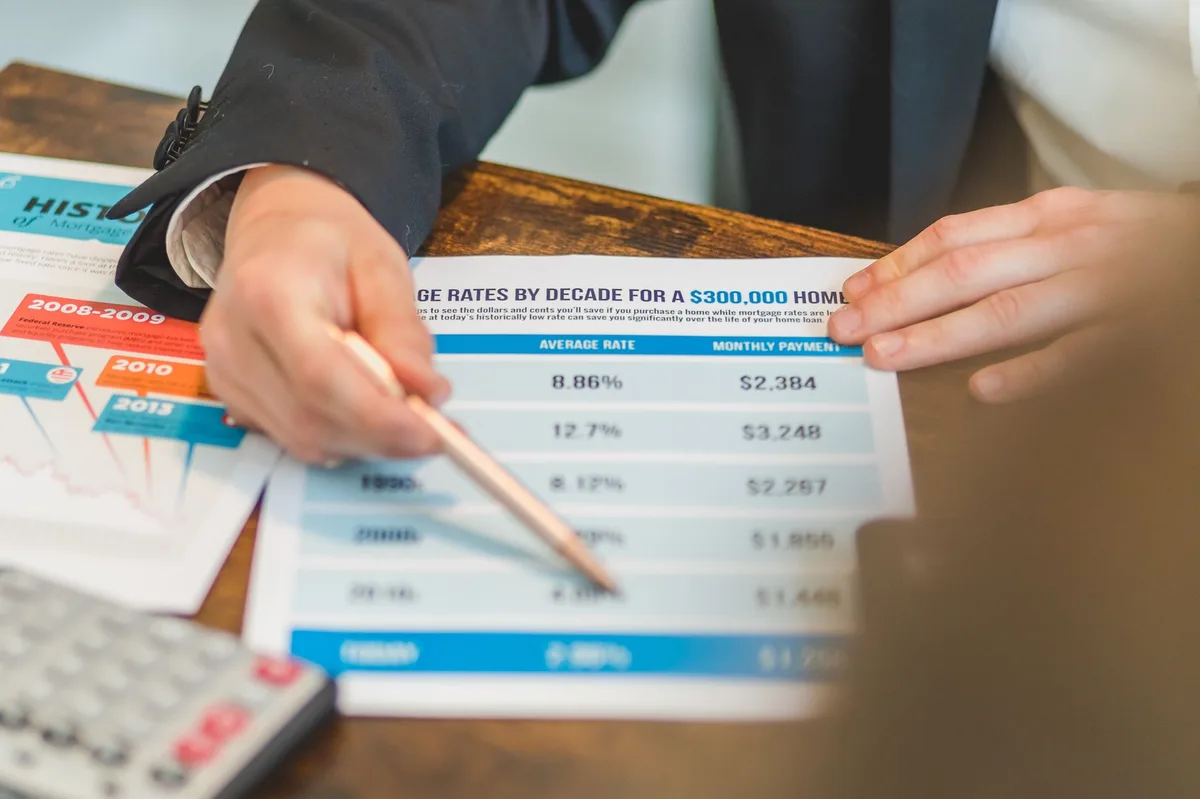
Pexels - RDNE Stock project · original
In this article
Key Takeaway
Fixed-rate home loans lock in your interest rate for a set period (typically one to five years), giving you predictable repayments regardless of RBA cash rate movements. Variable-rate home loans move up or down with the lender’s standard variable rate, which generally tracks the RBA cash rate, offering potential savings when rates fall but higher repayments when rates rise. Your choice depends on your tolerance for repayment changes, your view on future rate movements, and whether you value certainty over flexibility.
What Fixed-Rate Home Loans Are
A fixed-rate home loan keeps your interest rate constant for an agreed period, usually between one and five years. During this fixed period, your principal-and-interest repayments remain the same every month, making budgeting straightforward. According to ASIC MoneySmart, fixed-rate loans protect you from rate rises during the fixed term but also mean you miss out on rate cuts. At the end of the fixed period, the loan typically reverts to the lender’s standard variable rate unless you refinance or negotiate a new fixed term.
Fixed-rate loans often come with restrictions: many limit extra repayments to a capped amount per year (commonly A$10,000 to A$30,000), and breaking the fixed term early can trigger significant break costs if market rates have fallen since you locked in. Offset accounts and redraw facilities are less common or restricted on fixed loans compared to variable products.
What Variable-Rate Home Loans Are
Variable-rate home loans have an interest rate that can change at any time at the lender’s discretion. In practice, most lenders adjust their variable rates in response to movements in the RBA cash rate, the Reserve Bank of Australia’s monetary policy tool. When the RBA raises the cash rate, lenders typically pass the increase on to borrowers within weeks. When the RBA cuts the cash rate, variable rates generally fall too, though the size and timing of lender rate changes can vary.
Variable-rate loans usually offer more flexibility: you can make unlimited extra repayments without penalty, access redraw facilities to withdraw surplus payments, and link an offset account to reduce interest charges. As explained in foundational finance texts such as Principles of Finance, variable-rate debt carries interest-rate risk for the borrower, the possibility that rates rise and increase your repayment burden, but it also offers the upside of lower repayments if rates fall.
Key Differences Between Fixed and Variable
The main differences come down to certainty, flexibility, and cost. Fixed-rate loans deliver repayment certainty during the fixed term, protecting you from rate rises but locking you out of rate cuts. Variable-rate loans expose you to rate movements, both good and bad, but give you the freedom to repay faster without penalty and access features like offset accounts. According to Finder, the comparison rate (a standardised rate that includes most fees and charges) can differ substantially between fixed and variable products, so always compare the comparison rate as well as the advertised rate.
Read also: Home Loans and Interest Rates in Australia in 2026
Fixed loans often have lower advertised rates than variable loans when the market expects rates to rise, and higher advertised rates when the market expects cuts. Break costs on fixed loans can be significant if you sell the property, refinance, or want to pay off the loan during the fixed term.
Which Should You Choose?
Your choice depends on your personal circumstances and outlook. A fixed-rate loan may suit you if you want repayment certainty, if you are budgeting tightly and cannot absorb rate rises, or if you believe rates are more likely to rise than fall over the next few years. A variable-rate loan may suit you if you value flexibility to make extra repayments, if you want access to an offset account, or if you believe rates are more likely to fall or remain stable.
Many borrowers choose a split loan, splitting the loan amount between a fixed portion and a variable portion, to gain some certainty while retaining some flexibility. Rates change frequently, so verify current advertised rates and comparison rates with licensed lenders or a mortgage broker before deciding. Eligibility, fees, break costs, and product features vary by lender and product, and your choice should consider your financial situation, risk tolerance, and plans for the property.
General Advice Warning
The information in this article is general in nature only and does not consider your objectives, financial situation, or needs. You should consider obtaining personal advice from a licensed mortgage broker or financial adviser before acting on it. This article is not personalised financial, lending, or legal advice. Advertised rates as of October 2026 differ from the comparison rate, which includes most fees and charges. Rates change frequently, so confirm current terms with a licensed lender or broker for your personal situation. Eligibility, limits, fees, and product availability vary by lender, product, and your circumstances.
Sources
- Home Loans (accessed )
- Cash Rate (accessed )
- Home Loans (accessed )
- Principles of Finance (accessed )
Related articles
Home Loans and Interest Rates in Australia in 2026
Understand Australian home loans and interest rates in 2026, including variable and fixed rates, comparison rates, and factors affecting mortgage costs.
Home Loan Comparison Rate Explained in Australia: Why the Headline Rate Is Not the Full Story
The comparison rate reveals the true cost of an Australian home loan by including fees. Learn why the advertised rate alone misleads borrowers.
Fixed Versus Variable Home Loan Rates in Australia: Which to Choose
Compare fixed and variable home loan rates in Australia. Understand the key differences, risks, and benefits to choose the right rate type for your situation.
