Refinancing to a Different Lender in Australia: 6 Key Facts About Discharge Fees and Timing
Discharge fees and settlement timing can add hundreds of dollars and weeks to your refinancing process when switching lenders in Australia.
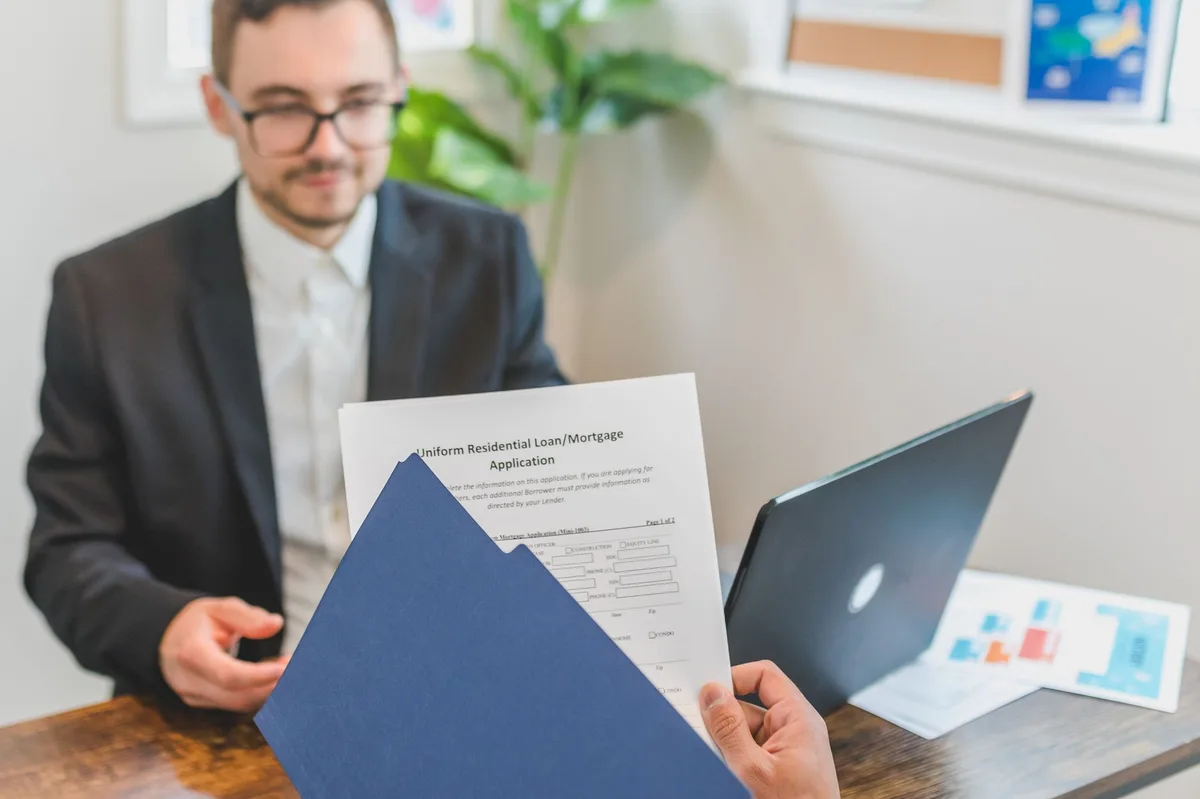
Pexels - RDNE Stock project · original
In this article
Key Takeaway
When refinancing your home loan to a different lender in Australia, expect to pay a discharge fee (typically A$150 to A$400) to your current lender, and allow 4 to 6 weeks for the full settlement process. If you are on a fixed-rate loan and break early, you may also face break costs that can reach thousands of dollars. Understanding these fees and timelines helps you plan your refinancing switch and avoid unexpected delays or expenses.
What You Need to Know About Switching Lenders
Refinancing to a different lender can save you thousands of dollars over the life of your home loan, but the process involves exit fees and administrative steps that take time and money. According to ASIC MoneySmart, discharge fees are standard when you pay out a mortgage and switch to a new lender, and the settlement timeline depends on how quickly both lenders and your conveyancer can process the paperwork.
As covered in foundational finance texts such as Principles of Finance, understanding the total cost of exiting one loan product and entering another is essential to determining whether refinancing will deliver net savings. Below are the six key facts you need to know about discharge fees and timing when switching lenders in Australia.
1. What Discharge Fees Cover
A discharge fee (also called a discharge administration fee or settlement fee) is what your current lender charges to release the mortgage over your property and prepare the necessary legal documents. The lender must remove its interest from the property title, lodge the discharge with the relevant state land titles office, and provide a payout statement to your new lender or conveyancer. This administrative work costs money, and most lenders pass that cost on to you as a one-time fee at settlement.
2. Typical Discharge Fee Amounts
Discharge fees in Australia generally range from A$150 to A$400, though some lenders charge more. The exact amount is set out in your loan contract (check the fees schedule or product disclosure statement). Major banks and non-bank lenders publish their discharge fees, and these are often listed in comparison tables on sites like Finder. Before you refinance, ask your current lender for a written payout quote that includes the discharge fee, so you know the total cost upfront.
3. Timeline for the Discharge Process
The full refinancing settlement process typically takes 4 to 6 weeks from the time your new loan is approved to the day your old loan is discharged and the new loan settles. The timeline breaks down as follows:
- Week 1 to 2: Your new lender completes final checks, orders a property valuation (if required), and issues formal loan approval.
- Week 2 to 4: Your conveyancer or solicitor prepares settlement documents, requests a payout figure from your old lender, and coordinates a settlement date with both lenders.
- Week 4 to 6: Settlement occurs (the new lender pays out the old loan), your old lender lodges the discharge with the land titles office, and the new mortgage is registered on the title.
Delays can occur if documents are incomplete, if your old lender is slow to provide the payout statement, or if there are title issues. Staying in close contact with your conveyancer and responding promptly to requests for information keeps the process on track.
4. Fixed-Rate Break Costs (If Switching Early)
If you are currently on a fixed-rate home loan and you refinance before the fixed term ends, you will likely face break costs (also called economic costs or early repayment fees). Break costs compensate the lender for the lost interest income and for unwinding the fixed-rate funding arrangement. The amount depends on how much time remains on your fixed term, the difference between your locked rate and current wholesale rates, and the remaining loan balance. Break costs can range from zero (if wholesale rates have risen since you fixed) to many thousands of dollars (if rates have fallen).
Your lender must provide a break cost estimate in writing before settlement. Factor this into your refinancing calculation: if the break cost is A$5,000 and your new loan will save you only A$2,000 over the next two years, the switch may not be worthwhile until closer to the end of your fixed term.
Read also: How to Refinance Your Australian Home Loan and Save on Interest in Australia
5. Other Exit Fees to Watch For
In addition to the discharge fee and potential break costs, check your loan contract for:
- Deferred establishment fees: Some lenders waive upfront establishment fees but charge them if you exit the loan within the first few years.
- Account closure fees: A small administrative fee (typically A$50 to A$100) for closing offset accounts or linked transaction accounts.
- Government fees: Your state land titles office charges a fee to register the discharge and the new mortgage (usually A$100 to A$200 combined, paid by your conveyancer and included in settlement costs).
Request a full payout statement from your current lender at least two weeks before your planned settlement date. The payout statement itemises all fees, the remaining principal, and interest calculated to the settlement date, so you and your new lender know the exact amount required to discharge the loan.
6. How to Minimise Costs and Delays
To keep discharge fees and settlement time under control:
- Shop around for refinancing offers with cashback or fee rebates: Many lenders offer cashback (typically A$2,000 to A$4,000) or waive application fees for refinancers, which can offset your discharge fee and other switching costs.
- Wait until your fixed term ends if break costs are high: Run the numbers and compare the total cost of breaking early against the savings from the new rate.
- Use an experienced conveyancer or mortgage broker: A professional who handles refinances regularly will anticipate potential delays and keep both lenders moving.
- Provide documents promptly: The faster you supply payslips, bank statements, and signed forms, the faster your new lender can settle.
- Confirm the settlement date with all parties: Make sure your current lender, new lender, and conveyancer all agree on the settlement date to avoid last-minute rescheduling.
Conclusion
Refinancing to a different lender in Australia involves a discharge fee (typically A$150 to A$400), a settlement timeline of 4 to 6 weeks, and potentially significant break costs if you are exiting a fixed-rate loan early. By understanding these fees and steps, you can budget accurately, avoid surprises, and complete your refinancing switch smoothly. Always request a detailed payout statement from your current lender, compare the total switching costs against your expected savings, and work with a licensed mortgage broker or conveyancer to keep the process on track.
Before refinancing, consider obtaining personal advice from a licensed mortgage broker or financial adviser who can assess your specific situation, compare current loan products, and confirm whether switching lenders will deliver a net benefit after all fees and break costs are accounted for.
General Advice Warning
The information in this article is general in nature only and does not take into account your personal objectives, financial situation, or needs. Discharge fees, break costs, settlement timelines, and loan terms vary by lender, product, and your individual circumstances. You should consider obtaining personal advice from a licensed mortgage broker or financial adviser before deciding to refinance. This article is not personalised financial, lending, or legal advice. Loan eligibility, fees, and interest rates change frequently. Verify current terms with a licensed lender or broker for your situation, and consult a qualified tax professional or legal adviser for personal cases.
Sources
- Home Loans (accessed )
- Home Loan Comparison (accessed )
- Australian Prudential Regulation Authority (accessed )
- Principles of Finance (accessed )
Related articles
How to Refinance Your Australian Home Loan and Save on Interest
Learn how refinancing your Australian home loan works, when to refinance, and how to save thousands on interest by switching lenders.
How to Refinance Your Australian Home Loan and Save on Interest in Australia
Refinance your Australian home loan to save on interest. Learn when it makes sense, how to switch lenders, and what to watch for.
How to Refinance Your Home Loan in Australia
Learn how to refinance your home loan in Australia with this step-by-step guide covering rate comparison, application, and settlement.
