How the Mortgage Stress Test Affects Your Renewal in Canada
The OSFI stress test typically does not apply when you renew with your current lender, but it does if you switch to a new lender at renewal, which can limit your options if you cannot re-qualify.
Pexels - RDNE Stock project · original
In this article
The Short Answer
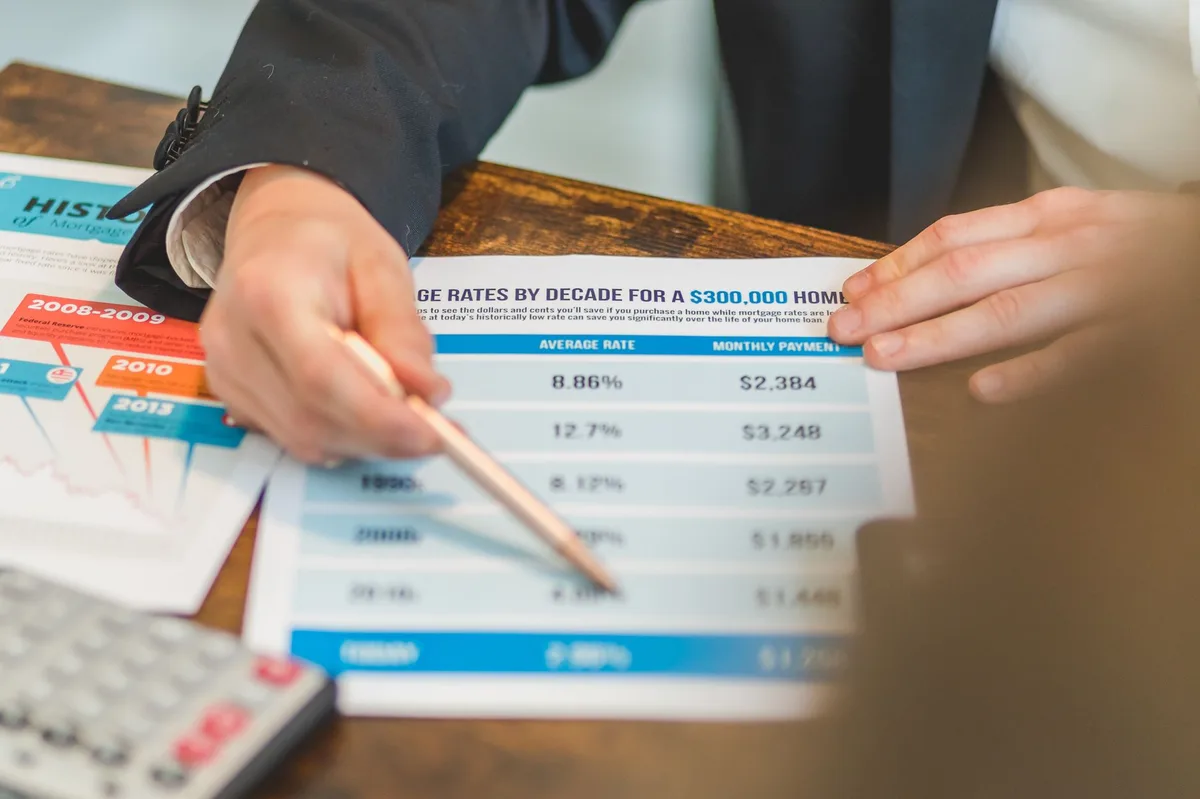
When you renew your mortgage with your current lender at the end of your term, you typically do not need to re-qualify under the OSFI mortgage stress test. However, if you want to switch to a different lender at renewal, the new lender will apply the stress test as part of their qualification process. This means that if your financial situation has changed or your loan-to-value ratio is high, you might not qualify to switch, effectively limiting your options to renewing with your existing lender (possibly at less competitive rates).
What Is the Mortgage Stress Test?
The mortgage stress test is a federal qualifying rule set out in the Office of the Superintendent of Financial Institutions’ Guideline B-20. It requires federally regulated lenders (banks, trust companies, and most major mortgage lenders) to qualify you at a rate higher than your actual contract rate. As of September 2026, you must qualify at the greater of your contract rate plus 2 percentage points or 5.25 per cent, whichever is higher.
The stress test ensures you can still afford your mortgage payments if interest rates rise. According to the Financial Consumer Agency of Canada, this rule applies at the time of purchase, refinancing, and when switching lenders, but not when you simply renew with your current lender (FCAC, 2026).
Stress Test at Renewal: Same Lender Versus Switching
When your mortgage term ends (typically after one to five years), you face a renewal. At this point, you renegotiate your rate and term, but the principal balance and amortization continue. If you renew with your current lender, the lender is not required to re-qualify you under the stress test. You can renew even if your income has dropped or your debt has increased, as long as you remain in good standing and have made your payments on time.
However, if you want to switch to a different lender at renewal to take advantage of a better rate or different terms, the new lender treats this as a new mortgage application and applies the full stress test. If you cannot qualify at the higher stress test rate (for example, because your income has declined, your debts have risen, or property values have fallen and your loan-to-value ratio is now too high), you will not be approved by the new lender. In that case, you must renew with your existing lender, who may offer you a less competitive rate because they know you are locked in.
This dynamic is sometimes called the “renewal lock-in effect.” Foundational financial texts such as Principles of Finance explain that borrower qualification rules directly influence market competition and the range of options available to consumers.
Why This Matters
The stress test creates an incentive structure at renewal. Borrowers who can still qualify under the stress test have leverage to shop around and negotiate better rates, because lenders know they can switch. Borrowers who cannot re-qualify are in a weaker bargaining position and may face higher rates at renewal.
Read also: Do You Need a Mortgage Stress Test to Switch Lenders in Canada?
The lock-in effect is particularly pronounced for variable-rate mortgage holders whose balances have grown due to rising payments, or for anyone whose loan-to-value ratio has increased because property values have declined. According to the Office of the Superintendent of Financial Institutions, the stress test is designed to protect borrowers and the financial system from over-leveraging, but it can constrain choice at renewal (OSFI, 2026).
What to Consider at Renewal
Before your term ends, check whether you can still qualify under the stress test. Use an online mortgage affordability calculator with the qualifying rate (your potential new rate plus 2 percentage points or 5.25 per cent, whichever is higher) to estimate your qualification limit. If you can qualify, request rate quotes from multiple lenders well before your renewal date (ideally 120 days out). If you cannot qualify to switch, focus on negotiating the best possible rate with your current lender, and consider making lump-sum prepayments to reduce your balance and improve your loan-to-value ratio before your next renewal.
Mortgage terms and qualification rules vary by lender and province. Rates change frequently, so verify current terms with a licensed mortgage professional before making decisions.
Next Steps
Contact a licensed mortgage broker or your current lender at least four months before your renewal date to review your options. If you can qualify under the stress test, compare offers from at least three lenders. If you cannot, ask your current lender for their best renewal rate and confirm there are no penalties for making prepayments during your next term.
Disclaimer: This article provides general educational information only and is not personalized financial, lending, legal, or tax advice. Mortgage qualification rules, the stress test, and available products vary by province, lender, and your individual circumstances. Rates and terms change frequently. Consult a licensed mortgage broker or financial institution for advice specific to your situation.
Sources
- Residential Mortgage Underwriting Practices and Procedures - Guideline B-20 (accessed )
- Mortgages (accessed )
- Principles of Finance (accessed )
- Home Buying (accessed )
Related articles
Mortgage Stress Test Requirement Lifted for Renewing Borrowers Who Switch Lenders in Canada
Learn how the 2024 policy change lets renewing Canadian borrowers switch lenders without the stress test, what it means for your renewal, and key limitations.
Do You Need a Mortgage Stress Test to Switch Lenders in Canada?
Learn when Canadian homeowners can switch mortgage lenders without a stress test, and when refinancing still triggers qualification.
Understanding the Mortgage Stress Test Exemption for Switching Lenders in Canada
Learn how the mortgage stress test exemption works for Canadians switching lenders, who qualifies, and how to use it to secure better rates.
