How to Refinance Your Mortgage in Canada: When It Makes Sense
Understanding mortgage refinancing in Canada, the difference between refinancing and renewal, and when breaking your current mortgage term makes financial sense.
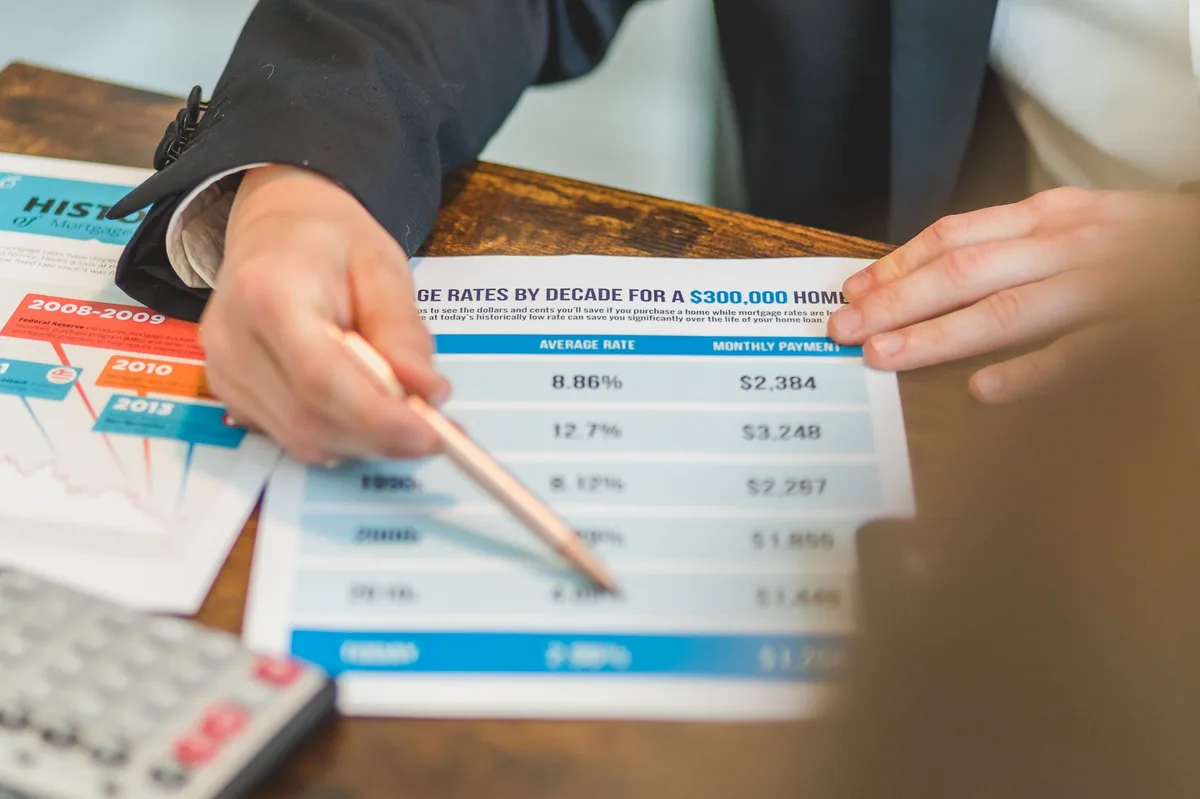
Pexels - RDNE Stock project · original
In this article
Key Takeaway
Refinancing your Canadian mortgage means replacing your existing mortgage with a new one before your current term ends, usually to access a lower interest rate, tap into home equity, or consolidate debt. It differs from renewal, which happens automatically at term end. Refinancing makes sense when the savings or benefits outweigh the prepayment penalties and closing costs, but the calculation depends on your remaining term, current rate, penalty structure, and financial goals.
What Mortgage Refinancing Means in Canada
Mortgage refinancing is the process of breaking your current mortgage contract and replacing it with a new mortgage, typically with different terms, a different rate, or from a different lender. When you refinance, you pay off your existing mortgage in full and take out a new loan, which may be for the same amount or a different principal depending on your needs.
In Canada, you can refinance to access up to 80 per cent of your home’s appraised value (the maximum combined loan-to-value ratio for refinancing), meaning you can borrow against the equity you have built. As covered in foundational finance texts such as Principles of Finance, leveraging home equity is a common strategy for accessing capital at relatively lower interest rates compared to unsecured credit.
Refinancing vs Renewal: A Critical Canadian Distinction
The most important concept to understand is the difference between refinancing and renewal. Canadian mortgages are structured with a term (typically one to five years) and an amortization period (commonly 25 or 30 years). At the end of each term, you renew your mortgage, renegotiating the rate and conditions for the next term. According to the Financial Consumer Agency of Canada, renewal happens at term end and does not normally trigger prepayment penalties (FCAC, 2026).
Refinancing, by contrast, means breaking your mortgage before the term ends. This triggers prepayment penalties, which can be substantial. Renewal is routine and expected, refinancing is a deliberate decision that comes with costs.
When Refinancing Makes Sense
Securing a Significantly Lower Interest Rate
If interest rates have dropped substantially since you locked in your current rate, refinancing may save you thousands over the life of the mortgage. The calculation depends on how much you will save monthly versus the penalty you will pay upfront. Generally, if the rate difference is 1.5 percentage points or more and you have several years left on your term, the math often works in your favour.
Accessing Home Equity for Major Expenses
Refinancing lets you borrow against the equity you have built, up to the 80 per cent loan-to-value cap. Homeowners commonly refinance to fund renovations, pay for education, or cover other large expenses. Because mortgage rates are lower than personal loans or lines of credit, this can be a cost-effective way to access capital (CMHC, 2026).
Consolidating High-Interest Debt
If you carry credit card balances or other high-interest debt, refinancing to roll that debt into your mortgage can lower your overall interest cost and simplify your payments. This strategy works best when the mortgage rate is substantially lower than your other debt, and when you commit to not running up new credit card balances.
Switching from Variable to Fixed (or Vice Versa)
Market conditions and personal risk tolerance change. If you are on a variable-rate mortgage and rates are rising, switching to a fixed rate through refinancing can lock in predictability. Conversely, if fixed rates are high and you expect the Bank of Canada to cut rates, moving to a variable product might save money, though this comes with interest rate risk.
Read also: How to Negotiate Your Best Mortgage Renewal Rate in Canada (2026-2027)
When Refinancing Does Not Make Sense
The Prepayment Penalty Outweighs the Benefit
Prepayment penalties in Canada can be steep, especially on fixed-rate mortgages. Lenders typically charge the greater of three months’ interest or the interest rate differential (IRD), which measures the cost to the lender of losing your higher-rate loan in a lower-rate environment. The IRD can run into tens of thousands of dollars if you have a long time remaining on your term and rates have dropped significantly. If the penalty is larger than the savings or benefits you will gain, refinancing does not make financial sense.
You Are Close to Renewal
If your term ends in six months or less, it is usually better to wait for renewal. At renewal, you can switch lenders or renegotiate terms without penalty. Refinancing a few months early rarely justifies the cost.
You Have Little Equity
If your home’s value has not increased much or you are early in your amortization, you may not have enough equity to make refinancing worthwhile, especially if you are trying to access cash. Lenders will appraise your home, and if the value does not support the loan-to-value ratio you need, refinancing may not be possible.
Your Credit Has Deteriorated
Refinancing requires re-qualifying under current lending standards, including the OSFI mortgage stress test. If your income has dropped, your debt load has increased, or your credit score has fallen, you may not qualify for the new mortgage or may only qualify at a higher rate, negating the benefit.
The Refinancing Process and Costs
Refinancing involves application, appraisal, legal work, and administrative steps similar to your original mortgage. According to RBC Royal Bank, you will need to provide updated income documentation, undergo a credit check, and have your home appraised (RBC, 2026).
Costs to budget for include the prepayment penalty (the largest cost), appraisal fees (typically a few hundred dollars), legal fees for discharging the old mortgage and registering the new one, and potentially a new title insurance policy. Some lenders offer to cover certain fees as part of a refinancing promotion, but the prepayment penalty is always your responsibility.
Conclusion
Refinancing your Canadian mortgage can be a powerful financial tool when used strategically. It makes sense when you can secure a materially lower rate, need to access equity for a sound financial purpose, or want to consolidate expensive debt, provided the penalty and closing costs do not erase your gains. It does not make sense when penalties are prohibitive, you are near renewal, or your financial situation has changed in ways that limit your options.
Before refinancing, calculate the total cost including penalties and fees, compare it against the benefit, and verify current rates with a licensed mortgage broker. Mortgage rules, penalties, and qualification requirements vary by lender and by province. This article provides general educational information only and is not personalized financial, lending, or legal advice. Consult a licensed mortgage professional or the FCAC for guidance specific to your circumstances.
Sources
- Mortgages: Understanding Your Rights and Responsibilities (accessed )
- Home Buying Step by Step (accessed )
- Mortgages (accessed )
- Principles of Finance (accessed )
Related articles
How to Navigate Mortgage Renewals in Canada When Rates Are Higher
Navigate your mortgage renewal when rates are high. Compare fixed vs variable, evaluate term lengths, and learn negotiation strategies for Canadian homeowners.
How to Negotiate Your Best Mortgage Renewal Rate in Canada (2026-2027)
Navigate the 2026-2027 mortgage renewal surge in Canada. Learn proven negotiation tactics to secure your best rate and save thousands on your term.
How to Negotiate Your Mortgage Renewal Rate in Canada
Negotiate a better mortgage renewal rate in Canada with these proven strategies. Learn when to start, how to leverage competing offers, and save thousands.
