Green Mortgages in the UK: Better Rates for Energy-Efficient Homes
Green mortgages reward energy-efficient homes with preferential rates and cashback incentives, helping UK borrowers save money while reducing carbon emissions.
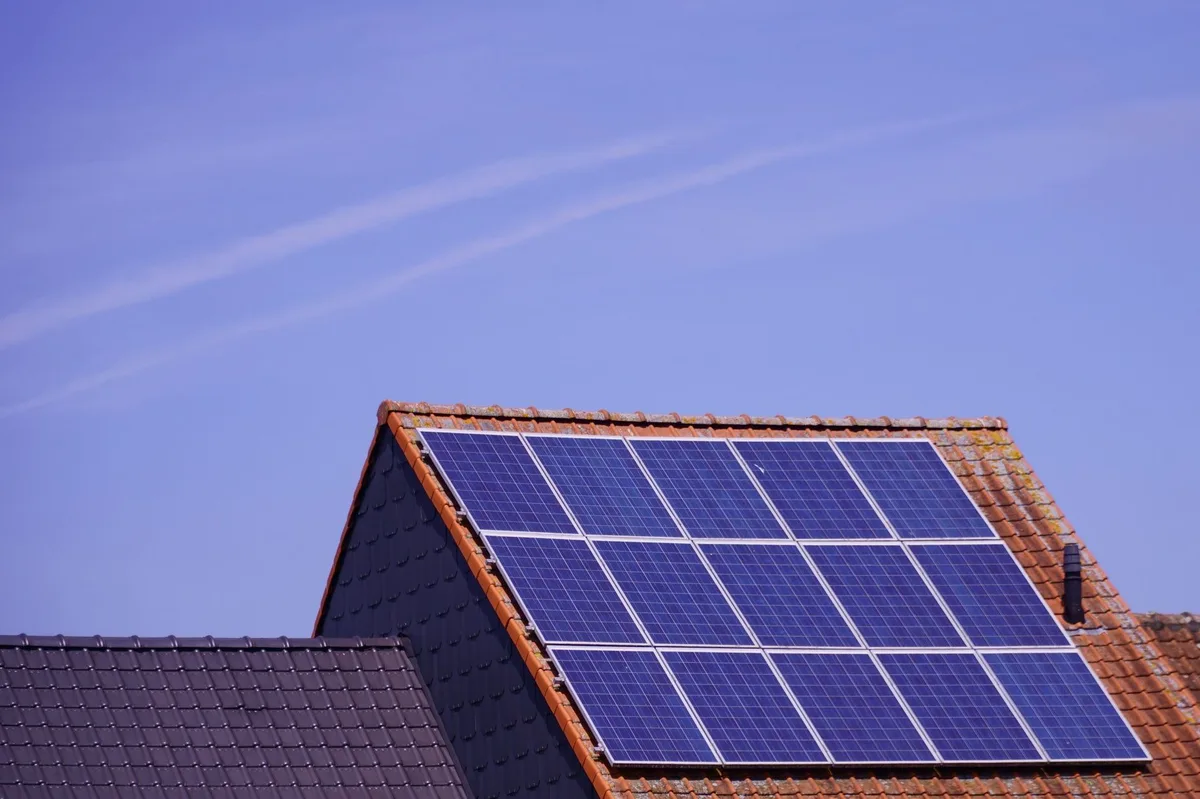
Pexels - D Goug · original
In this article
Key Takeaway
Green mortgages in the UK offer preferential interest rates, cashback, or fee reductions to borrowers buying or remortgaging energy-efficient homes. Properties with an Energy Performance Certificate (EPC) rating of A or B typically qualify, though some lenders accept C-rated homes undergoing energy improvements. The rate discount ranges from 0.10% to 0.50%, and many products include cashback of £500 to £2,000 to fund efficiency upgrades such as insulation, solar panels, or heat pumps.
What Is a Green Mortgage?
A green mortgage is a home loan designed to incentivise energy efficiency by rewarding borrowers who purchase, remortgage, or improve properties with strong environmental credentials. UK lenders offer lower interest rates, cashback, or reduced arrangement fees when the property meets specific energy performance standards, typically measured by the Energy Performance Certificate (EPC) rating system mandated across England, Scotland, Wales, and Northern Ireland.
Green mortgages align with the UK’s net-zero carbon targets and encourage homeowners to reduce energy consumption and carbon emissions. According to MoneyHelper, green mortgage products have grown substantially since 2020 as lenders respond to climate commitments and borrower demand for sustainable financing (MoneyHelper, 2026).
Why Green Mortgages Matter
Green mortgages deliver three interrelated benefits: financial savings for the borrower, reduced carbon emissions, and long-term property value protection.
Lower borrowing costs. The preferential rate or cashback reduces the total cost of the mortgage over the deal period. A 0.25% discount on a £250,000 fixed-rate mortgage saves approximately £600 per year, compounding over a typical two or five-year initial term.
Energy bill savings. Homes with EPC ratings of A or B consume far less energy for heating, lighting, and hot water than lower-rated properties. The resulting reduction in utility bills compounds the benefit of the lower mortgage rate, improving overall affordability.
Climate impact and resilience. Energy-efficient homes produce fewer carbon emissions and align with the UK’s 2050 net-zero commitment. Properties with robust insulation, efficient heating systems, and renewable energy sources are also more resilient to future regulatory changes, such as stricter minimum EPC requirements for rental properties or the phasing out of fossil-fuel heating systems.
As foundational texts such as Principles of Finance explain, the time value of money and compounding savings make even modest rate reductions financially significant over a mortgage term, particularly when combined with ongoing operational cost savings.
How Green Mortgages Work in the UK
Green mortgage products fall into two categories: purchase or remortgage deals for properties that already meet the energy performance threshold, and improvement mortgages that fund energy upgrades to bring a lower-rated property up to standard.
Eligibility criteria. Most UK lenders require an EPC rating of A or B, though some accept C-rated properties if the borrower commits to specified improvements within an agreed period (typically 12 to 24 months after completion). The EPC must be valid (less than ten years old) and provided at the mortgage application stage.
Rate structure and incentives. Green mortgages mirror standard mortgage products in structure (fixed-rate, tracker, or discount mortgages with repayment or interest-only terms) but offer a discounted rate or a cashback incentive. The rate reduction ranges from 0.10% to 0.50% depending on the lender and the EPC rating. Cashback, where offered, typically ranges from £500 to £2,000 and must be used for approved energy improvements such as insulation, double glazing, solar photovoltaic panels, heat pumps, or smart heating controls.
Read also: First-Time Buyer Autumn Guide: Mortgage, Stamp Duty, and Deposit Tips for the UK
Loan-to-value and affordability. Green mortgages follow the same affordability assessment and loan-to-value (LTV) limits as conventional products. Lenders assess income, outgoings, and credit history, and the maximum LTV depends on the borrower profile and property type. Green mortgage rates are available across LTV bands, from high-LTV first-time buyer deals to low-LTV remortgage products.
Regulatory oversight. Green mortgages are regulated mortgage contracts overseen by the Financial Conduct Authority (FCA). Lenders must ensure affordability, provide clear disclosure of terms, and comply with responsible lending standards (FCA, 2026).
UK Context and Examples
Green mortgages are offered by high-street banks, building societies, and specialist lenders. Barclays, NatWest, Nationwide, Santander, and TSB each publish green mortgage ranges, though specific product names, eligibility criteria, and incentive structures vary. According to MoneySavingExpert, comparing green mortgage deals across lenders is essential, as the rate discount and cashback terms differ significantly (MoneySavingExpert, 2026).
Example scenario. A first-time buyer purchasing a £300,000 new-build flat with an EPC rating of A qualifies for a five-year fixed green mortgage at 4.25%, compared to 4.50% on an equivalent standard product. The 0.25% discount saves approximately £750 per year during the deal period. If the lender also offers £1,000 cashback, the borrower can install smart thermostats or improve cavity wall insulation, further reducing energy bills.
Improvement mortgages. A remortgage borrower with a C-rated Victorian terrace can access a green mortgage product if they commit to upgrading the property to EPC B within 18 months. The lender releases the cashback on completion, and the borrower uses the funds to install external wall insulation and upgrade the boiler to a condensing model. Once the improvements are complete and the EPC is updated, the property benefits from lower running costs and enhanced resale value.
Conclusion
Green mortgages provide a practical financial incentive for UK homeowners to invest in energy-efficient properties and reduce carbon emissions. The combination of preferential interest rates and cashback for energy improvements lowers both borrowing costs and long-term energy bills, making green mortgages a compelling option for purchase, remortgage, and home improvement scenarios. As regulatory pressure to improve housing stock intensifies and energy costs remain volatile, properties with strong EPC ratings are likely to hold value more effectively than inefficient homes.
Borrowers considering a green mortgage should verify the property’s current EPC rating, compare green mortgage deals across multiple lenders, and confirm whether cashback terms align with planned improvements. Consulting an FCA-authorised mortgage adviser ensures the product matches personal affordability and long-term plans.
Important Information
This article provides general educational information about green mortgages in the UK and is not regulated mortgage advice or personalised financial, lending, or legal advice. Refisage is not authorised by the Financial Conduct Authority (FCA). Mortgage eligibility, rates, cashback terms, and energy performance requirements vary by lender, product, and your personal circumstances. Always verify current terms with an FCA-authorised mortgage adviser before making a decision.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Rates, cashback incentives, and green mortgage product availability change frequently. The information presented reflects the position as of October 2026; confirm up-to-date terms with an FCA-authorised lender or adviser for your specific situation.
Sources
- Buying a Home (accessed )
- Financial Conduct Authority (accessed )
- Mortgages (accessed )
- Principles of Finance (accessed )
Related articles
First-Time Buyer Mortgage Comparison: Fixed, Tracker, and Discount Options in the UK
Compare fixed-rate, tracker, and discount mortgages for UK first-time buyers. Understand pros, cons, and which mortgage type suits your situation best.
First-Time Buyer Autumn Guide: Mortgage, Stamp Duty, and Deposit Tips for the UK
UK first-time buyers: autumn mortgage tips, stamp duty relief guide, and deposit strategies. Navigate rates, AIP, and seasonal market conditions.
First-Time Buyer Guide to Getting a Mortgage in the UK
Learn how first-time buyers get a mortgage in the UK: deposit requirements, affordability checks, government schemes, and the application process.
