Mortgage
Interest-Only Mortgages: Risks UK Borrowers Need to Understand
Interest-only mortgages can lower monthly payments but carry significant repayment risks. Learn how they work and what UK borrowers must plan for.
Author
Writes about UK mortgages: remortgaging, first-time buyer schemes, and Help to Buy equity loans, explaining how Bank of England base-rate decisions flow through to tracker and fixed deals.
Interest-only mortgages can lower monthly payments but carry significant repayment risks. Learn how they work and what UK borrowers must plan for.
Green mortgages reward energy-efficient homes with preferential rates and cashback incentives, helping UK borrowers save money while reducing carbon emissions.
New-build properties in the UK often carry a premium over resale homes, and when the surveyor's valuation falls short of the purchase price, buyers face a deposit shortfall that can derail their mortgage.
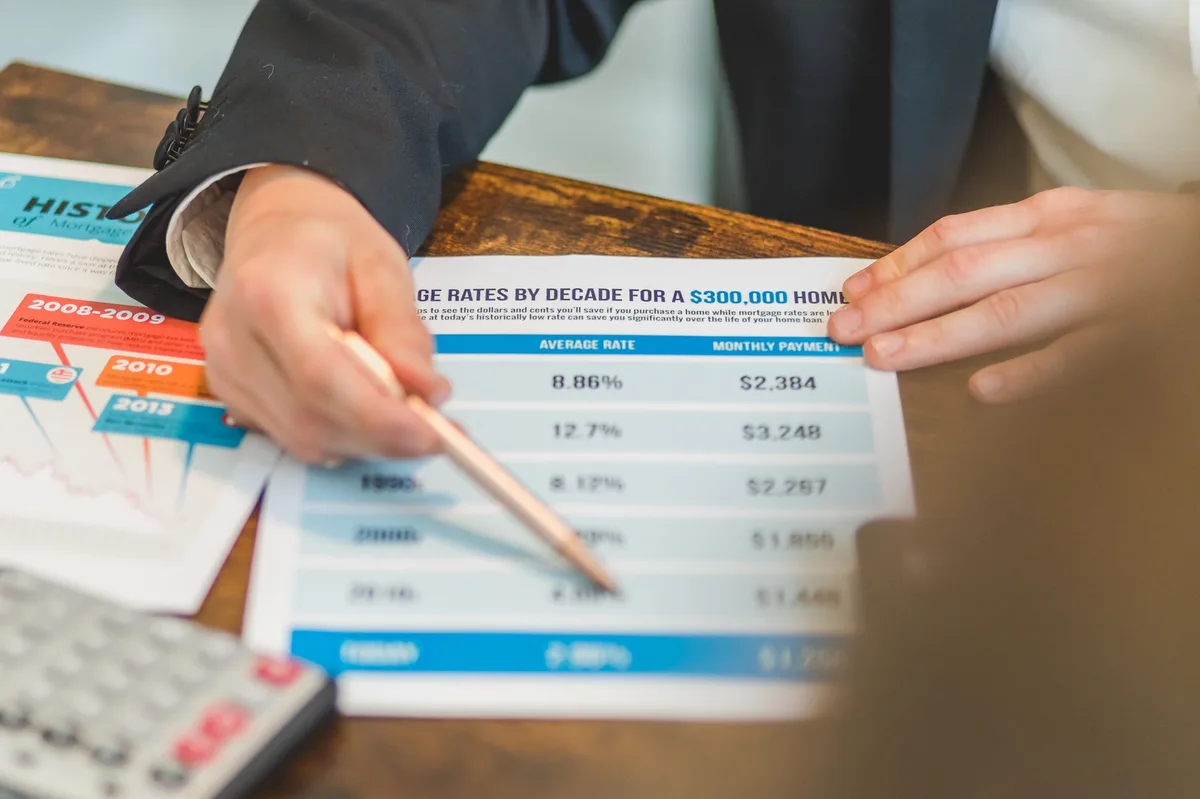
Early repayment charges penalise borrowers who overpay or remortgage during the deal period. Learn how UK lenders calculate ERCs and when they apply.
Self-build mortgages release funds in stages as your project progresses. Compare arrears-stage versus advance-stage models and choose the right release schedule for your build.
A down-valuation can upend your purchase. Learn what happens when the lender's valuation falls short of your offer and how to protect your deposit.
Missed payments do not automatically disqualify you from getting a mortgage in the UK. Specialist adverse credit lenders assess applications individually and may still approve you, though typically at higher rates and with a larger deposit required.
A joint borrower sole proprietor mortgage lets parents or family help with affordability without owning the property. Here's how it works and when it makes sense.
A practical guide to remortgaging in the UK, including when to switch deals, how to compare rates, and steps to secure the most competitive mortgage for your circumstances.
Understand how first-time buyers qualify for a mortgage in the UK, from deposit requirements to government schemes and the application process.
A practical checklist to help you strengthen your credit file and boost your chances of mortgage approval in the UK.
Learn how to compare two UK mortgage deals side by side to find which product costs less over the full term, accounting for rates, fees, and repayment structures.
A practical checklist to help you decide whether to use an FCA-authorised mortgage broker or apply directly to a UK lender.
Understand the fundamental difference between interest-only and repayment mortgages, how each works, and which structure might suit your financial circumstances.
Choosing between a fixed rate and tracker mortgage depends on your risk tolerance and rate forecasts. Here's how to decide which suits your circumstances in today's market.
UK lenders typically offer 4 to 4.5 times your annual income, but your actual borrowing limit depends on a detailed affordability assessment of income, outgoings, and financial commitments.
Learn the essential steps to secure your first mortgage in the UK, from checking affordability to completion.
Compare your remortgage options, learn the best time to switch deals, and discover how to secure competitive rates when your fixed term ends.
Rising mortgage rates hit first-time buyers hardest, reducing affordability and slowing the market, but widespread house price falls and collapsing chains remain unlikely in most UK regions.
Market analysts predict first-time buyers will drive UK property sales in 2026 as interest rate cuts improve mortgage affordability.
The Bank of England has kept the base rate at 3.75% for a second consecutive meeting. Here's what this means for your mortgage payments and savings returns.
Falling house prices do not usually change your current mortgage payment, but they can affect your equity, loan-to-value and remortgage choices.
If affordability checks stop you remortgaging, you may still have options with your current lender or through a specialist adviser. Start by finding the exact reason for the decline before applying again.
Remortgaging can still be worthwhile when rates have risen, but the best deal is not always the lowest headline rate. Compare total costs, timing, fees, ERCs, LTV bands, and whether a product transfer is enough.
Some UK buy-to-let lenders are improving remortgage pricing, but the lowest headline rate is not always the cheapest deal. Landlords should compare fees, rental cover, early repayment charges, and product transfer options before switching.
UK mortgage rates fell this week following positive developments in international diplomacy, offering potential savings for homebuyers and those remortgaging.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.