How to Close on a Home Before the End of 2026 in the US
Learn the timeline and essential steps to close on your home purchase before December 31, 2026, to maximize tax benefits and meet your year-end deadline.
Pexels - Ivan S · original
In this article
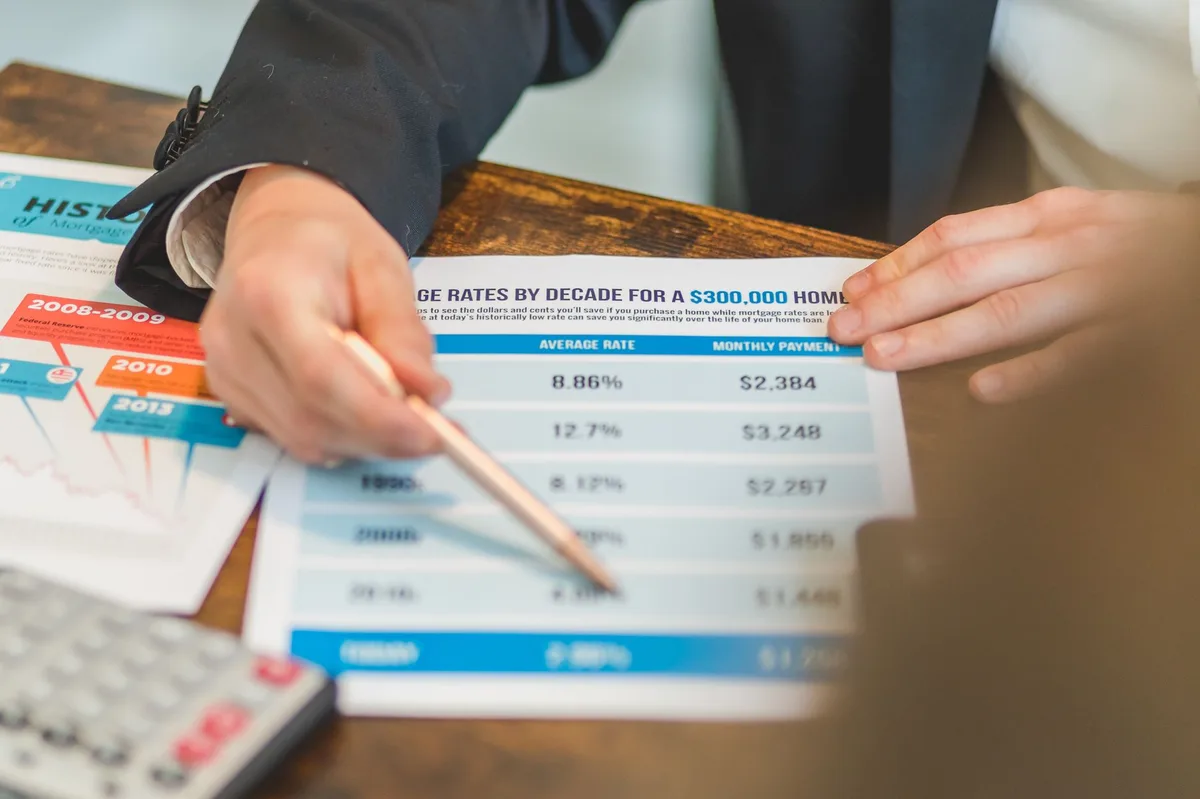
To close on a home before December 31, 2026, start the process no later than mid-October 2026. The typical purchase timeline runs 30 to 45 days from accepted offer to closing, but delays in underwriting, appraisals, or title work can push it longer. Buyers aiming for year-end closing should get pre-approved by early October, secure an accepted offer by mid-November at the latest, and build in buffer time for potential delays.
Many buyers target a year-end closing to claim mortgage interest and property tax deductions on their 2026 tax return. The IRS allows deductions for mortgage interest paid in the year of closing, and closing before December 31 ensures you capture those benefits immediately. However, rushing the process increases risk of errors, so balance speed with thorough due diligence.
Step 1: Get Pre-Approved by Early October
Start with mortgage pre-approval no later than the first week of October 2026. Pre-approval requires submitting pay stubs, tax returns, bank statements, and authorization for a credit check. According to the Consumer Financial Protection Bureau, pre-approval gives you a realistic budget and strengthens your offer (CFPB, 2026). Lenders typically issue pre-approval letters valid for 60 to 90 days, covering your search period through closing.
Shop rates with at least three lenders. Compare interest rates, APR, discount points, and lender fees. Lock your rate once you have an accepted offer to protect against rate increases during the closing process. Rate locks typically last 30 to 60 days, matching the standard closing timeline.
Step 2: Find a Home and Submit an Offer by Mid-November
With pre-approval in hand, begin your home search immediately. Work with a licensed real estate agent familiar with your target area and price range. The U.S. Department of Housing and Urban Development recommends interviewing multiple agents and checking references before committing (HUD, 2026).
To close by year end, you need an accepted purchase contract by mid-November at the latest. The contract triggers the closing timeline: inspections, appraisals, underwriting, and title work all begin once both parties sign. Missing this deadline leaves insufficient time for the standard 30 to 45-day closing process, even without complications.
When making an offer, consider requesting a shorter inspection period (7 days instead of 10) and waiving non-essential contingencies if you are comfortable with the risks and the market is competitive. Balance speed with protection. Never waive financing or title contingencies, as these protect you from uninsurable title defects and appraisal shortfalls.
Step 3: Complete Inspections and Appraisal Quickly
Schedule the home inspection within 48 hours of offer acceptance. Most inspectors can complete the report within 3 to 5 business days. Review findings immediately and decide whether to request repairs, credits, or walk away. Delays in inspection negotiations push back the entire timeline.
The lender orders the appraisal once the contract is signed. Appraisals typically take 7 to 14 days depending on appraiser availability and property complexity. If the appraisal comes in below the purchase price, you will need to renegotiate with the seller, increase your down payment to cover the gap, or cancel the contract under the appraisal contingency. Plan for this possibility by keeping extra cash reserves available.
Step 4: Navigate Underwriting Without Delays
After receiving the appraisal, the lender begins full underwriting. The underwriter verifies income, employment, assets, debts, and property value. This stage typically takes 10 to 20 days but can stretch longer if the underwriter requests additional documentation.
Respond to underwriter requests the same day you receive them. Common requests include updated pay stubs, bank statements, explanations for large deposits, and verification of down payment source. Any delay in providing documents extends the closing date. During underwriting, do not change jobs, open new credit accounts, make large purchases, or move money between accounts without notifying your loan officer. These actions can invalidate your approval and restart underwriting.
Step 5: Review Closing Disclosure and Schedule Closing
The lender must provide the Closing Disclosure at least three business days before closing. This document details your final loan terms, monthly payment, closing costs, and cash needed to close. Review it carefully against the initial Loan Estimate you received at application. Significant changes in fees or loan terms can trigger a new three-day waiting period, delaying closing.
Schedule your closing appointment as soon as the lender clears you to close, ideally in the final week of December but with a buffer before December 31. Closings scheduled on December 30 or 31 carry higher risk of last-minute delays that could push you into the new year. Aim for December 27 or 28 to allow room for unexpected issues.
Common Mistakes That Cause Delays
Opening new credit accounts during the purchase process triggers credit re-checks and can disqualify you from the loan. Changing jobs before closing requires re-verification of employment and income, delaying approval. Large unexplained deposits in bank accounts raise red flags with underwriters and require detailed documentation.
Read also: Closing Costs Explained and How to Reduce Them for US Buyers
Skipping the final walk-through inspection the day before closing can leave you unaware of property damage or incomplete repairs agreed to in the contract. Title issues discovered late in the process, such as unreleased liens or ownership disputes, can delay closing by weeks while the seller resolves them.
Frequently Asked Questions
Can I deduct mortgage interest if I close on December 31?
Yes. The IRS allows deductions for mortgage interest and points paid in the year of closing (IRS, 2026). Even if you close on the final day of 2026, you can claim prorated interest and any discount points on your 2026 tax return. Consult a tax professional for your specific situation.
What happens if closing gets delayed past December 31?
If closing pushes into 2027, you lose 2026 tax deductions for mortgage interest and property taxes. You can claim these deductions starting in 2027. The delay also means your rate lock may expire, potentially requiring a new lock at current market rates if rates have increased.
How much cash do I need at closing?
Cash needed includes your down payment, closing costs (typically 2 to 5 percent of the purchase price), and prepaid items such as property taxes, homeowners insurance, and mortgage interest. Your Closing Disclosure itemizes the exact amount. Bring a cashier’s check or arrange a wire transfer, as personal checks are not accepted for large amounts.
Should I rush to close before year end?
Only if the timeline allows proper due diligence. Rushing inspections, skipping title review, or accepting unfavorable contract terms to meet an arbitrary deadline creates long-term risks. If it is already late November and you have not started the process, consider waiting until January to avoid costly mistakes.
Conclusion
Closing on a home before the end of 2026 requires disciplined timeline management and quick responsiveness to lender and seller requests. Start pre-approval by early October, secure an accepted offer by mid-November, and build buffer time for unexpected delays. The tax benefits of year-end closing are real, but they do not justify skipping essential protections such as inspections and title review.
The fundamentals of responsible homeownership, as covered in foundational texts such as The Business of Being a Housewife, emphasize the importance of thorough preparation and informed decision-making in major financial commitments. Work with licensed professionals, confirm all timelines and costs with your lender in writing, and verify closing readiness at least one week before your target date.
This article provides educational information about the home closing process and is not personalized financial, lending, legal, or tax advice. Mortgage interest deduction rules, closing timelines, and loan qualification requirements vary by lender, loan program, and individual circumstances. Consult a licensed lender, HUD-approved housing counselor, and tax professional for advice specific to your situation. Interest rates, closing costs, and tax law are subject to change.
Sources
- Owning a Home (accessed )
- Buying a Home (accessed )
- Home Mortgage Interest Deduction (accessed )
- The Business of Being a Housewife: A Manual to Promote Household Efficiency (accessed )
Related articles
Closing Costs Explained and How to Reduce Them for US Buyers
Understand closing costs when buying a home in the US and discover actionable strategies to reduce these fees by thousands of dollars.
How Escrow Accounts Work on US Mortgages: Required vs Optional
Compare escrow-required vs escrow-waived mortgages. Learn how lender-managed accounts work, when you can opt out, and which option saves money.
Closing Costs Breakdown: What You Actually Pay at a US Home Closing
Learn what closing costs include when buying or refinancing a home in the US, with a breakdown of typical fees and a real-world example.
