US Mortgage Rates Hit Highest Levels in Over a Year
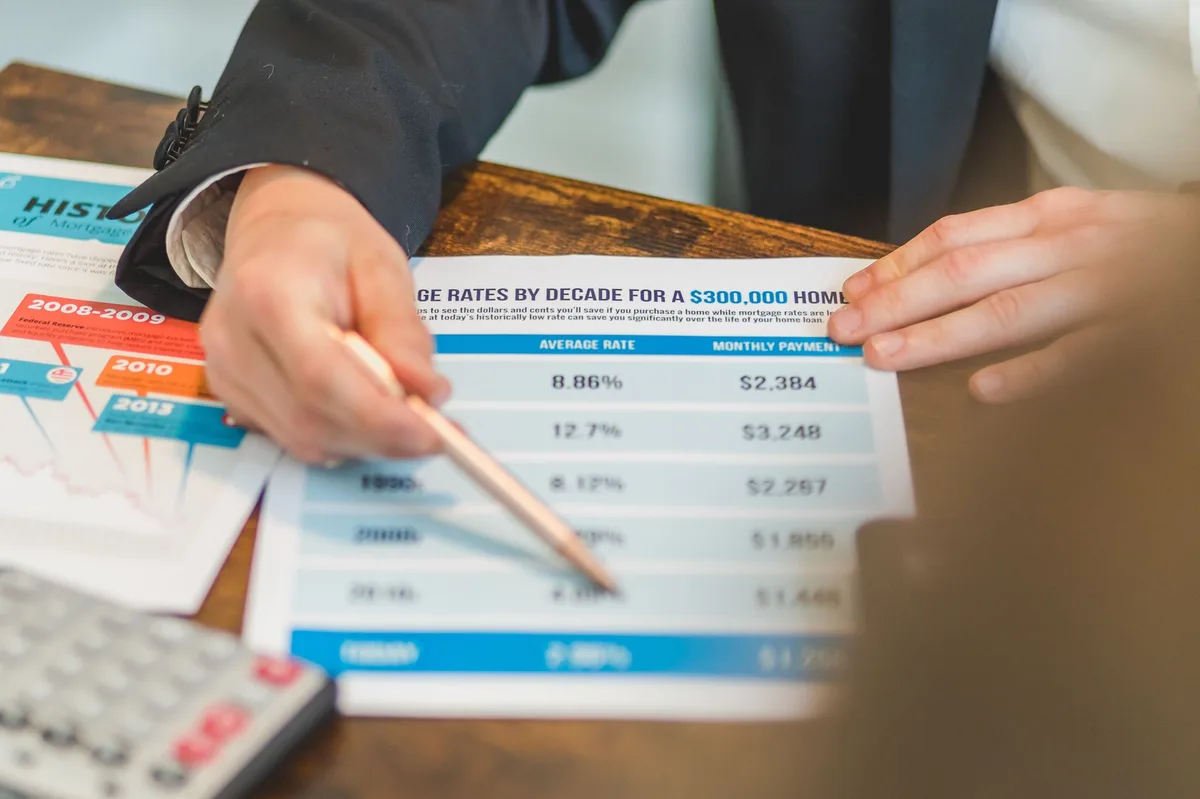
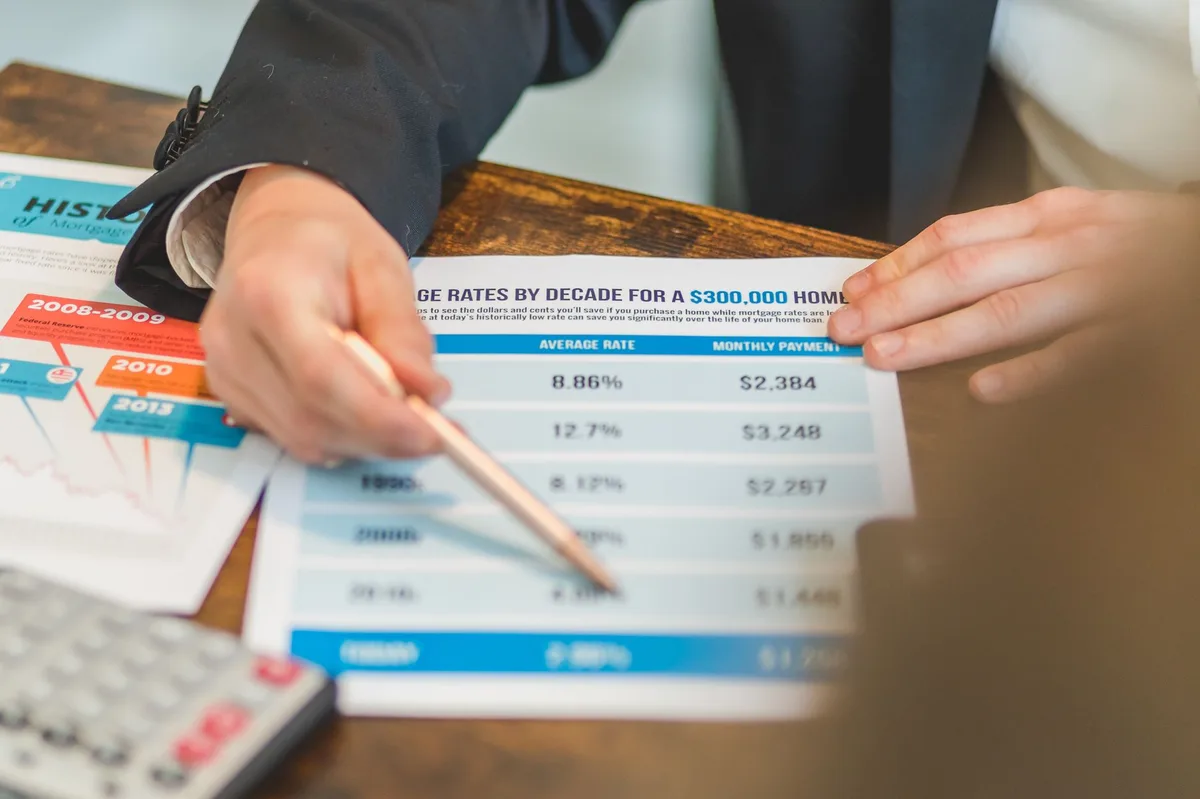
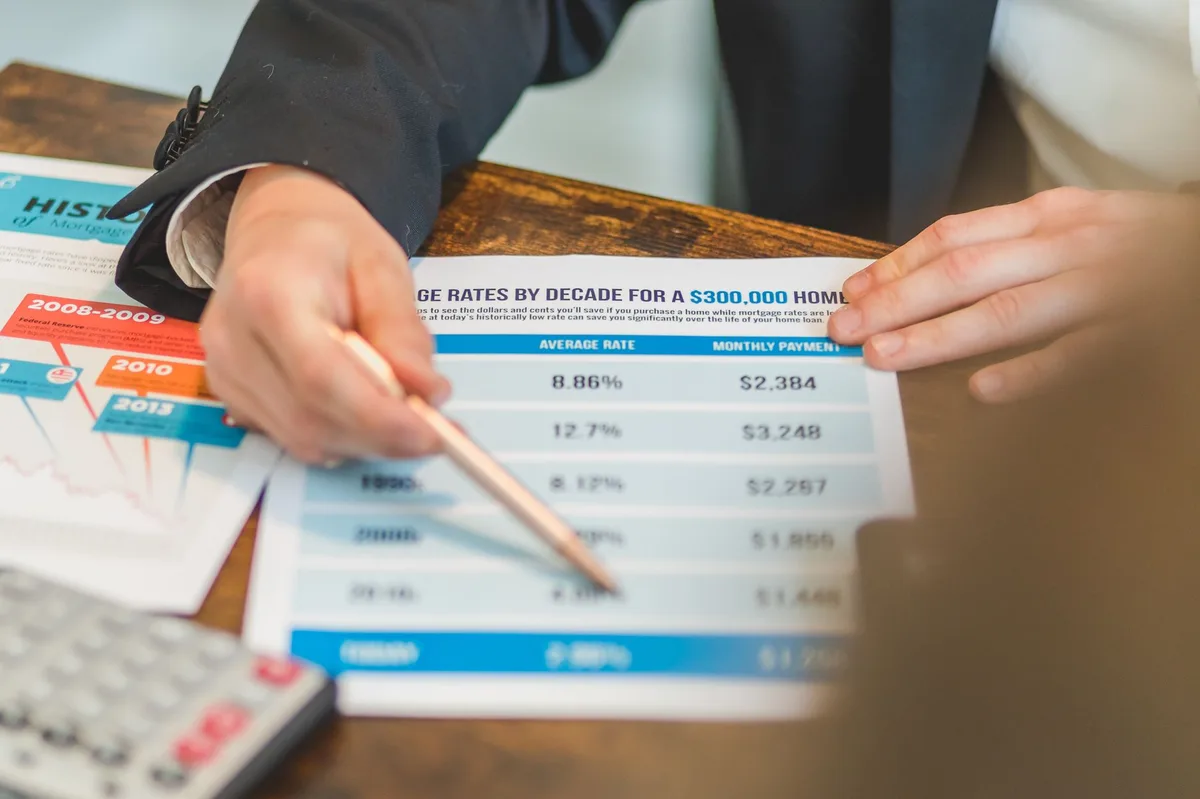
Average 30-year fixed mortgage rates have climbed above 7.2%, marking the highest point since summer 2025, driven by stronger-than-expected economic data and Federal Reserve policy signals.
Author
Writes about US refinance and home-equity products. Explains cash-out refinancing, HELOC draws, and debt-to-income thresholds for homeowners looking to lower their monthly payment or tap accumulated equity.

Average 30-year fixed mortgage rates have climbed above 7.2%, marking the highest point since summer 2025, driven by stronger-than-expected economic data and Federal Reserve policy signals.

Fixed-rate mortgages rose this week while adjustable-rate mortgages fell. Here's what today's rates mean for borrowers shopping for a home loan or considering a refinance.

Mortgage rates show mixed movement this morning as markets digest recent economic data and Federal Reserve signals.
Mortgage and refinance rates continue climbing today, reaching levels not seen since the early 2000s as the Federal Reserve maintains its restrictive monetary policy.

Compare cash-out refinancing and home equity loans to decide which financing option works best for your situation and financial goals.
Learn the proven strategies to boost your credit score before applying for a home loan and qualify for better mortgage rates and terms.

Compare five proven strategies to accelerate mortgage payoff and save thousands in interest without the cost and hassle of refinancing.

Learn the step-by-step process to evaluate whether refinancing your mortgage at current rates will save you money or cost more in the long run.

A construction loan for a newly built home pays the builder in stages as work progresses, not all at once. Understand how draws, inspections, and rate lock timing affect your costs and closing.

Learn how FHA-insured HECM reverse mortgages let homeowners 62 and older convert home equity into cash without monthly payments.

When an appraisal comes in low, buyers face several options that affect both their purchase contract and earnest money deposit. Understanding your choices helps you protect your investment.

Self-employed workers can qualify for a mortgage using bank statement loans or P&L documentation instead of traditional W-2 income verification.

Learn the simple formula to calculate how much equity you can tap from your home for a HELOC or cash-out refinance, and understand the loan-to-value limits that determine your borrowing power.

Deciding between buying mortgage points or keeping cash for closing costs depends on your break-even timeline, emergency reserves, and how long you plan to stay in the home.

Learn how rental yield measures your property's annual return and what percentage signals a strong investment in today's US real estate market.

Learn how debt-to-income ratios determine how much home you can afford and what monthly payment fits your budget.

Accelerate your path to dropping private mortgage insurance by making extra monthly payments and tracking your equity buildup to 20%.

Understanding conforming loan limits helps you know whether you qualify for standard mortgage terms or need a jumbo loan when buying a home.

Bi-weekly mortgage payments let you make one extra monthly payment per year, reducing your principal faster and building equity years ahead of schedule while saving thousands in interest.

Compare jumbo and conforming loans to understand which financing option fits your high-value home purchase and whether you meet the stricter qualification standards.

A HELOC lets you borrow against your home equity as needed. Learn how draw periods, repayment periods, variable rates, and qualification requirements work.

The Federal Reserve's July 2026 meeting could signal rate changes ahead. Here's what borrowers need to know about timing a refinance.

An escrow account is a separate account your lender manages to pay property taxes and homeowners insurance on your behalf, ensuring these critical costs are covered on time.

Understanding the difference between fixed-rate and adjustable-rate mortgages helps you choose the loan structure that matches your financial plans and risk tolerance.

On May 1, 2026, US mortgage rates climbed as renewed inflation fears gripped markets, pushing the 30-year fixed rate above 7% and making borrowing more expensive for homebuyers and those considering a refinance.

Conventional mortgage and refinance interest rates moved upward across the board on May 13, 2026, driven by persistent inflation concerns.

A Federal Reserve rate pause does not automatically lower mortgage rates in the US, but it can bring stability to home buyers.

Fixed mortgage rates were elevated around June 6, 2026, with 30-year rates near the mid-6% range. Borrowers should compare APR, points, and closing costs before locking a rate.

Mortgage and refinance rates were mixed over the July 4 holiday weekend, with purchase rates holding steadier than some refinance quotes. Borrowers should compare APR, points, and closing costs before locking.

Purchase and refinance mortgage rates stayed close on June 15, 2026, with the 30-year fixed average still below 7%. Borrowers should compare APR, fees, points, and closing costs before locking a rate.

Mortgage and refinance rates eased slightly on May 22, 2026, but borrowing costs remained high by recent standards. Here is what the move means for US buyers and homeowners.

A HELOC calculator estimates how much revolving credit you may be able to borrow against home equity. The key inputs are home value, current mortgage balance, lender loan-to-value limits, credit profile, and any existing liens.

Current mortgage and refinance rates declined across all major loan types on June 13, 2026, with the 30-year fixed rate dropping below recent averages.

The Fed held its policy rate steady in June, but that does not automatically create a refinance opportunity. The real test is your current mortgage rate, closing costs, credit profile, and break-even timeline.

Current mortgage and refinance interest rates as of June 24, 2026, plus factors that could drive rates up or down this week.

Offset mortgages link your savings to your mortgage to reduce interest, but they are not widely available in the US market. Learn about the concept and the US alternatives that achieve similar goals.

Learn how to build cash reserves that satisfy lender requirements and protect your homeownership dream from unexpected expenses.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.