How to Calculate if Refinancing Makes Sense in the US (August 2026)
Learn the step-by-step process to evaluate whether refinancing your mortgage at current rates will save you money or cost more in the long run.
Pexels - RDNE Stock project · original
In this article
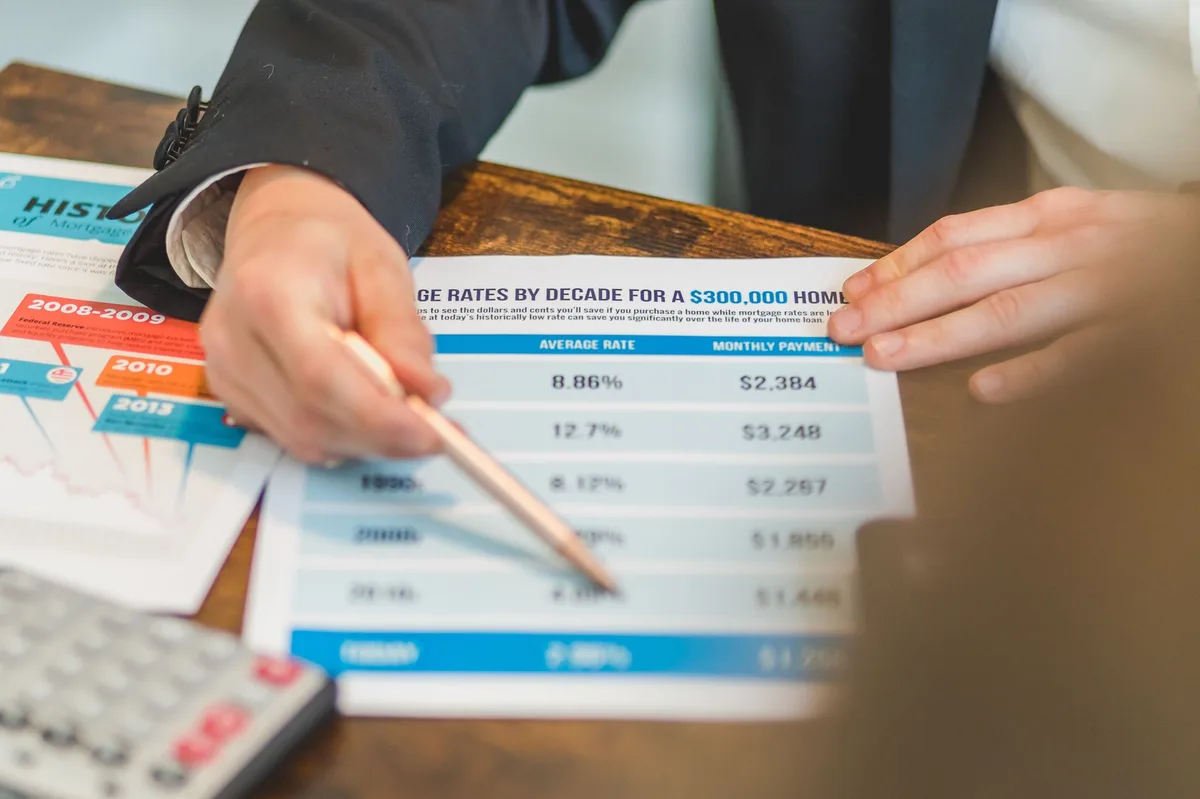
Refinancing makes sense when the interest rate savings outweigh the closing costs within your planned homeownership timeline. To calculate this, you need your current loan details, new rate quotes, estimated closing costs (typically 2% to 5% of the loan amount), and your break-even point (how many months to recoup costs through lower payments). If you plan to stay in your home longer than the break-even period and rates are meaningfully lower than your current rate, refinancing likely makes financial sense.
Mortgage rates fluctuate daily, and August 2026 presents a specific rate environment that may or may not favor your situation. The decision to refinance depends on comparing hard numbers, not assumptions. This guide walks you through the calculation process so you can make an informed choice based on your actual loan terms and timeline.
What You Will Learn
You will learn how to gather your current mortgage details, obtain accurate rate quotes, calculate your monthly savings, estimate total closing costs, determine your break-even point, and factor in your future plans to decide if refinancing makes financial sense right now.
Step 1: Gather Your Current Mortgage Information
Pull your most recent mortgage statement and note your current principal balance, interest rate, monthly payment (principal and interest only, excluding escrow), remaining loan term, and original loan amount. You need these exact figures to run an accurate comparison.
If you have PMI (private mortgage insurance) on a conventional loan, check if refinancing into a loan-to-value ratio below 80% would eliminate it. For FHA loans, note that MIP (mortgage insurance premium) may be permanent depending on your down payment and loan origination date, which affects the refinancing benefit calculation.
Step 2: Get New Rate Quotes for August 2026
Contact at least three licensed lenders to request rate quotes for the same loan type and term. Ask for the interest rate, APR, discount points (if any), and an itemized estimate of closing costs. According to the Consumer Financial Protection Bureau, lenders must provide a Loan Estimate within three business days of your application, which breaks down all costs.
As of August 2026, rates change daily and vary by lender, credit score, loan-to-value ratio, and loan type. A rate quote older than a few days may not reflect current market conditions, so request fresh quotes when you are ready to calculate. Verify whether the quote includes points (upfront fees to buy down the rate) and whether those points make sense for your timeline.
Step 3: Calculate Your Monthly Savings
Use the new interest rate and your current principal balance to calculate the new monthly payment. Subtract the new payment from your current payment to find your monthly savings. For example, if your current payment is $1,800 and the new payment would be $1,550, your monthly savings is $250.
Online mortgage calculators or amortization tables can help here, but the formula is straightforward: multiply the loan amount by the monthly interest rate (annual rate divided by 12), then apply the standard amortization formula. As discussed in foundational texts such as Principles of Finance, the time value of money principle applies, lower payments now free up cash flow for other financial goals or debt reduction.
If you currently pay PMI and the refinance eliminates it, add that monthly PMI cost to your savings figure. For a borrower paying $150 per month in PMI, eliminating it adds another $150 to the monthly benefit.
Step 4: Estimate Total Closing Costs
Closing costs for refinancing typically range from 2% to 5% of the new loan amount and include appraisal fees, title insurance, origination fees, recording fees, and other lender charges. Request a detailed Loan Estimate from each lender to see the breakdown.
For a $300,000 refinance, expect closing costs between $6,000 and $15,000. Some lenders offer no-closing-cost refinances, but these roll the fees into the loan balance or charge a higher interest rate, which extends your break-even timeline. Compare the true cost over the life of the loan, not just the upfront savings.
Step 5: Calculate Your Break-Even Point
Divide your total closing costs by your monthly savings to find the break-even point in months. Using the example above, if closing costs are $7,500 and monthly savings is $250, the break-even point is 30 months (2.5 years).
If you plan to stay in your home longer than the break-even period, refinancing likely makes sense. If you expect to move or pay off the loan before reaching break-even, the upfront costs outweigh the savings and refinancing does not benefit you financially.
Step 6: Factor in Your Timeline and Other Goals
Consider how long you plan to stay in the home, whether you want to shorten the loan term (switching from a 30-year to a 15-year mortgage builds equity faster but increases monthly payments), and whether a cash-out refinance fits your financial goals. Freddie Mac research shows that borrowers who refinance into shorter terms pay significantly less interest over the life of the loan, even if monthly payments rise.
Read also: When Does It Make Sense to Refinance Your Mortgage in the US
If your goal is to tap home equity for debt consolidation, home improvements, or other expenses, a cash-out refinance changes the calculation: you borrow more than you owe and receive the difference in cash, but this increases your loan balance and may push your loan-to-value ratio higher, affecting rates and PMI requirements.
Practical Tips
Lock your rate when you find favorable terms. Rate locks typically last 30 to 60 days and protect you from rate increases during the closing process. Check your credit score before applying; even a small improvement (from 720 to 760, for example) can lower your rate by 0.25% to 0.5%, which compounds over the loan term.
Shop lenders aggressively. Rate and fee differences between lenders can amount to thousands of dollars. Use the same loan details with each lender to ensure apples-to-apples comparisons.
Common Mistakes to Avoid
Do not focus only on the interest rate and ignore closing costs. A slightly lower rate with high fees may cost more than a marginally higher rate with lower fees. Do not assume that refinancing always makes sense just because rates dropped; run the break-even calculation based on your actual timeline.
Avoid rolling closing costs into the loan balance without recalculating the break-even point. This increases your principal and changes the math, potentially extending the payoff period beyond your plans.
Frequently Asked Questions
How much lower should the new rate be to make refinancing worth it?
A common rule of thumb is 0.5% to 1% lower than your current rate, but the real answer depends on your closing costs and timeline. Run the break-even calculation to know for sure.
Can I refinance if I have an FHA loan?
Yes. FHA streamline refinancing allows you to refinance an existing FHA loan with reduced documentation and no appraisal in many cases, lowering costs. VA borrowers have similar streamline (IRRRL) options.
What if rates drop further after I refinance?
You can refinance again if rates drop enough to justify new closing costs. There is no legal limit on how many times you can refinance, but each time resets your break-even clock.
Conclusion
Calculating whether refinancing makes sense in August 2026 requires gathering your current loan details, obtaining new rate quotes, estimating closing costs, and determining your break-even point based on how long you plan to stay in your home. If your monthly savings multiplied by the number of months you will stay exceeds your closing costs, refinancing is financially sound. Contact a licensed mortgage lender to request a Loan Estimate and verify current rates for your specific situation, as rates change daily and loan eligibility varies by program, lender, and location.
This article provides educational information and general guidance. It is not personalized financial, lending, or legal advice. Mortgage rates, loan terms, and eligibility requirements change frequently and vary by lender, credit profile, and location. Consult a licensed mortgage lender or HUD-approved housing counselor to evaluate your specific refinancing options and confirm current terms before making any financial decisions.
Sources
- Owning a Home (accessed )
- Research and Insights (accessed )
- Mortgages (accessed )
- Principles of Finance (accessed )
Related articles
When Does It Make Sense to Refinance Your Mortgage in the US
Understand the four main refinancing scenarios in the US, compare break-even timelines, and determine when refinancing your mortgage saves money.
5 Situations When Refinancing Your Mortgage Makes Sense in the US
Discover the 5 key situations when refinancing your mortgage makes financial sense in the US, from rate drops to debt consolidation.
How to Refinance Your Mortgage: A Step-by-Step Guide to Lower Your Rate or Tap Home Equity
Learn how to refinance your mortgage step-by-step, from checking rates to closing, with tips on timing, costs, and choosing the right loan type.
