Fall Mortgage Applications in the US: What Lenders Check That Summer Buyers Miss
Applying for a mortgage in fall brings different lender scrutiny than summer applications, from year-to-date income verification to post-summer employment stability.
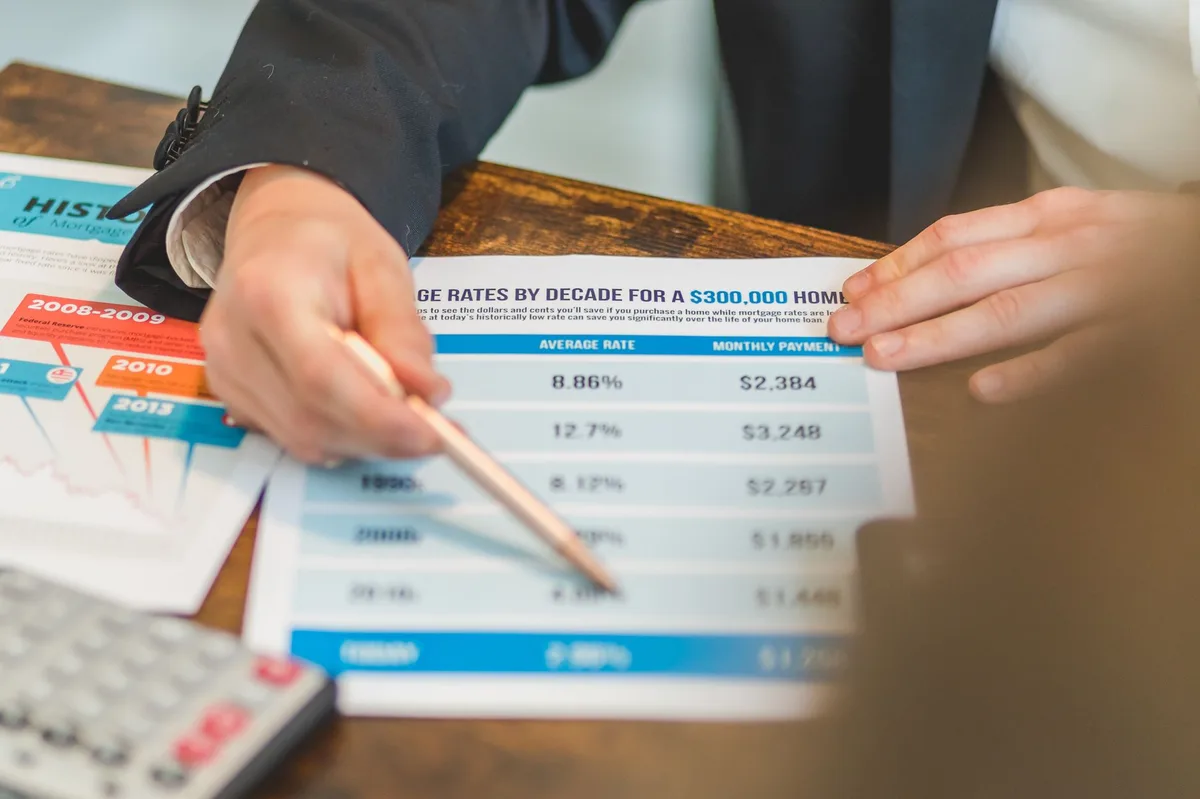
Pexels - RDNE Stock project · original
In this article
Key Takeaway: Fall mortgage applications undergo heightened lender scrutiny in six specific areas: year-to-date income verification becomes more precise, employment changes from summer are examined closely, seasonal work patterns face deeper review, summer spending appears on credit reports, end-of-year documentation requirements shift, and rate lock timing carries different risk. Knowing these focus points before you apply helps you gather the right documents and avoid delays.
Mortgage lenders adjust their verification processes throughout the year, and fall applications face different scrutiny than summer ones. If you are applying for a home loan between September and December, understanding what lenders check more carefully during this period can help you prepare documentation and avoid last-minute surprises that delay closing.
1. Year-to-Date Income Becomes Verifiable Reality
By fall, lenders have eight to ten months of your current-year income documented through paystubs, making it easier to verify whether you will meet annual income requirements. Summer buyers applying in May or June present only four or five months of income, which lenders must project forward. According to the Consumer Financial Protection Bureau, lenders verify income stability as a core underwriting requirement (CFPB, 2026).
What this means for you: If your income fluctuates (commissions, bonuses, overtime, or variable hours), fall lenders can see the actual pattern rather than relying on employer letters about expected income. Bring year-to-date paystubs and be prepared to explain any gaps or reductions from what your offer letter projected.
2. Post-Summer Employment Stability Gets Extra Attention
Many workers change jobs in summer, accepting new positions between May and August. By fall, lenders scrutinize whether those job changes have stuck or whether you are still in a probationary period. A job change in June that seemed stable in July might show red flags in October if your new role has performance conditions or if the probationary period is not yet complete.
What this means for you: If you changed employers after April, gather a written confirmation from your new employer stating your position is permanent, not probationary, and that your income is stable. Lenders typically want to see at least 30 days of paystubs from the new job, and they will verify employment directly.
3. Seasonal Work Patterns Require Deeper Documentation
Fall is when lenders can see whether seasonal workers (construction, landscaping, tourism, education support, retail) actually maintain year-round income or rely on a few high-earning months. Summer buyers in seasonal fields can point to current earnings; fall buyers must prove the income continues or that they have other income sources covering the lean months.
What this means for you: If you work seasonally, provide two years of tax returns showing consistent annual income, and if you supplement seasonal work with off-season employment, document both income streams clearly. Fannie Mae and Freddie Mac both require seasonal income to be verified over a multi-year period to establish reliability (Fannie Mae, 2026).
4. Summer Spending Shows Up on Credit Reports
Credit card balances from summer travel, home improvement projects, or back-to-school expenses typically post to credit reports by late August or September. Lenders pull your credit report shortly before closing, and any new debt that increases your debt-to-income ratio can jeopardize your approval or require you to pay down balances before closing.
Read also: How to Get Your First Mortgage in the United States: A Step-by-Step Guide
What this means for you: Check your credit report in early fall if you plan to apply for a mortgage. If summer spending pushed your balances higher, pay them down before the lender pulls credit. A debt-to-income ratio above 43 percent often disqualifies conventional loan applicants, and even FHA loans prefer ratios below 50 percent.
5. Tax Documentation Shifts Closer to Filing Deadlines
Lenders require the most recent two years of federal tax returns. For fall applicants, that means 2024 and 2025 returns (as of October 2026). If you filed an extension for 2025, you must either provide the completed return before closing or explain the extension and provide all supporting W-2s, 1099s, and other income documentation directly. Summer buyers applying before extension deadlines (October 15) face less scrutiny here.
What this means for you: If you filed an extension, gather your complete tax return and all schedules before you apply. Lenders will not close a loan without verifying the most recent tax year, and incomplete returns delay underwriting.
6. Rate Lock Expiration Risk Increases with Year-End Closings
Mortgage rate locks typically last 30 to 60 days. If you apply in October and lock a rate, but closing is delayed into December due to title issues, appraisal delays, or seller-side problems, your rate lock might expire. Extending a rate lock usually costs 0.125 to 0.25 percent of the loan amount per 15-day extension, and if rates have risen, you might face a higher rate at closing.
What this means for you: Build extra time into your closing timeline if you are applying in fall. Title companies and appraisers slow down around Thanksgiving and year-end holidays, and any delay can cost you money if your rate lock expires. Confirm your lender’s rate lock policy and extension costs before you commit.
Common Mistakes Fall Mortgage Applicants Make
The most frequent error is assuming summer income or employment patterns will satisfy fall lenders without additional documentation. Lenders verify current information, not past projections. Borrowers also underestimate how summer debt affects fall applications, waiting until after the credit pull to discover their debt-to-income ratio has climbed. Finally, many fall applicants do not account for year-end documentation requirements, particularly around tax returns and bonus income that has not yet been paid or verified.
Conclusion
Fall mortgage applications in the US require tighter income verification, clearer employment stability, multi-year proof of seasonal income, lower debt-to-income ratios reflecting summer spending, complete tax documentation, and careful rate lock management. As foundational texts such as Principles of Finance explain, lenders assess borrower risk through income stability and debt capacity, and fall applications provide more data points for that assessment than summer ones. Prepare these six areas before you apply, and you avoid the delays and denials that catch unprepared borrowers off guard.
This information is educational and general, not personalized financial or lending advice. Mortgage qualification requirements, acceptable debt-to-income ratios, employment verification standards, and documentation rules vary by loan program (conventional, FHA, VA, USDA), lender, and individual borrower situation. Rates and terms change daily. Consult a licensed mortgage loan officer for current requirements and eligibility specific to your financial profile and the loan type you are considering.
Sources
- Owning a Home (accessed )
- Fannie Mae Education and Resources (accessed )
- Freddie Mac Research and Insights (accessed )
- Principles of Finance (accessed )
Related articles
How to Get Your First Mortgage in the United States: A Step-by-Step Guide
Follow these five steps to get your first mortgage in the US: check credit, get pre-approved, choose a loan program, find a home, and close.
Pre-Approval vs Pre-Qualification: 7 Things Sellers Expect in the US
Learn the 7 key differences between mortgage pre-approval and pre-qualification that sellers care about when choosing buyers in the US market.
7 Strategies to Win a Home Offer in a Competitive US Fall Market
Discover 7 proven strategies to win a home offer in a competitive US fall market, from escalation clauses to strategic contingency waivers.
