Closing Before Year-End in Canada: Mortgage Interest Deduction Timing
Understanding the tax implications of mortgage closing dates in Canada and what year-end timing actually affects.
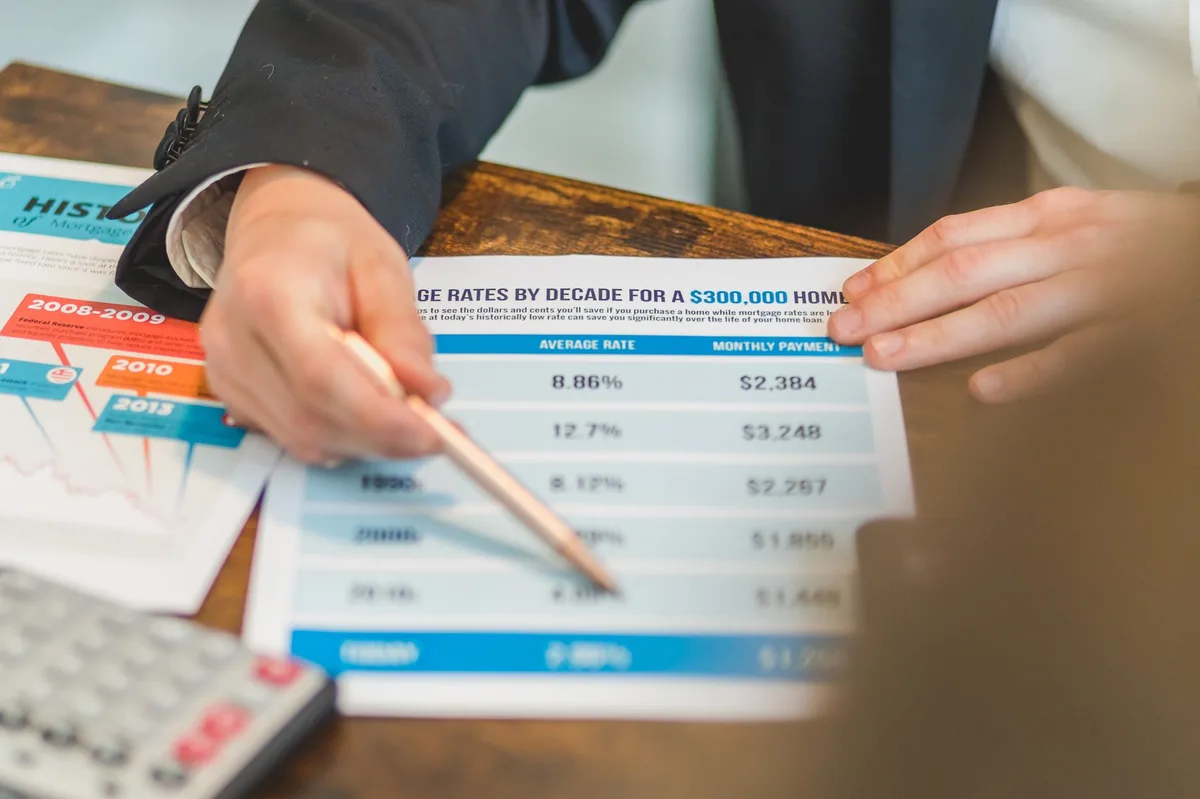
Pexels - Cytonn Photography · original
In this article
In Canada, mortgage interest on your principal residence is not tax-deductible, so rushing to close before December 31 will not give you a mortgage interest deduction. However, year-end timing can still affect land transfer tax claims, moving expense deductions, and your overall financial planning. If you are buying an investment property, the timing of your first interest payment may matter for tax purposes.
The Canadian Reality: No Principal Residence Deduction
Unlike the United States, Canada does not allow homeowners to deduct mortgage interest paid on their principal residence from their taxable income. According to the Financial Consumer Agency of Canada, mortgage interest payments are considered a personal expense and do not qualify for a federal tax deduction (FCAC, 2026).
This means that whether you close on December 15 or January 15, the mortgage interest you pay on your home will not reduce your tax bill. The timing of your closing date, by itself, provides no mortgage interest tax benefit for a principal residence.
What IS Tax-Deductible in Canada
While principal residence mortgage interest is not deductible, some mortgage-related interest can be claimed in specific situations:
Investment Properties: If you are purchasing a rental property or investment property, the mortgage interest is deductible as a rental expense against your rental income. In this case, closing before year-end means you can claim any December interest payments on your current tax return (Canada Revenue Agency).
The Smith Manoeuvre: This strategy involves refinancing your mortgage to borrow against your home equity and invest the proceeds in income-generating investments. The interest on the borrowed amount used for investment purposes may be tax-deductible, as covered in foundational finance texts such as Principles of Finance.
Business Use of Home: If you use a portion of your home exclusively for business purposes and have a mortgage, you may be able to deduct a proportionate share of the mortgage interest as a business expense.
Year-End Timing Considerations That Do Matter
Even without a mortgage interest deduction, several year-end factors may influence your closing timing:
Land Transfer Tax: In most provinces and some municipalities, you pay land transfer tax at closing. If you itemize moving expenses (when relocating for work), the land transfer tax may be deductible in the year you pay it. Closing before December 31 means you claim it on your current year tax return rather than waiting until next year.
Moving Expenses: If you are relocating at least 40 kilometres closer to a new work location, you may deduct eligible moving expenses, including some closing costs. The year you incur these expenses determines which tax year you claim them.
Read also: Land Transfer Tax in Canada: Provincial Differences for First-Time Buyers
First-Time Home Buyer Incentives: Programs like the Home Buyers’ Plan (which allows you to withdraw up to 35,000 dollars from your RRSP tax-free to buy a home) are not affected by closing date timing, but if you withdrew RRSP funds in the current year, closing before year-end completes that transaction within the same tax year.
Property Tax Adjustments: At closing, property taxes are typically adjusted between buyer and seller. The portion you pay at closing may be deductible if the property is used for rental or business purposes.
Financial Planning Beyond Taxes
Year-end closing timing can affect your finances in non-tax ways. December closings may face holiday scheduling delays with lawyers, lenders, and land registry offices. January closings give you a fresh start in the new year and may offer more flexibility with moving dates.
Your lender may also prefer certain timing for interest calculations. Canadian mortgages typically begin accruing interest on the closing date, and your first payment is usually due on the first day of the month following a full month after closing. A late December closing means your first payment may not be due until February, giving you extra time to settle in.
Practical Next Steps
Before deciding on a closing date based on year-end timing, confirm your specific situation with a licensed mortgage broker and a qualified tax professional. If you are buying an investment property, December closing may provide a small tax benefit from claiming December interest. For a principal residence, focus on closing when it works best for your moving schedule, financing conditions, and the transaction itself.
This information is general educational content only, not personalized financial, lending, legal, or tax advice. Mortgage rules, tax deductions, and land transfer tax rates vary by province, territory, and lender. Consult the Canada Revenue Agency, a licensed mortgage professional, and a tax advisor for your personal circumstances.
Disclaimer: The information provided in this article is for general educational purposes only and does not constitute financial, lending, legal, or tax advice. Mortgage products, tax rules, land transfer tax rates, and eligibility requirements vary by province, territory, lender, and individual circumstances. Interest deductibility rules are complex and depend on how borrowed funds are used. Consult a licensed mortgage broker, the Financial Consumer Agency of Canada, and a qualified tax professional for advice specific to your situation before making any mortgage or tax-related decisions.
Sources
- Mortgages - Financial Consumer Agency of Canada (accessed )
- Canada Revenue Agency (accessed )
- Mortgages - Ratehub (accessed )
- Principles of Finance (accessed )
Related articles
Land Transfer Tax in Canada: Provincial Differences for First-Time Buyers
Compare land transfer tax rates and first-time buyer rebates across Canada. Ontario and BC charge the most, while seven provinces have no transfer tax.
How to Calculate Ontario Land Transfer Tax in Canada
Calculate Ontario land transfer tax for your home purchase. Understand the progressive rate structure and first-time buyer rebate eligibility.
Ontario Land Transfer Tax in Canada: Calculate What You Owe and the First-Time Buyer Rebate
Estimate Ontario land transfer tax, Toronto MLTT, and the first-time buyer rebate before closing on a home in Canada.
