The Canada B-20 Mortgage Stress Test Explained for First-Time Buyers: 7 Key Facts
The OSFI B-20 mortgage stress test determines how much you can borrow in Canada. Learn how the qualifying rate works, what it means for your budget, and how to prepare.
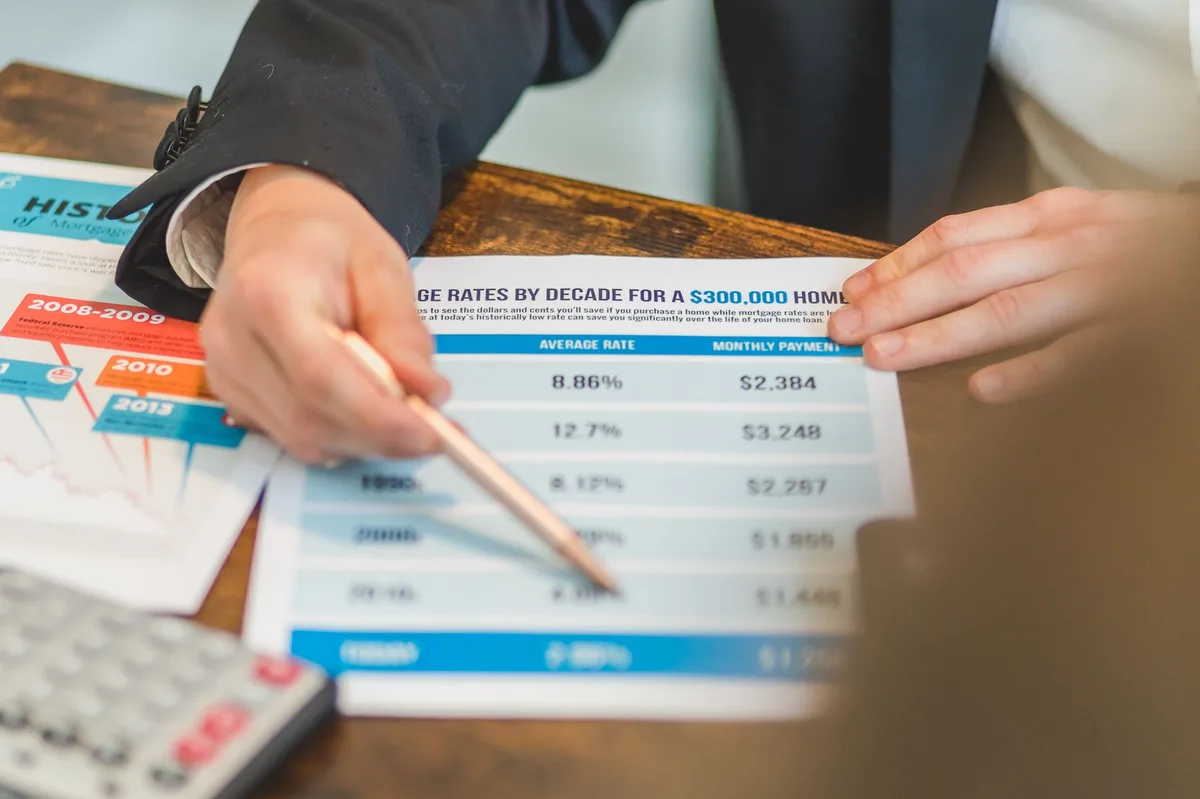
Pexels - RDNE Stock project · original
In this article
Key Takeaway
The OSFI B-20 mortgage stress test requires all federally regulated lenders in Canada to qualify you at a rate higher than your actual mortgage rate (either 5.25 per cent or your contract rate plus 2 percentage points, whichever is greater, as of August 2026). This means you can borrow less than your income alone might suggest, but it protects you from payment shock if rates rise when you renew. Understanding how the stress test works helps first-time buyers set a realistic budget and prepare for approval.
Understanding the B-20 Stress Test
If you are buying your first home in Canada, the B-20 mortgage stress test will directly affect how much you can borrow. Introduced by the Office of the Superintendent of Financial Institutions in 2018 and updated over time, this rule applies to all insured and uninsured mortgages from federally regulated lenders (banks, credit unions under federal jurisdiction, and trust companies).
Here are the seven most important facts first-time buyers need to know about the B-20 stress test and how it shapes your mortgage approval.
1. The Stress Test Uses a Higher Qualifying Rate Than Your Actual Rate
When you apply for a mortgage, the lender does not simply check whether you can afford the payments at the rate you will actually pay. Instead, according to the OSFI B-20 guideline (OSFI, 2026), you must qualify at the greater of two rates: the Bank of Canada conventional five-year fixed posted rate (5.25 per cent as of August 2026) or your contract rate plus two percentage points.
For example, if you negotiate a five-year fixed rate of 4.5 per cent, you will qualify at 6.5 per cent (4.5 per cent plus 2 per cent). If you negotiate a rate of 3.0 per cent, you still qualify at 5.25 per cent (the higher of the two thresholds). This qualifying rate determines your maximum borrowing power, not the rate you will actually pay each month.
2. The Stress Test Reduces Your Maximum Borrowing Amount
Because the lender calculates your debt service ratios at the higher qualifying rate, you can borrow less than you might expect based on your income alone. A household earning C$100,000 annually might qualify for approximately C$450,000 to C$500,000 under the stress test, whereas without the test the same household could potentially borrow C$550,000 or more, depending on other debts and the down payment.
According to the Financial Consumer Agency of Canada, the stress test ensures you can still afford your mortgage payments if interest rates rise during or after your initial term (FCAC, 2026). This safety margin protects you from over-borrowing in a low-rate environment and facing financial strain when you renew at a higher rate.
3. The Stress Test Applies to Renewals With a New Lender (Switches)
If you renew your mortgage with your current lender at the end of your term, you do not face the stress test again (your lender already holds your mortgage and typically offers a renewal without re-qualifying you). However, if you switch to a different lender for a better rate at renewal, the new lender must apply the stress test as if you were a new borrower.
This rule can trap some homeowners: if rates have risen significantly since your original purchase, or if your income has dropped, you might not qualify to switch lenders even though you have been making payments successfully for years. Many borrowers stay with their existing lender at renewal to avoid re-qualification, which can limit your negotiating power.
4. It Measures Affordability Using Debt Service Ratios
Lenders assess your ability to pass the stress test using two key ratios, as covered in foundational finance texts such as Principles of Finance from OpenStax:
- Gross Debt Service (GDS) ratio: your housing costs (mortgage principal and interest at the qualifying rate, property taxes, heating, and half of condo fees if applicable) must not exceed 39 per cent of your gross monthly income.
- Total Debt Service (TDS) ratio: your housing costs plus all other debt payments (car loans, credit cards, student loans, lines of credit) must not exceed 44 per cent of your gross monthly income.
If your ratios exceed these thresholds when calculated at the qualifying rate, the lender will reduce the mortgage amount until you fall within the limits or deny the application entirely.
Read also: The B-20 Mortgage Stress Test Explained for First-Time Buyers in Canada
5. A Larger Down Payment Improves Your Chances
One effective way to offset the impact of the stress test is to increase your down payment. A larger down payment reduces the mortgage principal you need to borrow, which lowers your monthly payment (calculated at the qualifying rate) and improves your debt service ratios.
For example, if you can put down 15 per cent instead of the minimum 5 per cent, you borrow less, pay less in CMHC mortgage default insurance premiums, and have an easier time meeting the stress test thresholds. Saving an extra C$20,000 to C$30,000 for your down payment can make the difference between qualifying for the home you want and settling for a less expensive property.
6. Reducing Other Debts Before You Apply Helps Significantly
Because the TDS ratio includes all your monthly debt obligations, paying down or eliminating other debts before you apply for a mortgage can free up room in your budget and improve your stress test results. Paying off a C$400 monthly car payment or a C$200 minimum credit card balance can increase your qualifying amount by tens of thousands of dollars.
Lenders look at the monthly payments listed on your credit report, so even a small loan with a low balance but a high monthly minimum can hurt your ratios. If possible, clear high-payment debts in the months leading up to your mortgage application.
7. The Stress Test Does Not Apply to Private or Non-Federally Regulated Lenders
The B-20 guideline applies only to federally regulated financial institutions. Some provincially regulated credit unions, mortgage finance companies, and private lenders are not required to apply the stress test (though many choose to follow similar prudent lending standards).
If you cannot pass the stress test with a major bank, you might qualify with an alternative lender. However, private and non-federally regulated lenders typically charge higher interest rates (often 1 to 3 percentage points above prime lender rates) and may require larger down payments or impose stricter prepayment penalties. This route can work as a short-term solution (for example, to get into the market and then refinance with a major lender after building equity), but it costs more over the life of the mortgage.
How to Prepare for the Stress Test
Start by calculating your debt service ratios at the current qualifying rate (check the Bank of Canada for the latest conventional five-year fixed posted rate, or add 2 percentage points to the rate your lender quotes you). Use an online mortgage affordability calculator to estimate your maximum borrowing power under the stress test, then set your home search budget accordingly.
Strengthen your application by improving your credit score (aim for 680 or higher, ideally above 700), saving a larger down payment, paying down existing debts, and ensuring your income documentation is complete and accurate (T4 slips, recent pay stubs, notice of assessment for self-employed buyers).
Final Thoughts
The B-20 mortgage stress test adds a layer of affordability protection for Canadian homebuyers, but it also means you will qualify for a smaller mortgage than your income alone might suggest. First-time buyers who understand how the qualifying rate works, plan for the reduced borrowing limit, and take steps to strengthen their financial profile (larger down payment, lower debts, strong credit) will navigate the stress test successfully and buy a home they can afford not just today, but through future rate cycles as well.
Disclaimer: This article provides general educational information about the OSFI B-20 mortgage stress test and mortgage qualification in Canada. It is not personalized financial, lending, legal, or tax advice, and it is not an offer or commitment to lend. Mortgage rules, qualifying rates, stress test thresholds, and lender policies vary by province, lender, and individual circumstances. Interest rates and the Bank of Canada conventional five-year fixed posted rate change frequently. Consult a licensed mortgage broker or your financial institution to confirm current rates, qualification requirements, and the stress test calculation for your personal situation before making any financial decisions.
Sources
- Residential Mortgage Underwriting Practices and Procedures - Guideline B-20 (accessed )
- Mortgages (accessed )
- Key Interest Rate (accessed )
- Principles of Finance (accessed )
Related articles
Understanding the B-20 Mortgage Stress Test in Canada: A Guide for First-Time Buyers
The B-20 mortgage stress test requires Canadian buyers to qualify at a higher rate. Learn how it works and how to prepare as a first-time buyer.
7 Essential Facts About Canada's B-20 Mortgage Stress Test for First-Time Buyers
Understand Canada's B-20 mortgage stress test: how it works, what rate you qualify at, and how it affects first-time home buyers in 2026.
The Canada B-20 Mortgage Stress Test Explained for First-Time Buyers
The OSFI B-20 mortgage stress test requires Canadian borrowers to qualify at a higher rate. Learn how it works and what first-time buyers need to know.
