Mortgage
The Canada B-20 Stress Test in 2026: Qualifying for a Mortgage at Current Rates
Learn how the OSFI B-20 mortgage stress test determines your qualifying rate and what you need to earn to pass in 2026.
Articles about credit under Mortgage.
Learn how the OSFI B-20 mortgage stress test determines your qualifying rate and what you need to earn to pass in 2026.
Fall mortgage applications face different lender scrutiny than spring applications, with increased focus on employment stability, recent debt changes, and seasonal property factors.
Learn how Canadian lenders use GDS and TDS ratios to determine your mortgage eligibility and how to improve your chances of approval.
The OSFI B-20 mortgage stress test determines whether you can still afford your mortgage if rates rise. Learn how the qualifying rate works, how it affects insured versus uninsured mortgages, and what it means for your first home purchase.
Compare documentation paths for self-employed Canadians seeking a mortgage, from traditional income verification to alternative documentation and stated-income programs.
B lenders offer mortgage financing to Canadian borrowers with damaged credit, charging higher interest rates and fees than prime lenders but providing a path to homeownership when major banks say no.
Self-employed Canadians face stricter income verification when applying for a mortgage, as lenders require detailed documentation to assess true earning capacity under OSFI rules.
The OSFI B-20 stress test determines how much you can borrow. Learn the qualification rules, how the test affects your budget, and what first-time buyers need to know before applying.
Learn how the OSFI B-20 mortgage stress test works in Canada and what first-time home buyers need to know to qualify for a mortgage in 2026.
Learn how the OSFI B-20 mortgage stress test works in Canada and what first-time home buyers need to know to qualify for a mortgage.
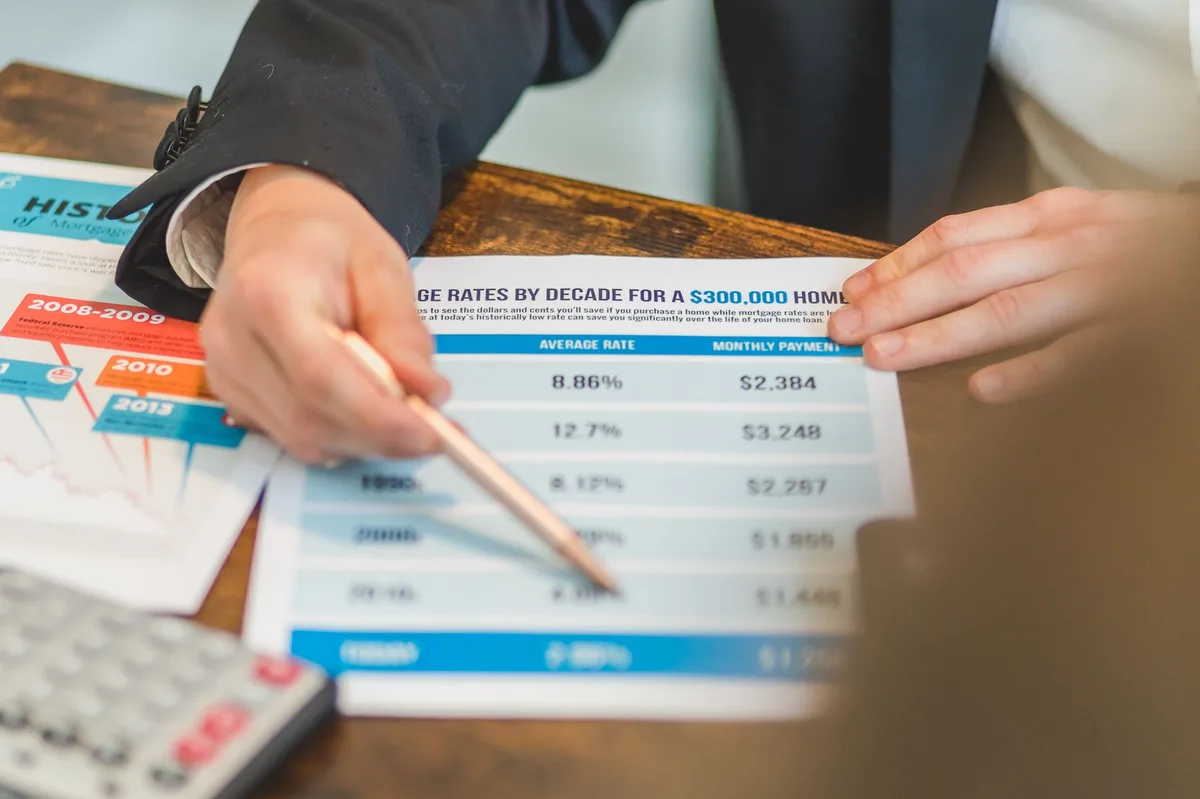
The OSFI B-20 mortgage stress test determines how much you can borrow in Canada. Learn how the qualifying rate works, what it means for your budget, and how to prepare.
Understanding the Gross Debt Service and Total Debt Service ratios that Canadian lenders use to determine how much mortgage you qualify for.
Learn how the OSFI B-20 mortgage stress test affects your home purchase approval and what qualifying rate you need to meet as a first-time buyer in Canada.
Understand how the OSFI mortgage stress test works and whether you qualify for a mortgage under Canada's B-20 guideline qualification rate.
Learn how Canada's mortgage stress test affects your borrowing power and what qualifying rate you need to pass.
The Bank of Canada has identified three key indicators that signal when homeowners may struggle to meet their mortgage obligations.
Learn how the OSFI mortgage stress test protects Canadian homeowners by ensuring they can handle payment increases during periods of rising interest rates.
Morningstar's support for OSFI's mortgage stress test and loan-to-income limits reinforces that Canadian mortgage qualification rules are likely to stay cautious.
Canada's mortgage stress test checks whether a borrower could still afford payments if rates rose. Here is how it works, why lenders use it, and what to review before applying.
The mortgage stress test checks whether you could still afford your mortgage at a higher qualifying rate. Here is how it works in Canada and why it affects your buying power.
OSFI's stress test exception for certain uninsured mortgage switches has reduced one barrier for some Canadian borrowers, but it does not remove the stress test altogether. Here is what changed, what did not, and why the market is still confused.
Canada's mortgage stress test is still part of mortgage qualification. The biggest practical changes are likely to affect renewals, lender switches and how borrowers compare affordability as rates move.
Canada's mortgage stress test remains a central part of mortgage approval. Here is why OSFI and lenders still see it as important.
Higher interest rates can significantly reduce how much you qualify to borrow for a mortgage, even when your income stays the same. Understanding the stress test and qualifying rate helps you plan your home purchase or renewal.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.
