The Canada B-20 Stress Test in 2026: Qualifying for a Mortgage at Current Rates
Learn how the OSFI B-20 mortgage stress test determines your qualifying rate and what you need to earn to pass in 2026.
Pexels - RDNE Stock project · original
In this article
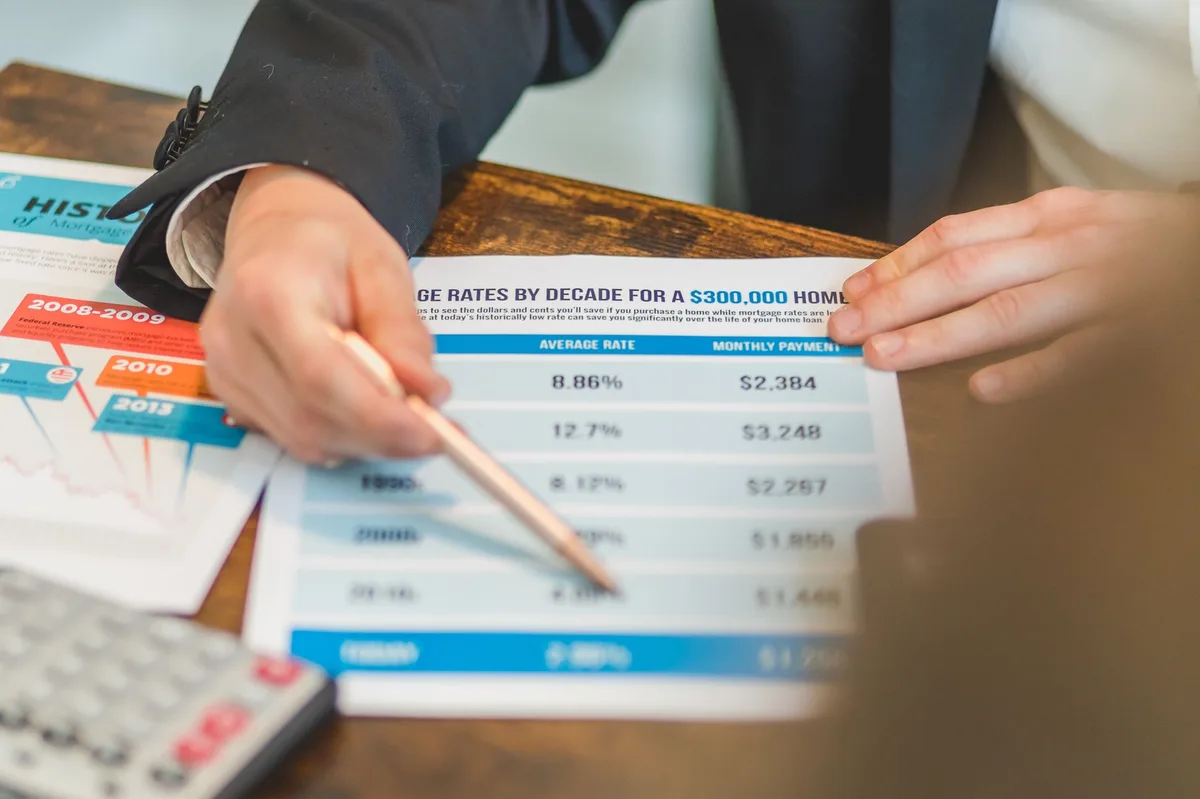
The OSFI B-20 mortgage stress test requires Canadian borrowers to prove they can afford mortgage payments at a rate higher than the one they will actually pay. As of October 2026, you must qualify at either your contract rate plus two percentage points, or the Bank of Canada qualifying rate (currently 5.25 per cent as set by OSFI), whichever is higher. This means that even if you secure a 3.5 per cent five-year fixed rate, the lender calculates your debt ratios using 5.5 per cent, reducing the maximum mortgage you can carry.
What the B-20 Stress Test Is
The B-20 guideline is a federal regulation issued by the Office of the Superintendent of Financial Institutions that applies to all federally regulated lenders (the big banks, credit unions under federal charter, and most mortgage finance companies). According to the OSFI B-20 guideline, lenders must test whether you can still afford your mortgage if rates rise or your financial circumstances change. The stress test has been in place since 2018 and applies to insured mortgages (those with less than 20 per cent down) and uninsured mortgages alike.
The qualifying rate calculation is straightforward: the lender takes the higher of your negotiated contract rate plus two percentage points, or the published qualifying rate set by the Bank of Canada and OSFI. The Financial Consumer Agency of Canada notes that this buffer protects borrowers from payment shock at renewal and ensures they have headroom if interest rates climb.
How the Qualifying Rate Affects Your Borrowing Power
When the lender runs your debt service ratios (gross debt service ratio and total debt service ratio), they plug in the higher stress-test rate instead of your actual rate. For example, if you earn C$90,000 per year and apply for a mortgage at 3.5 per cent, the lender will calculate your maximum loan amount as if the rate were 5.5 per cent. This reduces your purchasing power by roughly 15 to 20 per cent compared to qualifying at the contract rate alone.
The impact varies by province and by your other debts. Property taxes, heating costs, condo fees, car loans, and credit card minimums all count toward your total debt service ratio, which typically cannot exceed 42 to 44 per cent of your gross income. The stress test magnifies the effect of every dollar of existing debt, so paying down credit cards or car loans before you apply can materially increase the mortgage you qualify for.
What This Means for Borrowers in 2026
Current mortgage rates in October 2026 range from approximately 3.2 per cent for a five-year variable rate to 4.0 per cent for a five-year fixed rate at major lenders, though rates change frequently and vary by lender, term, and your credit profile. Under the stress test, a borrower negotiating a 3.5 per cent fixed rate must prove affordability at 5.5 per cent. If the contract rate were 4.0 per cent, the qualifying rate would be 6.0 per cent (the contract rate plus two percentage points is higher than the 5.25 per cent floor in this case).
Provincial rules and mortgage insurance requirements add further layers. In Ontario and British Columbia, land transfer taxes reduce the cash available for a down payment, tightening the loan-to-value ratio and potentially triggering CMHC mortgage default insurance if your down payment falls below 20 per cent. Quebec buyers face similar dynamics with the welcome tax. The stress test applies regardless of province, but the combined effect of local closing costs and the qualifying rate determines how much home you can afford in practice.
Read also: Canada B-20 Mortgage Stress Test: A Guide for First-Time Buyers in 2026
As covered in Principles of Finance, lender underwriting practices build in buffers to account for borrower risk and economic uncertainty. The B-20 stress test is one such mechanism, designed to prevent defaults during periods of rising rates or income disruption.
Tips for Passing the Stress Test
Increase your income or reduce your debts. Every thousand dollars of annual income adds roughly C$4,500 to C$5,000 of borrowing power under typical debt ratios. Paying off a C$400 monthly car payment frees up room for approximately C$80,000 more mortgage at a 5.5 per cent qualifying rate.
Save a larger down payment. A 20 per cent down payment eliminates the need for CMHC insurance premiums (which can add 2.8 to 4.0 per cent of the loan amount to your mortgage balance) and shows the lender you have financial discipline. The higher your down payment, the lower your loan amount and the easier it is to pass the stress test.
Shop for the lowest contract rate. While you must qualify at the stress-test rate, a lower contract rate means lower actual payments and may push you below the qualifying rate floor if the contract rate plus two percentage points is less than 5.25 per cent. Work with a licensed mortgage broker to compare offers from multiple lenders.
The B-20 stress test is general educational information only and not personalized financial or lending advice. Mortgage qualification rules, rates, and debt service ratio limits vary by lender, product, and your personal circumstances. Confirm your eligibility and the current qualifying rate with a licensed mortgage professional or your financial institution before making any decisions. As of October 2026, rates and the qualifying rate floor change frequently; verify current terms before applying.
Sources
- Residential Mortgage Underwriting Practices and Procedures - Guideline B-20 (accessed )
- Mortgages (accessed )
- Policy Interest Rate (accessed )
- Principles of Finance (accessed )
Related articles
Canada B-20 Mortgage Stress Test: A Guide for First-Time Buyers in 2026
Learn how Canada's B-20 mortgage stress test works for first-time buyers, comparing insured vs uninsured mortgages and qualifying rates in 2026.
7 Essential Facts About Canada's B-20 Mortgage Stress Test for First-Time Buyers
Understand Canada's B-20 mortgage stress test: how it works, what rate you qualify at, and how it affects first-time home buyers in 2026.
Understanding the B-20 Mortgage Stress Test in Canada: A Guide for First-Time Buyers
The B-20 mortgage stress test requires Canadian buyers to qualify at a higher rate. Learn how it works and how to prepare as a first-time buyer.
