Understanding Manulife Mortgage Rates in Canada
A comprehensive guide to Manulife's mortgage rate structure, products, and what Canadian borrowers need to know when comparing rates.
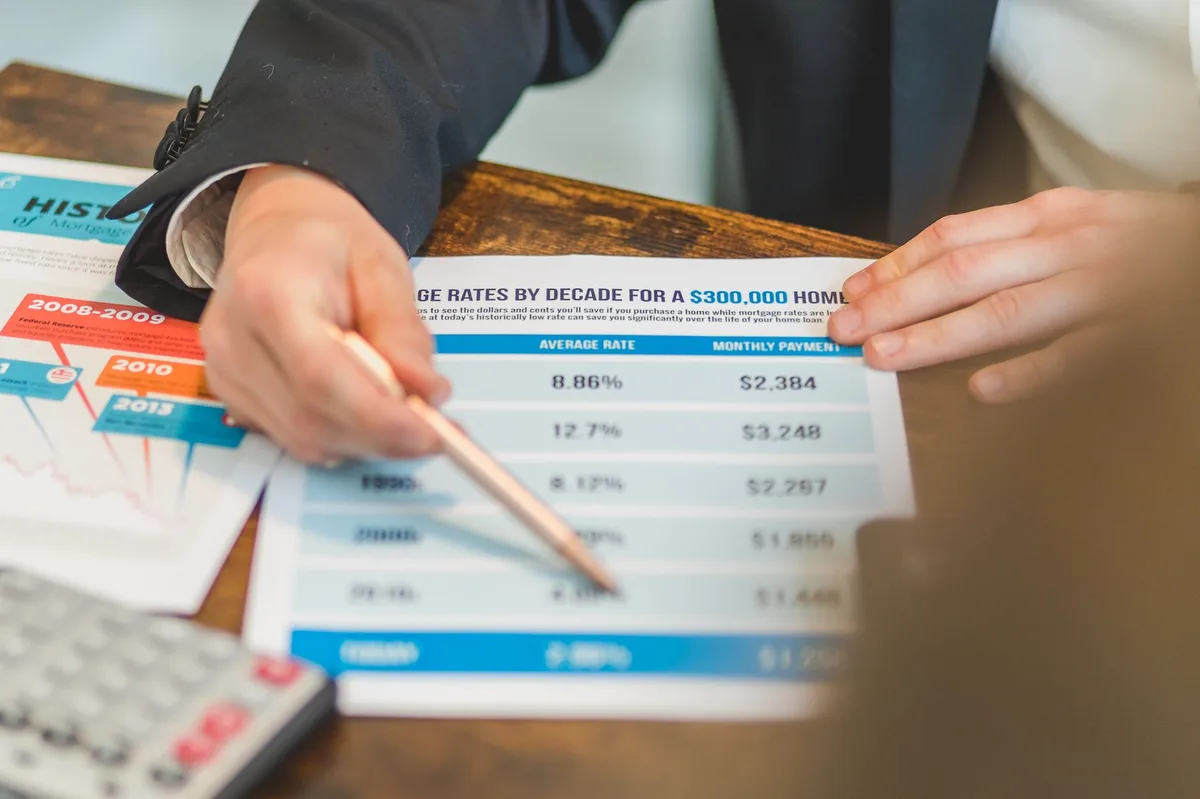
Pexels - RDNE Stock project · original
In this article
Key Takeaway
Manulife offers both fixed-rate and variable-rate mortgages to Canadian borrowers, with terms typically ranging from one to five years. Rates vary by mortgage type, term length, and whether the mortgage is open or closed, and all applicants must qualify under the OSFI mortgage stress test. Manulife’s rates change frequently in response to Bank of Canada policy and market conditions, so borrowers should verify current rates directly with the lender and compare them against other Canadian lenders before committing.
What Manulife Mortgage Rates Are
Manulife is a Canadian financial services company that offers mortgage products through Manulife Bank of Canada. Manulife mortgage rates are the interest rates the lender charges on its home financing products, expressed as an annual percentage. Like other Canadian lenders, Manulife offers both fixed-rate mortgages, where the rate stays constant for the duration of the term, and variable-rate mortgages, where the rate fluctuates with the lender’s prime rate, which in turn follows the Bank of Canada’s policy interest rate (Bank of Canada, 2026).
The rate you receive depends on several factors: the mortgage term (the period for which the rate is locked, typically one to five years), whether the mortgage is open (allowing prepayment without penalty) or closed (restricting prepayment), your credit profile, the property’s loan-to-value ratio, and current market conditions. As foundational texts such as Principles of Finance explain, lenders price mortgage rates to reflect their cost of funds, the borrower’s risk profile, and competitive market conditions.
Fixed-Rate Mortgages at Manulife
Fixed-rate mortgages from Manulife lock your interest rate for the duration of the term. The most common terms are one, two, three, four, and five years, with five-year fixed rates historically the most popular choice among Canadian borrowers. A fixed rate provides payment stability: your monthly principal and interest payment stays the same throughout the term, which simplifies budgeting and protects you if interest rates rise.
Fixed rates are generally higher than variable rates at the time of origination because you are paying for the certainty that your rate will not increase. At the end of the term, you renew the mortgage, either with Manulife or another lender, at the prevailing rate for a new term. According to the Financial Consumer Agency of Canada, understanding the distinction between the mortgage term and the amortization period (the full length of time to pay off the mortgage, often 25 or 30 years) is critical for Canadian borrowers (FCAC, 2026).
Variable-Rate Mortgages at Manulife
Manulife’s variable-rate mortgages have an interest rate that changes with the lender’s prime rate. When the Bank of Canada raises or lowers its policy interest rate, Canadian lenders typically adjust their prime rates in the same direction, which in turn affects your variable mortgage rate. A variable rate is often lower than a comparable fixed rate at the start, but it carries the risk that your rate and payment could increase if the Bank of Canada raises rates.
Some variable-rate mortgages offer a fixed payment with a fluctuating rate, meaning more or less of each payment goes to principal versus interest as the rate changes. Others adjust the payment amount when the rate changes. Borrowers who expect rates to fall, or who can tolerate payment variability, may prefer a variable-rate mortgage.
How to Access Manulife Mortgage Rates
You can obtain a Manulife mortgage by applying directly with Manulife Bank, or through a licensed mortgage broker who can compare Manulife’s rates and products against other lenders. Pre-approval is a common first step: Manulife reviews your income, credit history, and debt levels to estimate the maximum mortgage amount and the rate you qualify for. Pre-approval typically holds the rate for 90 to 120 days, though terms vary.
All mortgage applicants in Canada must qualify under the OSFI mortgage stress test, set out in Guideline B-20. The stress test requires you to qualify at the higher of the mortgage contract rate plus two percentage points or a minimum qualifying rate set by OSFI. This ensures you can still afford the mortgage if rates rise at renewal. Manulife, like all federally regulated lenders, applies this test to every mortgage application.
Rate Factors and Eligibility
Manulife sets its mortgage rates based on its own cost of funds, the competitive rate environment, and the risk profile of each borrower. Factors that influence the rate you are offered include your credit score (higher scores generally qualify for better rates), the size of your down payment (a down payment of 20 per cent or more avoids the need for mortgage default insurance and may qualify you for a lower rate), the property type and location, and whether you are a first-time buyer or repeat purchaser.
When your down payment is less than 20 per cent of the purchase price, you must obtain mortgage default insurance from CMHC, Sagen, or Canada Guaranty. The insurance premium is added to your mortgage balance. The insured mortgage may qualify for a lower interest rate because the insurer absorbs the lender’s default risk.
How Manulife Sets Its Rates
Manulife’s mortgage rates move in response to broader economic and monetary policy conditions. The Bank of Canada’s policy interest rate is a key driver: when the Bank raises its rate to combat inflation, variable mortgage rates rise, and the bond yields that influence fixed mortgage rates also tend to increase. When the Bank lowers rates to stimulate the economy, mortgage rates generally fall. Lenders also compete for market share, so Manulife’s rates reflect not only its internal cost structure but also the rates offered by the major banks and other mortgage providers (Ratehub, 2026).
Read also: Bank of Canada Rate Forecast for October 28: What to Expect in Canada
Rates change frequently, sometimes daily, so a rate quote from one day may not be available the next. This is why pre-approval rate holds and rate lock features are valuable during the homebuying process.
Comparing Manulife to Other Lenders
Manulife competes with the Big Five banks (RBC, TD, Scotiabank, BMO, and CIBC), other Schedule I banks, credit unions, and alternative lenders. Rate competitiveness varies by product and term: one lender may offer the lowest five-year fixed rate while another has a better three-year variable rate. Shopping around, either directly or through a mortgage broker, gives you leverage to negotiate and ensures you are getting a rate that reflects your credit strength and the current market.
Be aware that the lowest advertised rate often applies only to high-ratio insured mortgages with strong credit and may require other conditions such as setting up automatic payments or bundling other banking products. Always confirm the rate, term, prepayment privileges, and any restrictions before committing.
Practical Next Steps
If you are considering a Manulife mortgage, start by getting pre-approved to understand what rate and amount you qualify for. Compare Manulife’s offer against at least two other lenders or work with a licensed mortgage broker who can present multiple options. Verify the current rates directly with Manulife, as published rates are estimates and your actual rate depends on your application. Review the mortgage terms carefully, including prepayment privileges, penalties for breaking the mortgage early, and conversion options if you start with a variable rate and want to switch to fixed.
Frequently Asked Questions
What is the difference between Manulife’s fixed and variable rates?
A fixed rate stays the same for the term, providing payment stability. A variable rate changes with Manulife’s prime rate, which follows the Bank of Canada’s policy rate, and may be lower initially but can rise or fall.
Do I need mortgage default insurance for a Manulife mortgage?
Yes, if your down payment is less than 20 per cent of the purchase price. The insurance is provided by CMHC, Sagen, or Canada Guaranty and the premium is added to your mortgage balance.
How often do Manulife mortgage rates change?
Rates can change daily based on market conditions and the Bank of Canada’s policy decisions. Pre-approval typically holds a rate for 90 to 120 days.
Can I negotiate my Manulife mortgage rate?
Yes. Lenders often have flexibility, especially if you have strong credit, a large down payment, or competing offers from other lenders. A mortgage broker can help you negotiate.
What is the OSFI stress test and how does it affect my Manulife mortgage?
The stress test, set out in OSFI Guideline B-20, requires you to qualify at a rate higher than your contract rate. This ensures you can afford the mortgage if rates rise at renewal. All federally regulated lenders, including Manulife, apply this test.
Financial Disclaimer: This article provides general educational information only and is not personalized financial, lending, legal, or tax advice. It is not an offer or commitment to lend. Mortgage rates, products, eligibility, prepayment terms, and the OSFI stress test rules vary by lender, province, and your individual circumstances. Rates quoted are for illustrative purposes and change frequently. Consult a licensed mortgage broker or financial professional to confirm current rates and terms for your specific situation before making any mortgage decision.
Sources
- Mortgages (accessed )
- Mortgages and home equity lines of credit (accessed )
- Policy Interest Rate (accessed )
- Principles of Finance (accessed )
Related articles
Understanding CIBC Mortgage Rates in Canada
Explore CIBC mortgage rates in Canada. Learn about fixed and variable options, how rates are set, and what affects your personal rate offer at CIBC.
Bank of Canada Rate Forecast for October 28: What to Expect in Canada
Forecast for the Bank of Canada's October 28 rate decision and what it means for Canadian mortgage holders and variable-rate borrowers.
Bank of Canada Holds Key Interest Rate at 2.25%: What It Means for Loans in Canada
The Bank of Canada holds its policy rate at 2.25%. Learn how this decision affects mortgage rates, variable loans, and your borrowing costs in Canada.
