Understanding CIBC Mortgage Rates in Canada
Learn how CIBC structures its mortgage rates, what affects your rate offer, and how to compare fixed versus variable options at one of Canada's major banks.
Pexels - RDNE Stock project · original
In this article
Key Takeaway
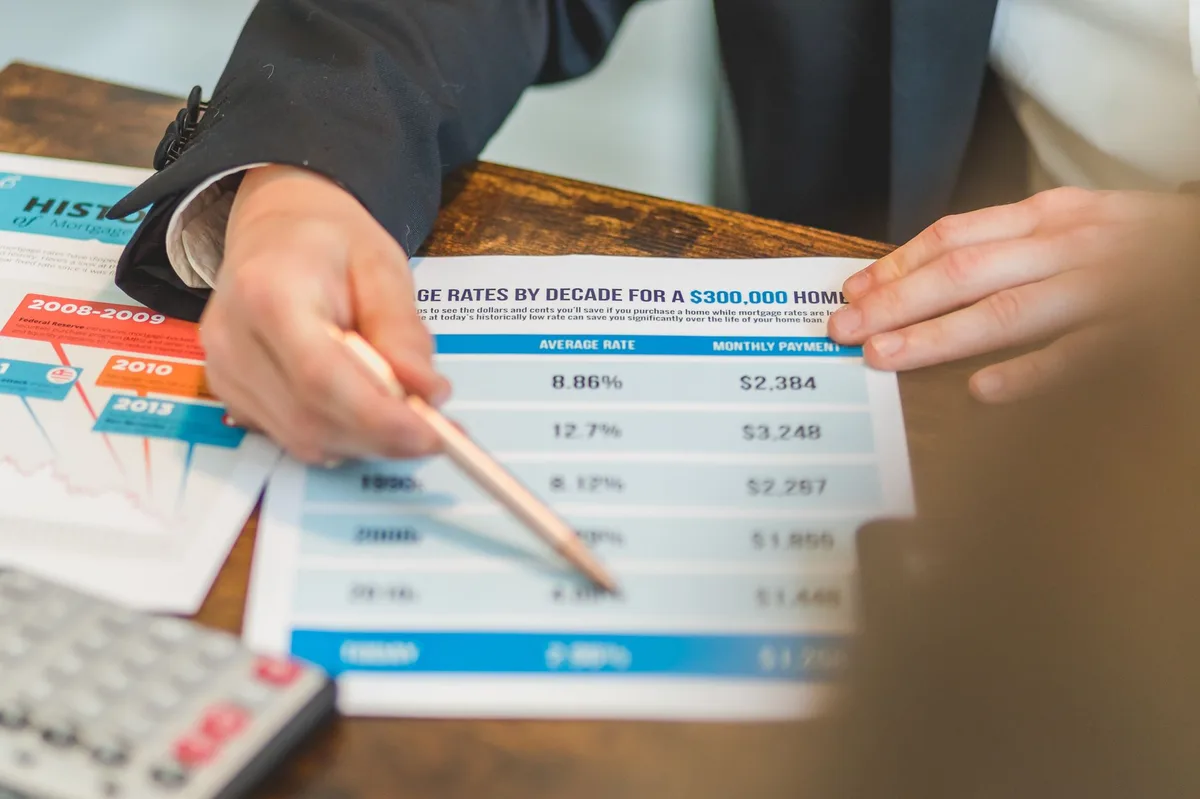
CIBC offers both fixed-rate and variable-rate mortgages across term lengths from one to ten years, with rates that change daily based on the Bank of Canada policy rate, bond yields, and competitive positioning. Your personal rate depends on your down payment, credit profile, the mortgage term and type you choose, and whether you qualify for a rate discount. Rates vary by province, and CIBC applies the OSFI stress test to every mortgage application to confirm you can handle rate increases.
What CIBC Mortgage Rates Are
CIBC mortgage rates are the interest rates Canadian Imperial Bank of Commerce charges borrowers on home loans. CIBC is one of Canada’s Big Five banks and offers residential mortgages for home purchases, renewals, refinancing, and accessing home equity. The rate you pay determines your monthly payment and the total interest cost over the life of your mortgage.
According to the Financial Consumer Agency of Canada, mortgage rates in Canada are influenced by the lender’s cost of funds, risk assessment, and competitive market conditions (FCAC, 2026). CIBC adjusts its posted rates daily, and the actual rate you receive depends on negotiation and your borrower profile.
CIBC mortgage rates apply to the mortgage term, the period during which your rate and conditions are locked in, typically ranging from one to five years. At the end of the term you renew, refinance, or pay off the mortgage. The amortization period, the total time to repay the loan fully, is separate and commonly extends to 25 or 30 years.
Fixed-Rate Mortgages at CIBC
A fixed-rate mortgage locks your interest rate for the full term. Your payment stays the same each month, and you are protected from rate increases. CIBC offers fixed-rate terms from one to ten years, with five-year fixed terms being the most popular choice among Canadian borrowers.
Fixed rates at CIBC are influenced by Government of Canada bond yields. When bond yields rise, fixed mortgage rates typically follow. CIBC posts its rates publicly, but the advertised rate is often a starting point. Many borrowers negotiate a lower rate, and CIBC may offer a rate discount if you have strong credit, a larger down payment, or bundle other banking products.
Fixed-rate mortgages work best when you want payment certainty and believe rates will rise during your term. The trade-off is that fixed rates are generally higher than variable rates at the start, and if market rates fall, you remain locked in unless you break your mortgage and pay the prepayment penalty, which for fixed-rate mortgages is usually the interest rate differential (IRD), a calculation that can be substantial.
Variable-Rate Mortgages at CIBC
A variable-rate mortgage has an interest rate that fluctuates with CIBC’s prime rate, which moves in response to changes in the Bank of Canada policy interest rate (Bank of Canada, 2026). When the Bank of Canada raises its rate, CIBC’s prime rate typically increases the same day, and your mortgage rate rises accordingly. When the Bank cuts rates, your rate falls.
CIBC offers variable-rate mortgages as either adjustable-rate (your payment changes when the rate changes) or fixed-payment variable (your payment stays the same, but the portion going to principal versus interest shifts). Variable rates are typically lower than fixed rates at origination, making them attractive when you expect rates to remain stable or decline.
The risk with a variable-rate mortgage is payment uncertainty. If rates climb significantly, your payment can increase, and under a fixed-payment variable structure, you may face an extended amortization or a payment adjustment at renewal. CIBC applies the mortgage stress test to variable-rate applications just as it does for fixed, using the higher of your contract rate plus 2 percentage points or the qualifying rate set by OSFI to ensure you can afford rate increases.
Foundational finance texts such as Principles of Finance explain that interest rate risk in variable-rate loans is borne by the borrower, while in fixed-rate loans the lender assumes that risk, which is why fixed rates carry a premium.
What Affects Your CIBC Mortgage Rate
Your personal rate at CIBC depends on several factors beyond the posted rate. Credit score plays a significant role: borrowers with scores above 700 generally qualify for better rates, while those with lower scores may face higher rates or require mortgage default insurance through CMHC if the down payment is under 20 per cent.
Down payment size matters. A down payment of 20 per cent or more eliminates the need for CMHC insurance and often unlocks lower rates. Insured mortgages (down payment under 20 per cent) sometimes receive better rates because the insurance reduces the lender’s risk, but you pay the insurance premium, which adds to your total cost.
Read also: Understanding Manulife Mortgage Rates in Canada
The term length you choose affects the rate. Shorter terms (one or two years) may carry lower rates but require you to renew more frequently and face interest rate risk sooner. Longer terms (five or ten years) offer stability but typically at higher rates.
Property type and location also influence your rate. Standard single-family homes in major urban centres generally receive the best rates. Investment properties, self-employed borrowers, and properties in remote areas may face rate premiums or stricter qualification criteria. Mortgage rules and land transfer tax vary by province, and CIBC applies provincial lending guidelines where applicable.
How to Compare and Negotiate CIBC Rates
CIBC publishes posted rates on its website and updates them daily, but these are rarely the final rates borrowers pay. Start by checking CIBC’s current posted rates for the term and type you want, then speak directly with a CIBC mortgage specialist or a licensed mortgage broker who works with CIBC.
Mortgage brokers often secure lower rates than what you can negotiate on your own because they have access to broker-only pricing and can compare offers from multiple lenders simultaneously. Even if you prefer to work directly with CIBC, getting a broker quote gives you leverage when negotiating.
When comparing rates, look beyond the number. Ask about prepayment privileges (how much extra you can pay each year without penalty), portability (whether you can transfer the mortgage to a new property), and the penalty calculation for breaking the mortgage early. CIBC’s prepayment penalty for fixed-rate mortgages uses the interest rate differential method, which can be expensive if rates have fallen since you locked in.
Review the total cost over the full term, not just the monthly payment. A slightly lower rate with restrictive terms may cost more than a marginally higher rate with flexible prepayment options if your financial situation changes.
Current Rate Environment and Timing
Mortgage rates in Canada change frequently in response to economic conditions, inflation, and Bank of Canada policy decisions. As of October 2026, rates have fluctuated throughout the year, and future movements depend on inflation trends, employment data, and global economic factors. CIBC adjusts its rates in real time, so the rate you see today may differ from the rate available tomorrow.
When shopping for a mortgage, CIBC and other lenders offer a rate hold, typically for 90 to 120 days, which locks in your rate while you finalize your purchase. If rates drop during the hold period, CIBC usually honours the lower rate, though this is not guaranteed and varies by product.
Timing your mortgage application to coincide with favourable rate movements is difficult. Rather than trying to time the market perfectly, focus on securing a rate and term structure that fits your financial situation, risk tolerance, and housing plans. If you expect to move or refinance within a few years, a shorter term may make sense even if the rate is slightly higher, because the penalty for breaking a shorter term is generally lower.
Conclusion
CIBC mortgage rates reflect broader market conditions, the Bank of Canada policy rate, and your individual borrower profile. Understanding the difference between fixed and variable rates, the factors that influence your personal rate offer, and how to negotiate effectively puts you in a stronger position when arranging financing. Rates and mortgage products vary by province, lender, and your circumstances, so confirm current terms and your specific eligibility with a CIBC mortgage specialist or a licensed mortgage broker before committing.
Financial Disclaimer: This article provides general educational information only and is not personalized financial, lending, legal, or tax advice. Mortgage rates, terms, eligibility, and prepayment penalties vary by lender, product, province, and your individual circumstances. Rates change daily. The OSFI mortgage stress test, CMHC insurance requirements, and land transfer tax differ depending on your location and down payment. Always verify current rates and product details directly with CIBC or a licensed mortgage professional, and consult a qualified financial advisor or mortgage broker for advice tailored to your personal situation before making any mortgage decisions.
Sources
- CIBC Mortgages (accessed )
- Mortgages and Home Buying (accessed )
- Bank of Canada (accessed )
- Principles of Finance (accessed )
Related articles
Understanding Manulife Mortgage Rates in Canada
Learn about Manulife mortgage rates in Canada, including fixed and variable options, terms available, and what borrowers need to qualify under current rules.
Bank of Canada Rate Forecast for October 28: What to Expect in Canada
Forecast for the Bank of Canada's October 28 rate decision and what it means for Canadian mortgage holders and variable-rate borrowers.
Bank of Canada Holds Key Interest Rate at 2.25%: What It Means for Loans in Canada
The Bank of Canada holds its policy rate at 2.25%. Learn how this decision affects mortgage rates, variable loans, and your borrowing costs in Canada.
