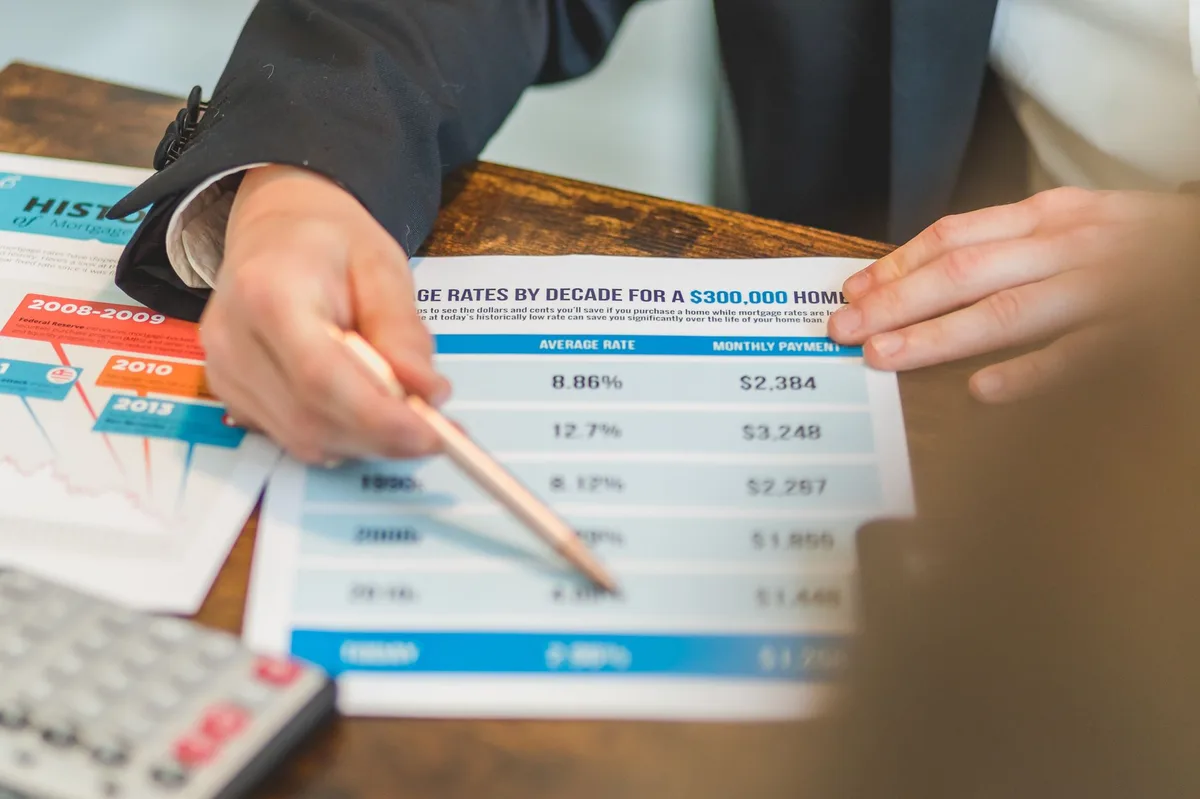
Mortgage
Understanding CIBC Mortgage Rates in Canada
Learn how CIBC structures its mortgage rates, what affects your rate offer, and how to compare fixed versus variable options at one of Canada's major banks.
Author
Writes about Canadian refinancing and home-equity products. Explains the HELOC-versus-second-mortgage decision, prepayment privilege rules by lender, and how to use equity responsibly.
Learn how CIBC structures its mortgage rates, what affects your rate offer, and how to compare fixed versus variable options at one of Canada's major banks.
When major Canadian banks disagree on future interest rates, your mortgage renewal strategy needs to account for uncertainty - here is what the split forecasts mean and how to prepare.
The International Monetary Fund has flagged bond-market volatility as a global threat, while major Canadian lenders like BMO respond by raising fixed mortgage rates.
The OSFI mortgage stress test remains a cornerstone of Canadian lending, but rising rates and changing market conditions have renewed debate about its role and effectiveness.
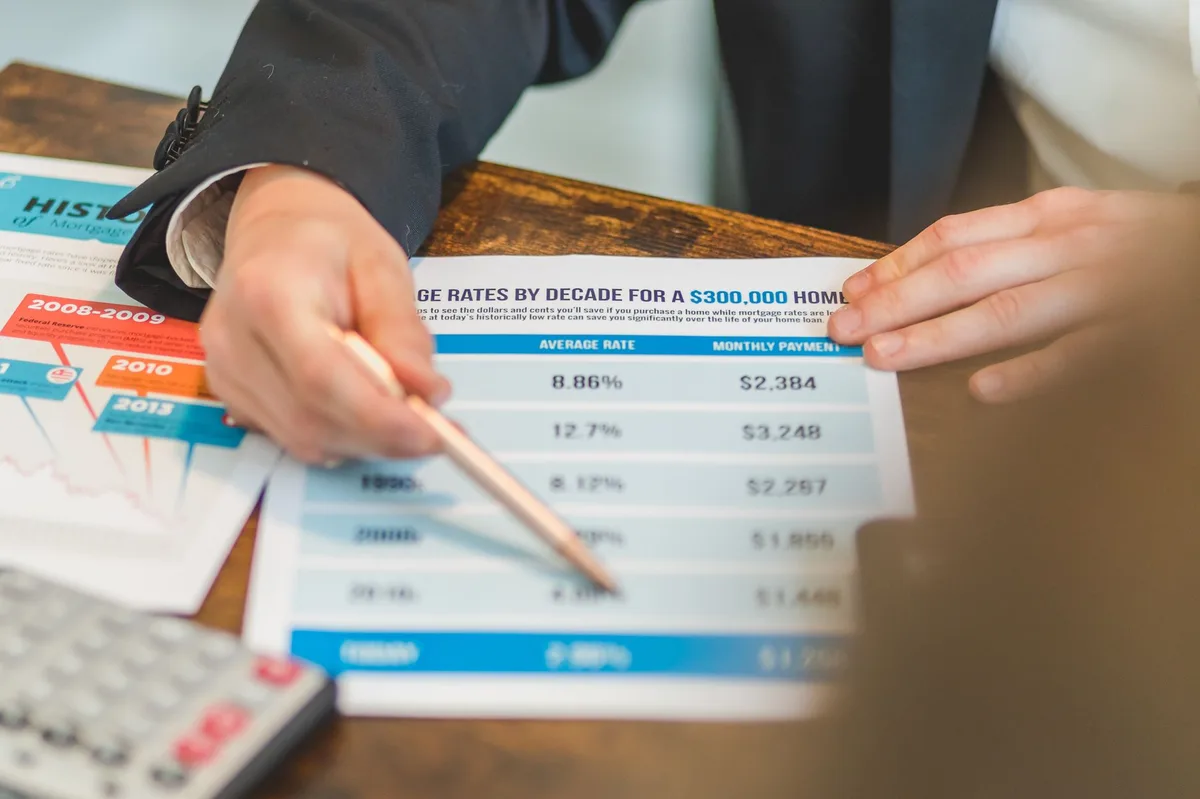
A largely unknown OSFI exemption allows borrowers with insured mortgages to switch lenders at renewal without passing the mortgage stress test, potentially saving thousands in interest.
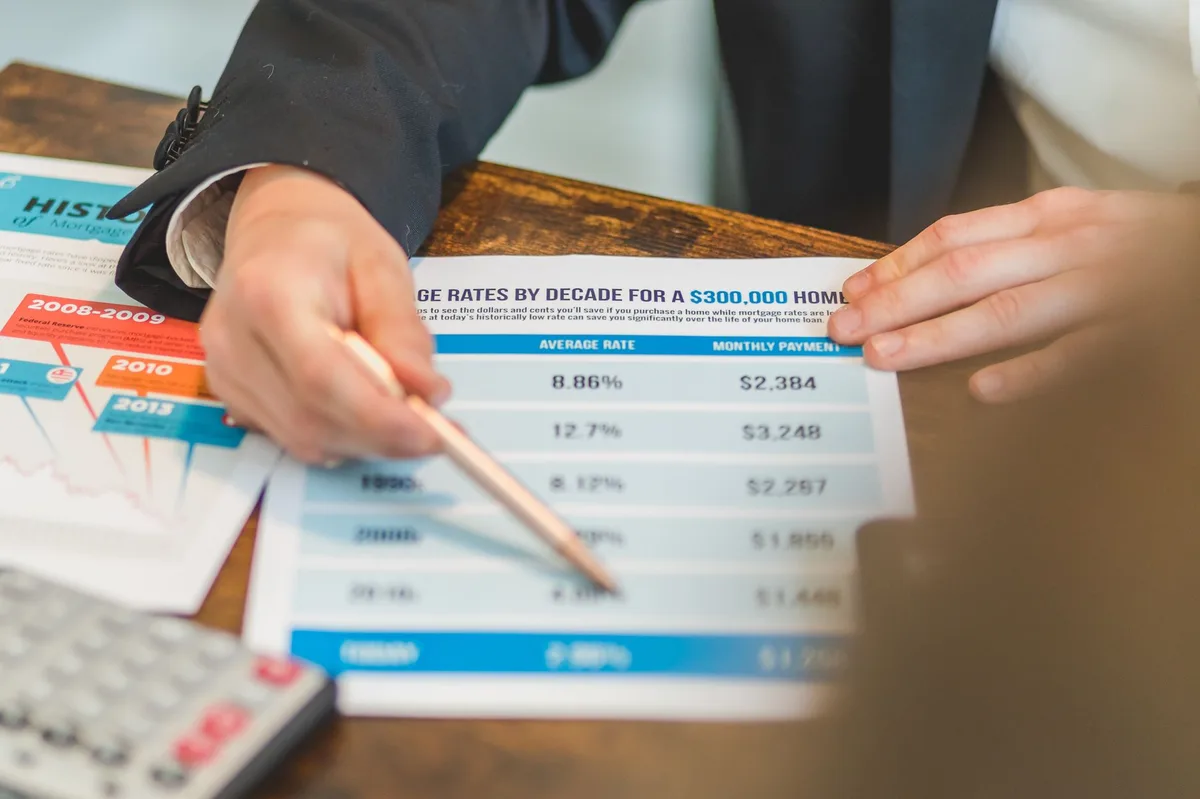
Understanding OSFI's mortgage stress test requirement and how it affects your borrowing power in Canada.
Recent changes to OSFI's mortgage stress test have created uncertainty among lenders, brokers, and borrowers across Canada's mortgage industry.
Learn how the OSFI mortgage stress test affects your home buying power in Canada, including the qualifying rate, calculation examples, and strategies to pass.
Canadian homeowners can now switch mortgage providers without passing the stress test, making it easier to access better rates and terms at renewal.
OSFI announced homeowners can now switch lenders at renewal without facing the mortgage stress test, opening up competition and potentially better rates for Canadian borrowers.
When bond yields rise, fixed-rate mortgages typically become more expensive while variable rates may lag. Understanding the relationship between bond markets and mortgage pricing helps you choose the right mortgage type for your financial situation.
The Bank of Canada's decision to hold its policy rate at 2.25% affects mortgage rates, variable-rate loans, and borrowing costs across Canada. Here's what borrowers need to know.
Bank of Canada research identifies three key indicators that predict mortgage default risk: payment strain, credit deterioration, and liquidity problems.
Understanding what the Bank of Canada's decision to hold interest rates means for mortgage holders and home buyers amid growing housing market challenges.
The Bank of Canada held its target overnight rate at 2.25% for the fifth consecutive time in June 2026, continuing a pause after earlier rate cuts.
When the Bank of Canada holds its policy rate steady, mortgage holders face different impacts depending on their mortgage type and renewal timeline.
The Bank of Canada policy interest rate directly affects variable-rate mortgages and indirectly influences fixed-rate mortgage pricing, making it one of the most important factors in your borrowing costs.
Co-signing a mortgage lets parents use their income and credit to help an adult child qualify, but it carries serious financial and legal obligations for both parties.
Fall mortgage applications face different lender scrutiny than spring applications, with increased focus on employment stability, recent debt changes, and seasonal property factors.
Compare the FHSA and RRSP HBP to find the best tax-advantaged savings strategy for your first home purchase in Canada.
Compare the RRSP Home Buyers Plan and the First Home Savings Account to decide which down payment strategy works best for your first home purchase in Canada.
The Bank of Canada's September 2026 rate decision creates a key choice point for autumn home buyers weighing fixed-rate stability against variable-rate flexibility.
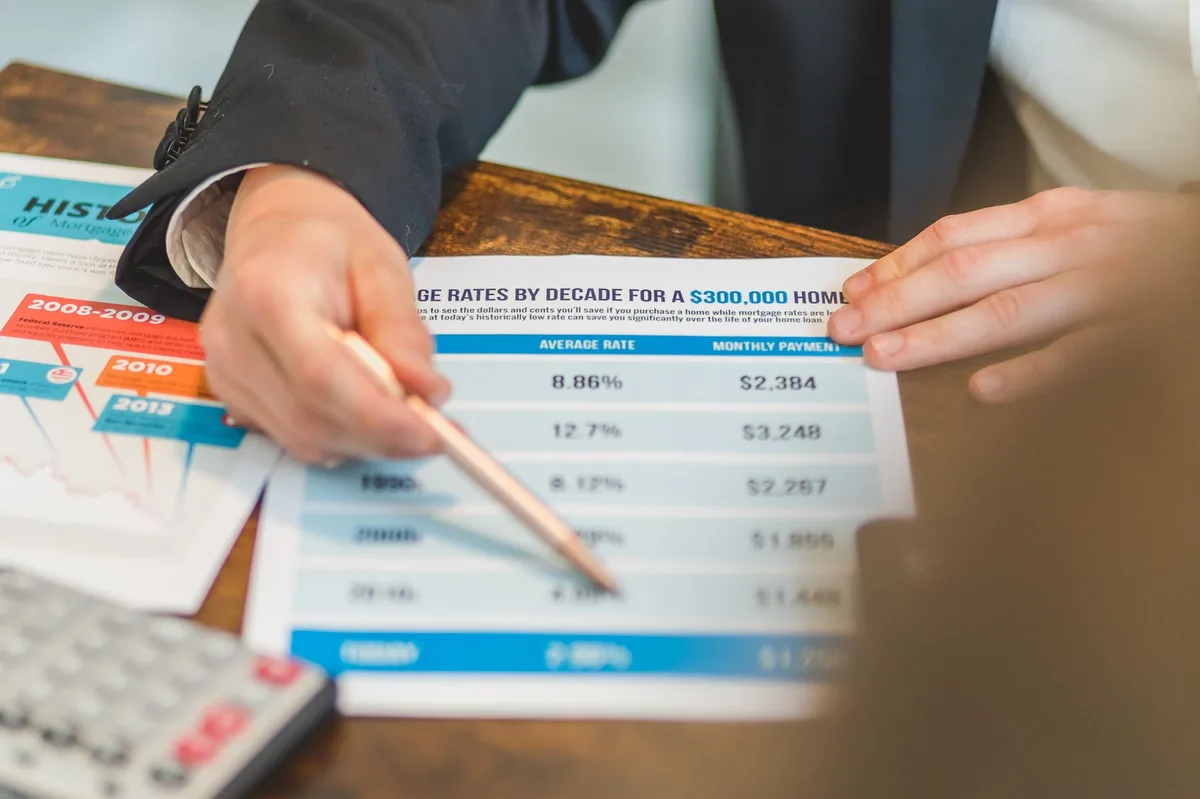
Learn how to negotiate the best mortgage renewal rate during the 2026-2027 renewal surge with proven strategies to save thousands over your term.
Mortgage portability lets you transfer your existing mortgage and rate to a new property, avoiding prepayment penalties and protecting a favourable rate when you move.
Learn how construction mortgage draws are released in stages as your new home is built, and what happens at completion when you convert to a standard mortgage.
Understand the key differences between financing a second home and an investment rental property in Canada, including mortgage requirements, tax implications, and which option suits your goals.
Learn how assumable mortgages work in Canada, the qualification process, and whether taking over an existing mortgage rate can save you money.
Learn how the OSFI B-20 mortgage stress test works in Canada and what first-time home buyers need to know to qualify for a mortgage.
Compare fixed-rate and variable-rate mortgages in Canada to decide which option suits your financial goals, risk tolerance, and interest rate outlook.
Compare 5-year fixed and variable mortgage rates in Canada with an interactive calculator to see which option aligns with your risk tolerance and financial goals.
Learn how to calculate gross and net rental yield to measure the return on your Canadian investment property and compare opportunities.
Learn how to evaluate two Canadian mortgage offers side by side to find the lowest total cost over your mortgage term.
Understand how the OSFI mortgage stress test works and whether you qualify for a mortgage under Canada's B-20 guideline qualification rate.
Compare mortgage life insurance and term life insurance to choose the right coverage for your home financing and family protection needs in Canada.
Discover how to use prepayment privileges to reduce your mortgage term, save thousands in interest, and own your home sooner.
The Bank of Canada has identified three key indicators that signal when homeowners may struggle to meet their mortgage obligations.
A Bank of Canada rate hold keeps the policy interest rate unchanged, stabilizing borrowing costs but offering no relief for those waiting for rate cuts to boost affordability or refinancing opportunities.
Learn how the OSFI mortgage stress test protects Canadian homeowners by ensuring they can handle payment increases during periods of rising interest rates.
BMO has brought back stress-test qualification for some uninsured mortgage switches. Here is what Canadian borrowers should know before moving a mortgage at renewal.
Canada's stress test rules changed for some uninsured mortgage switches. Here is what the OSFI update means at renewal and what still does not qualify.
Some Canadian homeowners can now switch mortgage providers at renewal without passing the federal mortgage stress test. The exemption is narrow, and it usually applies only to a straight switch with no larger loan or longer amortization.
Many Canadian homeowners can now shop for a new lender at renewal without requalifying under the mortgage stress test. The exception is narrow, so refinancing, borrowing more, or changing the loan structure may still trigger full underwriting.
OSFI no longer expects federally regulated lenders to apply the uninsured mortgage stress test to straight renewal switches. The change can make it easier for some Canadian homeowners to compare lenders at renewal.
The Bank of Canada's June 2026 policy rate decision and what it means for your mortgage payments, renewals, and home financing plans this summer.
Canadian mortgage rates show mixed movement in mid-June 2026, with fixed rates holding steady while variable rates edge up slightly.
Canadian mortgage rates rose this week across fixed and variable products. See today's rates and what the increase means for buyers and those looking to refinance.
Compare fixed-rate and variable-rate mortgages in Canada to understand how each works, their advantages and risks, and which option fits your financial goals and risk tolerance.
Fixed mortgage rates declined slightly while variable rates continue to fluctuate as the Bank of Canada maintains its current monetary policy stance.
Learn how to maximize deductions and meet CRA requirements with strategic tax planning before December 31 and the filing deadline.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.