BMO Brings Back the OSFI Stress Test for Uninsured Mortgage Switches in Canada
Bank of Montreal now requires borrowers switching their uninsured mortgage to qualify at the higher stress-test rate, reversing an industry practice that had made switches easier.
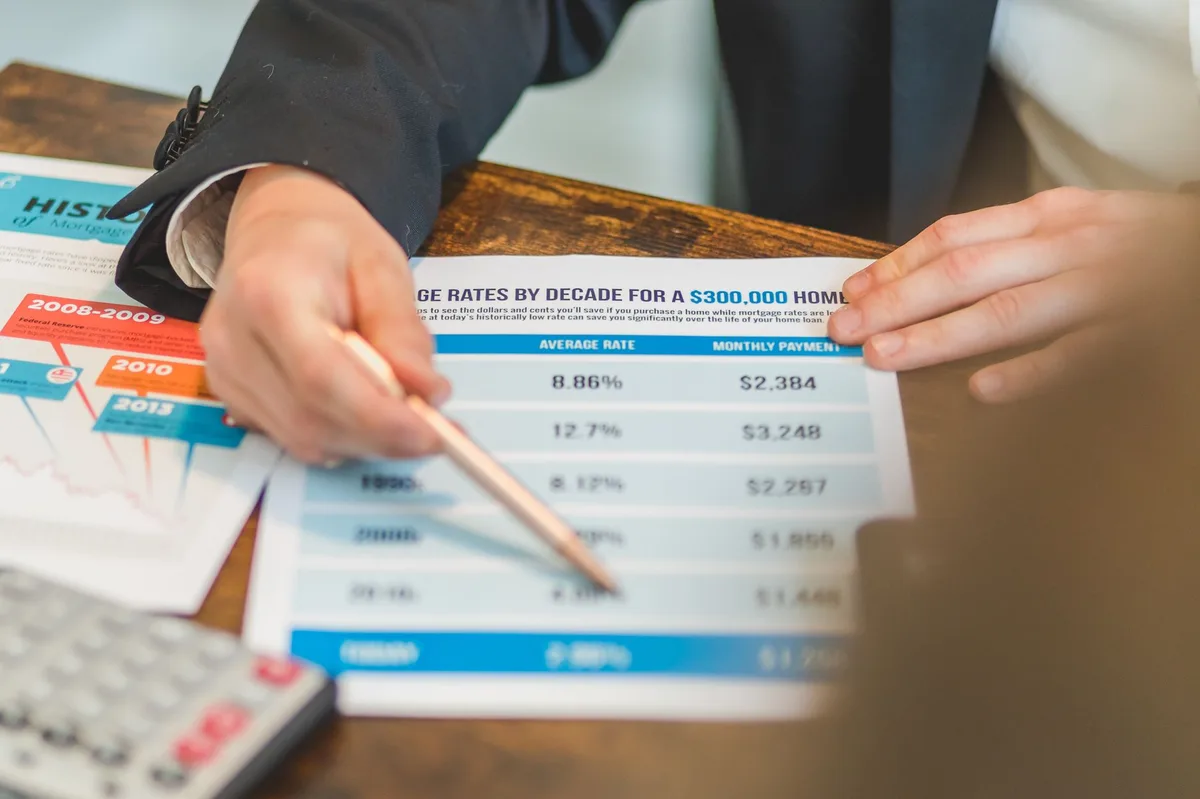
Pexels - RDNE Stock project · original
In this article
Key Takeaway: Bank of Montreal has reinstated the OSFI mortgage stress test requirement for borrowers switching their uninsured mortgage to a new lender, ending a common industry practice that allowed these switches without re-qualifying at the higher benchmark rate. This means BMO borrowers with at least 20 per cent equity who want to switch lenders at renewal must now prove they can afford payments at a rate roughly 2 percentage points higher than their contract rate.
Bank of Montreal has quietly reversed course on a longstanding industry accommodation for uninsured mortgage switches, reinstating the Office of the Superintendent of Financial Institutions stress test for borrowers who move their mortgage to a competing lender at renewal. The decision marks a significant tightening in qualification standards for a segment of the market that had largely operated outside the stress-test framework since the OSFI B-20 guideline was introduced in 2018.
What the OSFI Stress Test Is
The OSFI mortgage stress test, formally part of the B-20 guideline on residential mortgage underwriting, requires federally regulated lenders to qualify borrowers at the greater of their contract rate plus 2 percentage points or a minimum qualifying rate set by OSFI (currently 5.25 per cent as of October 2026). According to the Office of the Superintendent of Financial Institutions, the stress test ensures borrowers can still afford their mortgage if interest rates rise or their financial circumstances change (OSFI, 2026).
For a borrower offered a 4.5 per cent fixed rate, the stress test means proving you can afford payments calculated at 6.5 per cent, a materially higher threshold. The rule applies to all new insured and uninsured mortgages, refinances, and most renewals where the borrower increases their principal or switches lenders.
The Uninsured Switch Exemption
An uninsured mortgage is one where the borrower has put down at least 20 per cent, avoiding the requirement for CMHC mortgage default insurance. When a borrower with an uninsured mortgage reaches the end of their term and chooses to switch to a new lender for a better rate, the industry had generally treated this as a straight transfer rather than a new mortgage application, bypassing the stress test as long as the principal did not increase.
This exemption made sense in practice: the borrower was not taking on new debt, their loan-to-value ratio had likely improved through principal repayment and potential home price appreciation, and lenders viewed the risk as lower than a fresh purchase or refinance. The Financial Consumer Agency of Canada notes that renewals with the same lender do not require re-qualification, and the industry extended similar treatment to switches (FCAC, 2026).
Why BMO Brought the Stress Test Back
BMO has not issued a public statement detailing the rationale, but the move aligns with a broader shift toward tighter lending standards as Canadian household debt levels remain elevated and interest rate volatility persists. By requiring the stress test for switches, BMO is treating these transactions more like new originations, applying the same affordability buffer mandated by OSFI for refinances and purchases.
The change may reflect internal risk management priorities, particularly as more borrowers face payment shock when renewing at today’s higher rates after locking in historically low terms during 2020 and 2021. Principles of mortgage underwriting covered in foundational finance texts such as Principles of Finance emphasize that creditworthiness assessments must account for interest rate risk and the borrower’s capacity to service debt under adverse conditions, a principle the stress test codifies at the regulatory level.
What This Means for Borrowers
Borrowers with uninsured mortgages coming up for renewal at BMO now face a choice: renew with BMO without re-qualifying, or switch to another lender and pass the stress test. For households whose income or debt levels have changed since their original approval, or whose current rate is significantly lower than the stress-test qualifying rate, the latter option may no longer be available.
Concretely, a borrower with a remaining balance of CAD 400,000 and a household income of CAD 120,000 might qualify for a 4.5 per cent rate based on income, but the stress test at 6.5 per cent could push their debt service ratios above the 44 per cent total debt service threshold many lenders enforce, disqualifying them from switching. That borrower would then be locked into renewing with BMO, potentially at a less competitive rate than competitors are advertising.
Read also: OSFI Eliminates Stress Test for Uninsured Mortgage Switches in Canada
According to the Canada Mortgage and Housing Corporation, understanding the terms of your mortgage term and your options at renewal is critical to managing long-term housing costs (CMHC, 2026). Borrowers affected by this change should compare BMO’s renewal offer against the rates they could access by switching, factoring in any early prepayment they can make to reduce the balance and improve qualification odds.
Industry Implications
BMO is the first of the Big Five banks to formally reinstate the stress test for uninsured switches, but the move may signal a broader industry trend. If other federally regulated lenders follow, the practical exemption that has existed for uninsured switches could disappear, reducing rate competition at renewal and leaving more borrowers captive to their current lender.
For now, borrowers with uninsured mortgages at other institutions can still switch without re-qualifying, but that window may be closing. Financial advisors and mortgage brokers are already counselling clients to consider switching before renewal if they anticipate difficulty passing the stress test, locking in a better rate while the exemption still exists elsewhere.
What to Do Before Your Term Ends
If your mortgage term with any lender is ending in the next 12 months and you have at least 20 per cent equity, check whether your lender still allows switches without the stress test. If you are with BMO or any institution that has adopted the stricter standard, run the numbers: calculate your qualifying payment at your contract rate plus 2 percentage points and confirm your debt service ratios stay within limits.
If the stress test disqualifies you from switching, focus on negotiating the best possible renewal rate with your current lender. Lenders know you are less likely to leave if re-qualification is required, so bring competing offers and be prepared to push for rate concessions or better terms.
This is a dynamic area of mortgage regulation and lender policy. Rules, rates, and lender practices change frequently. Verify current qualification requirements and available rates with a licensed mortgage broker or your financial institution before making any renewal or switching decision.
Conclusion
BMO’s decision to apply the OSFI stress test to uninsured mortgage switches represents a meaningful tightening in the Canadian mortgage market, closing a qualification gap that had made switching lenders at renewal easier for borrowers with significant equity. While the change affects only BMO customers for now, it may mark the beginning of a broader industry shift. Borrowers approaching renewal should understand how the stress test works, assess their ability to qualify under the higher benchmark rate, and explore their options while the window for switching without re-qualification remains open at other lenders.
Disclaimer: This article provides general educational information only and is not personalized financial, lending, legal, or tax advice, nor an offer or commitment to lend. Mortgage qualification rules, stress-test requirements, and available products vary by province, territory, and lender. Rates and policies change frequently. Confirm current terms, eligibility, and rates with a licensed mortgage broker or your financial institution for your personal situation.
Sources
- Residential Mortgage Underwriting Practices and Procedures - Guideline B-20 (accessed )
- Mortgages (accessed )
- Home Buying (accessed )
- Principles of Finance (accessed )
Related articles
OSFI Eliminates Stress Test for Uninsured Mortgage Switches in Canada
OSFI removes the mortgage stress test for uninsured switches starting November 21, 2026. Learn who qualifies and how this helps Canadian homeowners.
Understanding OSFI's Mortgage Stress Test Elimination at Renewal in Canada
OSFI eliminated the stress test at renewal for uninsured mortgages in Canada. Learn what changed, who benefits, and how it affects your mortgage renewal.
BMO's Return of the OSFI Stress Test for Uninsured Mortgage Switches in Canada
BMO has brought back stress-test checks for some uninsured mortgage switches in Canada. Learn what this means at renewal.
