OSFI Eliminates Stress Test for Uninsured Mortgage Switches in Canada
Starting November 21, 2026, Canadian homeowners with uninsured mortgages can switch lenders at renewal without passing the mortgage stress test, giving borrowers significantly more negotiating power.
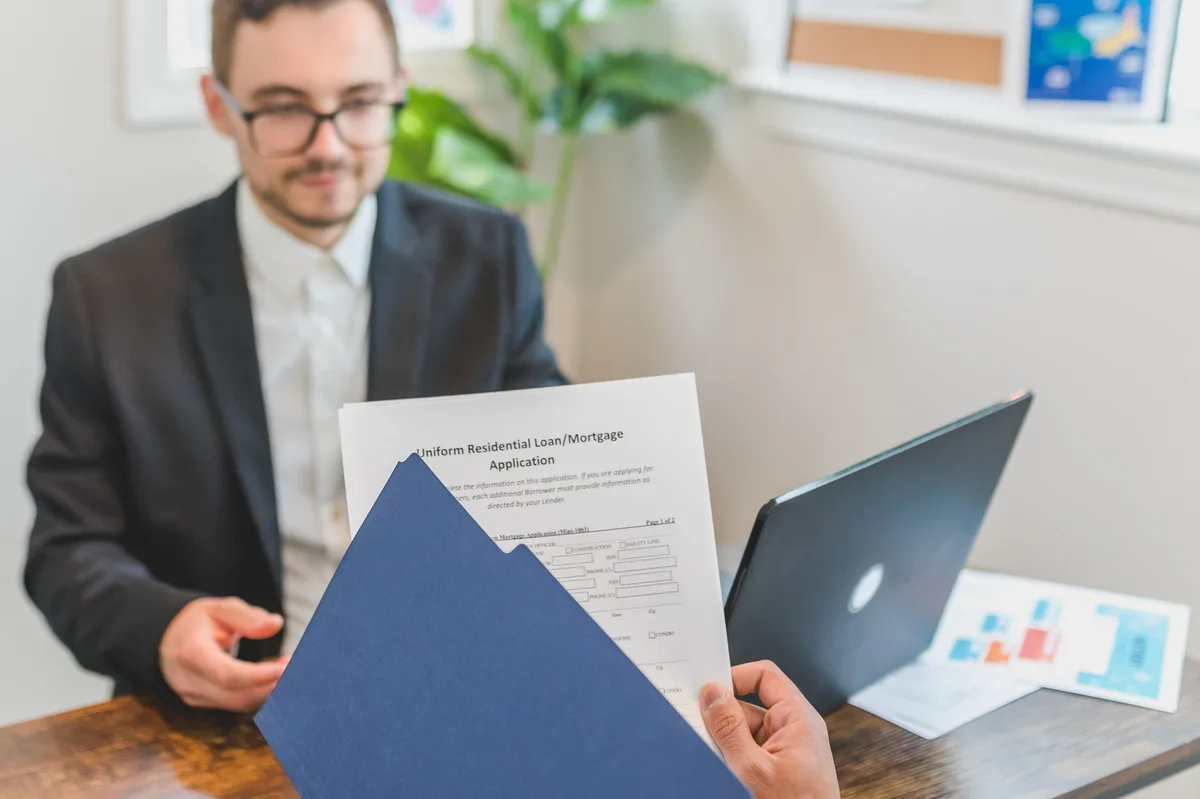
Pexels - RDNE Stock project · original
In this article
Starting November 21, 2026, the Office of the Superintendent of Financial Institutions (OSFI) will eliminate the mortgage stress test requirement for uninsured mortgage switches in Canada. This means homeowners with at least 20 per cent equity who want to move their existing mortgage to a new lender at renewal can do so without re-qualifying under the stress test. The change applies only to straight switches where the mortgage amount and amortization remain the same or decrease. It does not apply to refinances that increase the principal or extend the amortization.
What Changed
Under the previous OSFI B-20 guideline, all federally regulated lenders had to qualify borrowers at the higher of the contract rate plus two percentage points or 5.25 per cent, even for straightforward switches at renewal. According to the Office of the Superintendent of Financial Institutions, this requirement sometimes trapped borrowers with their existing lender, limiting their ability to shop for better rates.
The November 21, 2026 policy change removes the stress test for uninsured mortgage switches specifically. An uninsured mortgage is one where the borrower has at least 20 per cent equity in the property and does not require mortgage default insurance from CMHC or a private insurer.
Who This Affects
This change benefits homeowners renewing an uninsured mortgage who want to switch to a different lender for a better rate or terms. To qualify for a switch without the stress test, you must meet these conditions:
- You have at least 20 per cent equity in your home (loan-to-value of 80 per cent or less).
- You are moving your mortgage to a new lender at the end of your current term.
- The new mortgage amount does not exceed your current principal balance.
- The amortization period stays the same or decreases.
- You are not taking cash out or consolidating other debt.
If you meet these criteria, the new lender can approve your switch based on your ability to make the actual mortgage payment at the new rate, without applying the stress test buffer.
What This Means for Borrowers
The elimination of the stress test for switches gives Canadian homeowners significantly more leverage when their mortgage term ends. Previously, even if you found a lender offering a rate one percentage point lower than your current lender, you might not qualify for the switch if your income had dropped, your debt had increased, or rates had climbed since your original approval.
Now, as long as you can afford the actual payment at the new lender’s rate and you are not increasing your mortgage balance, you can move your business. This restores competitive pressure in the renewal market and reduces the risk of being locked into an uncompetitive rate, as noted by the Financial Consumer Agency of Canada in its mortgage guidance.
Read also: Understanding OSFI’s Mortgage Stress Test Elimination at Renewal in Canada
What Has Not Changed
The stress test still applies in these situations:
- Refinances: If you want to increase your mortgage amount to access equity, consolidate debt, or extend your amortization, you must still pass the stress test.
- Insured mortgages: Mortgages with less than 20 per cent equity that require CMHC insurance continue to be subject to the stress test under separate insurance rules.
- New purchases: Buyers taking out a new mortgage to purchase a home must still qualify under the stress test.
- Renewals with the same lender: Your existing lender does not stress test you at renewal if you stay with them, but this was already the case before the policy change.
Prepayment penalties may still apply if you break your existing mortgage before the term ends to switch lenders, particularly with a closed fixed-rate mortgage. Calculate whether the penalty (often the interest rate differential) outweighs the savings from the lower rate at the new lender.
Next Steps
If your uninsured mortgage is renewing in the coming months, contact at least two or three lenders or a licensed mortgage broker to compare offers. Request rate quotes and ask explicitly whether you qualify for a switch under the new November 21, 2026 rules. Confirm that your situation meets the criteria (same or lower principal, same or shorter amortization, and sufficient equity).
If your renewal is further out, keep this option in mind as you approach the end of your term. The ability to switch without re-qualifying under the stress test gives you a stronger position to negotiate with your current lender or move to a competitor offering better terms.
Important Disclaimer
This information is general educational content only and not personalized financial, lending, or legal advice. Mortgage qualification rules, products, and rates vary by lender, province, and individual circumstances. The OSFI policy change applies to federally regulated lenders and may not cover all institutions. Verify current requirements and your eligibility with a licensed mortgage professional before making decisions. Rates and policies are subject to change. As of October 2026, confirm the latest OSFI B-20 guideline details and how they apply to your specific situation.
Sources
- Residential Mortgage Underwriting Practices and Procedures - Guideline B-20 (accessed )
- Mortgages (accessed )
- Bank of Canada (accessed )
Related articles
BMO Brings Back the OSFI Stress Test for Uninsured Mortgage Switches in Canada
BMO now applies the OSFI stress test to uninsured mortgage switches in Canada, ending an industry exemption and tightening qualification for borrowers.
Understanding OSFI's Mortgage Stress Test Elimination at Renewal in Canada
OSFI eliminated the stress test at renewal for uninsured mortgages in Canada. Learn what changed, who benefits, and how it affects your mortgage renewal.
BMO's Return of the OSFI Stress Test for Uninsured Mortgage Switches in Canada
BMO has brought back stress-test checks for some uninsured mortgage switches in Canada. Learn what this means at renewal.
