How to Negotiate Your Best Mortgage Renewal Rate in Canada (2026-2027)
Learn how to negotiate the best mortgage renewal rate during the 2026-2027 renewal surge with proven strategies to save thousands over your term.
Pexels - Kampus Production · original
In this article
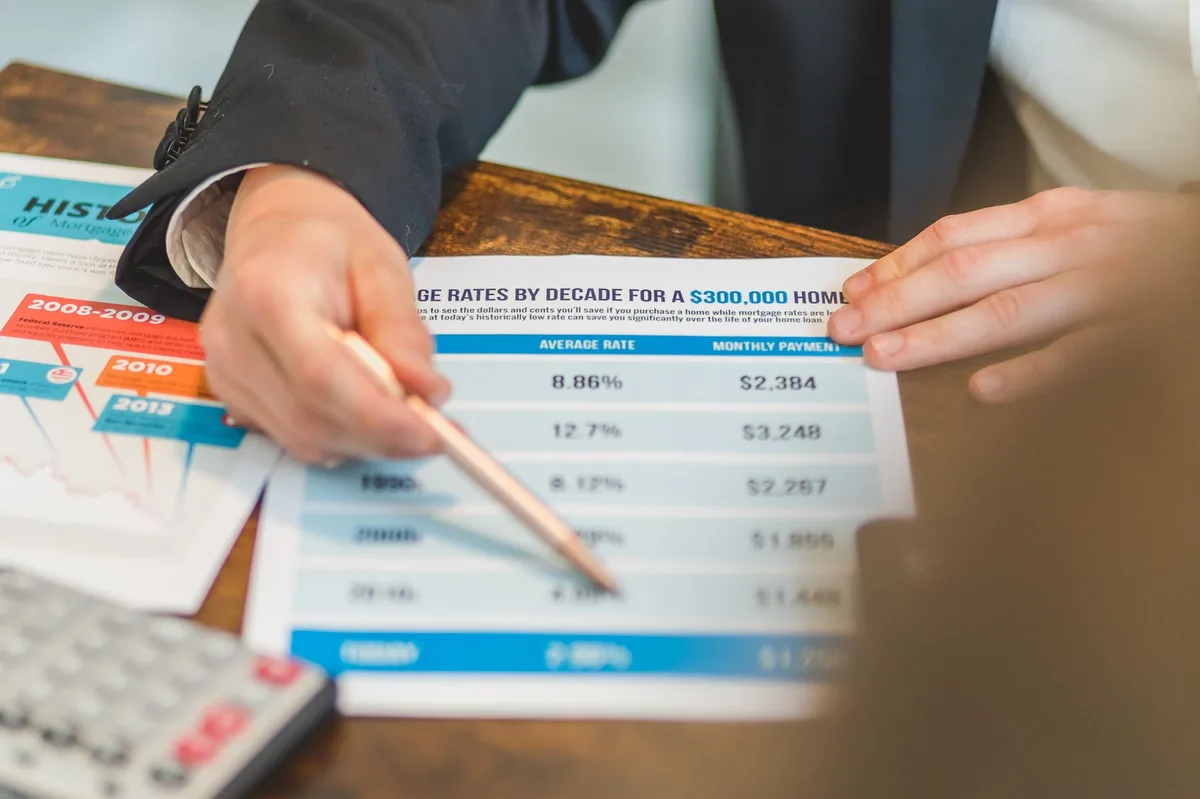
Between 2026 and 2027, hundreds of thousands of Canadian homeowners will face mortgage renewals after locking in historically low rates during the 2020-2022 period. Your renewal is not automatic at your lender’s posted rate. By negotiating effectively, you can save thousands of dollars over your next term, even in a higher-rate environment. Start early, gather competing offers, and use your strongest leverage: the threat of moving your mortgage to another lender.
What You Will Learn
This guide walks you through the negotiation process step by step, from understanding your renewal timeline to securing your best rate in writing. You will learn how to research current rates, leverage competing offers, and avoid the most common renewal mistakes that cost Canadian borrowers money.
Step 1: Review Your Mortgage Details and Renewal Timeline
Locate your current mortgage statement or original mortgage agreement. Note your maturity date (when your term ends), your current rate, whether you have a fixed or variable rate, your remaining amortization, and any prepayment privileges or penalties. Canadian mortgages renew at the end of the term (typically one to five years), not at the end of the amortization.
Your lender must send a renewal statement at least 21 days before maturity under federal regulations, but waiting until then costs you negotiating time (FCAC, 2026). Start your research four to six months before your maturity date.
Step 2: Research Current Rates and Gather Competing Quotes
Check current mortgage rates from multiple sources: major banks (RBC, TD, Scotiabank, CIBC, BMO), credit unions, mortgage brokers, and online rate aggregators such as Ratehub.ca (Ratehub, 2026). Note both posted rates and discounted rates for your term length and mortgage type.
Contact at least three lenders or a licensed mortgage broker to obtain pre-approval offers. These competing quotes are your strongest negotiating tool. Brokers often access wholesale rates unavailable directly from banks and can shop your mortgage across dozens of lenders at no cost to you.
Step 3: Assess Your Financial Position and Credit
Review your credit score and credit report before negotiating. A score above 700 typically qualifies you for better rates. Pay down outstanding balances and correct any errors on your report.
Calculate your current loan-to-value ratio (LTV). If your home has appreciated or you have paid down principal, a lower LTV strengthens your negotiating position. Under OSFI guidelines, your renewal must still meet the mortgage stress test if you switch lenders, but renewals with your current lender are exempt from the stress test.
Step 4: Contact Your Current Lender Early
Reach out to your lender’s retention department (not the general customer service line) four to six months before maturity. State clearly that you are shopping your mortgage and have received competitive offers. Do not accept the first renewal offer, which is almost always higher than what the lender is willing to negotiate.
Ask for their best rate directly and mention the competing quotes you have gathered. Be polite but firm. Your long payment history and the cost of losing your business to another lender give you leverage.
Step 5: Negotiate Using Your Research and Loyalty
Present your competing offers in writing or by email. Highlight your positive payment history, credit score, and the equity you have built. Ask your lender to match or beat the best rate you have received elsewhere.
If your lender offers a rate reduction but it still exceeds your best competing offer, counter again. As explained in foundational finance texts such as Principles of Finance, lenders balance customer retention costs against interest income, and the retention department has authority to discount rates beyond standard posted offers.
Negotiate the full package, not just the rate. Consider prepayment privileges (the ability to pay extra without penalty), portability (moving your mortgage to a new property), and the penalty structure if you break your term early. The interest rate differential (IRD) penalty on a fixed-rate mortgage can be substantial.
Step 6: Compare Your Lender’s Final Offer with Competitors
Once your current lender provides their best offer, compare it line by line with your competing pre-approvals. Consider the total interest cost over the term, fees (some lenders charge administrative or discharge fees), and flexibility features.
If a competitor’s offer is better, inform your current lender and give them one final chance to match it. If they decline, you are free to switch. Switching lenders at renewal does not trigger prepayment penalties (those apply only if you break your mortgage before maturity).
Step 7: Confirm Your Rate in Writing and Lock It In
Once you accept an offer, obtain the rate hold or commitment in writing immediately. Rate holds typically last 90 to 120 days. Read the renewal agreement or new mortgage contract carefully before signing, ensuring the rate, term, prepayment privileges, and penalty clauses match what was negotiated.
If switching lenders, your new lender will handle the discharge and transfer process. There may be legal fees (typically a few hundred dollars), but many lenders offer promotions covering these costs during competitive renewal periods.
Read also: How to Refinance Your Mortgage in Canada and When It Makes Sense
Practical Tips for Renewal Negotiations
Start early. The best negotiating window is four to six months before maturity, when you have time to explore all options without pressure.
Use a mortgage broker. Brokers work for you, not the lender, and access rates you cannot get directly. Their service is free because lenders pay them.
Do not automatically renew. Signing your lender’s renewal offer without negotiating almost always costs you money. Lenders count on customer inertia.
Consider term length strategically. If you expect rates to fall in the next few years, a shorter term (one or two years) gives you flexibility to renew again sooner. If you want stability, a five-year fixed rate locks in predictability.
Monitor the Bank of Canada policy rate. The policy rate influences variable mortgage rates and signals the overall rate environment (Bank of Canada, 2026). If the policy rate is trending downward, variable rates or shorter terms may offer savings.
Common Renewal Mistakes to Avoid
Waiting until the renewal statement arrives. By then, your negotiating time is compressed and your options are limited.
Accepting loyalty offers without comparing. Lenders often frame renewal offers as loyalty rewards, but they are rarely the best available rate.
Focusing only on rate and ignoring prepayment penalties. A slightly lower rate with a harsh IRD penalty can cost more if your circumstances change and you need to break the mortgage early.
Switching lenders without considering legal fees and effort. Sometimes your current lender’s matched rate is close enough that the convenience of staying outweighs a marginal rate difference.
Frequently Asked Questions
When should I start negotiating my mortgage renewal?
Begin four to six months before your maturity date to give yourself time to research, gather quotes, and negotiate without pressure.
Can I switch lenders at renewal without penalty?
Yes. At maturity, you can switch lenders without triggering prepayment penalties. Penalties apply only if you break your mortgage before the term ends.
Will I need to requalify with the stress test if I renew with my current lender?
No. Renewals with your existing lender are exempt from the OSFI mortgage stress test. However, if you switch lenders, you must qualify under the stress test at the higher of your contract rate plus two per cent or the qualifying rate.
What if my lender will not negotiate?
If your current lender refuses to offer a competitive rate, switch to a lender who provided a better pre-approval. You are not obligated to renew with your current lender.
Conclusion
The 2026-2027 renewal surge brings both challenge and opportunity. While rates are higher than the pandemic-era lows, effective negotiation can still save you thousands of dollars over your term. Treat your renewal as a fresh mortgage transaction, start early, gather competing offers, and negotiate confidently. Your mortgage is likely your largest financial obligation, and your lender expects most borrowers to renew passively at the offered rate. By taking control of the process, you turn renewal into a chance to optimize your mortgage and strengthen your financial position.
This article provides general educational information only and is not personalized financial, lending, legal, or tax advice. Mortgage rates, qualification requirements, and available products vary by province, lender, and individual circumstances. Renewal rules and the mortgage stress test requirements differ depending on whether you renew with your current lender or switch to a new one. Always confirm current rates and terms with a licensed mortgage professional or your financial institution before making decisions. Consult a qualified mortgage broker or advisor for advice tailored to your specific situation.
Sources
- Mortgages and Home Buying (accessed )
- Key Interest Rate (accessed )
- Mortgage Rates and Information (accessed )
- Principles of Finance (accessed )
Related articles
How to Navigate Mortgage Renewals in Canada When Rates Are Higher
Navigate your mortgage renewal when rates are high. Compare fixed vs variable, evaluate term lengths, and learn negotiation strategies for Canadian homeowners.
How to Refinance Your Mortgage in Canada: When It Makes Sense
Learn when refinancing your Canadian mortgage makes sense, how it differs from renewal, and what costs to consider before breaking your term.
Renewing Your Mortgage in Canada: What to Expect in 2026
Learn what to expect when renewing your Canadian mortgage in 2026, including rate options, qualification rules, and how to prepare for the best terms.
