Renewing Your Mortgage in Canada: What to Expect in 2026
Mortgage renewal in 2026 will require careful planning as homeowners face changing rate environments, new lender options, and updated qualification requirements.
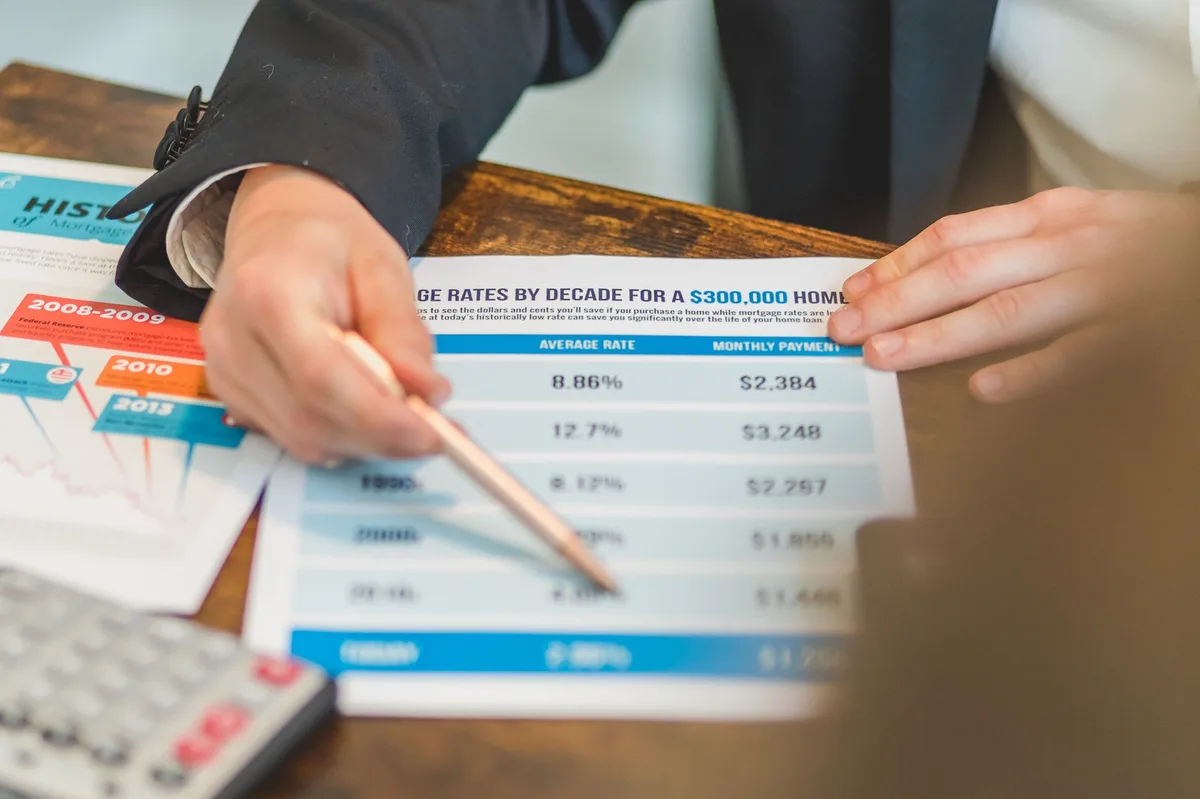
Pexels - RDNE Stock project · original
In this article
Key Takeaway
Mortgage renewal in Canada means renegotiating your mortgage at the end of your current term (typically one to five years), which is different from your full amortization period. In 2026, homeowners should expect continued volatility in interest rates tied to Bank of Canada policy decisions, stricter qualification requirements under the OSFI stress test, and competitive opportunities to shop between lenders. Starting your renewal process 120 days before your term ends gives you the leverage to negotiate better rates and avoid automatic renewal at less favourable terms.
What Mortgage Renewal Means in Canada
When Canadians speak about mortgage renewal, they are referring to the end of the mortgage term, the contract period (usually one to five years) during which your interest rate and conditions are locked in. This differs from the amortization period, which is the total time it takes to pay off your mortgage completely (often 25 or 30 years). As foundational texts such as Principles of Finance explain, mortgage instruments are structured with periodic renegotiation points that allow both borrowers and lenders to adjust to changing economic conditions.
According to the Financial Consumer Agency of Canada, most Canadian mortgages require renewal multiple times before the loan is fully repaid (FCAC, 2026). At renewal, you have the option to stay with your current lender at new terms, negotiate better conditions, or switch to a different lender entirely. The renewal is not the same as refinancing, which involves breaking your existing mortgage contract early and may trigger prepayment penalties.
The 2026 Rate Environment
The mortgage rate landscape in 2026 will reflect the Bank of Canada’s ongoing monetary policy responses to inflation, employment, and economic growth. As of October 2026, the Bank of Canada’s policy interest rate continues to influence the prime rate, which in turn affects variable-rate mortgages and serves as a benchmark for fixed-rate pricing (Bank of Canada, 2026).
Homeowners renewing in 2026 who secured their original terms in 2021 or 2022, when rates were historically low, will likely face higher rates at renewal. The gap between your current rate and available renewal rates will be a key factor in your monthly payment increase. For example, moving from a 2.5 per cent fixed rate to a 5.0 per cent fixed rate on a $400,000 mortgage balance with 20 years remaining could increase your monthly payment by several hundred dollars.
Your Renewal Options
At renewal, you will choose between fixed-rate and variable-rate products, and between staying with your current lender or switching. Fixed-rate mortgages lock your interest rate for the entire term, offering payment stability and protection against rate increases. Variable-rate mortgages fluctuate with the prime rate and may offer lower starting rates but expose you to payment increases if rates rise.
Canada Mortgage and Housing Corporation notes that borrowers should weigh their risk tolerance, budget flexibility, and rate outlook when choosing between fixed and variable products (CMHC, 2026). In a rising-rate environment, fixed rates offer certainty. In a declining or stable environment, variable rates may save money over the term.
Switching lenders at renewal can unlock better rates and more favourable terms, but requires requalifying under current rules. The OSFI B-20 mortgage stress test applies to all new mortgages and switches, meaning you must prove you can afford payments at a rate higher than your actual contract rate (typically the contract rate plus two percentage points, or the Bank of Canada’s qualifying rate, whichever is higher). If your income, employment, or credit situation has changed, or if your home value has declined, switching may be more difficult.
Timing and Preparation
Canadian lenders are required to send renewal statements at least 21 days before your term ends, but savvy borrowers start the process much earlier. Beginning 120 days before your renewal date gives you time to shop rates, gather documentation, and negotiate. Many lenders allow you to lock in a rate up to 120 days in advance, protecting you if rates rise before your term ends.
Read also: How Mortgage Payments Change at Renewal in Canada
To prepare for renewal, review your current mortgage balance, remaining amortization, and payment history. Check your credit score and address any issues that could affect your qualification. Gather recent pay stubs, tax returns, and proof of employment. If you plan to switch lenders, factor in potential appraisal fees, legal fees, and the time required to complete the application process.
Compare offers from at least three lenders, including your current lender, a major bank, a credit union, and an online or alternative lender. Mortgage brokers can streamline this process by accessing multiple lenders at once. Pay attention not just to the interest rate, but to prepayment privileges, penalty structures, and portability options.
What to Avoid
The most common mistake at renewal is accepting your lender’s automatic renewal offer without shopping around. Lenders often present renewal rates that are higher than the rates available to new customers or through negotiation. Failing to respond to your lender’s renewal statement by the deadline results in automatic renewal at the stated rate, which may not be competitive.
Do not wait until the last minute. Rushed decisions limit your options and eliminate the leverage that comes from having time to switch lenders. Avoid ignoring changes in your financial situation. If your income has dropped, your debt has increased, or your credit score has declined, address these issues early or consider strategies to stay with your current lender, where you will not need to requalify.
Moving Forward
Renewal in 2026 is an opportunity to reassess your mortgage strategy in light of current economic conditions, your personal financial goals, and the competitive lending landscape. Start early, compare offers, understand the qualification requirements, and do not hesitate to negotiate. Whether you stay with your lender or switch, the decisions you make at renewal will shape your housing costs for the next one to five years.
Financial Disclaimer: This article provides general educational information only and is not personalized financial, legal, tax, or lending advice. It is not an offer or commitment to lend. Mortgage products, rates, qualification requirements, prepayment options, and penalties vary by lender, province, and your individual circumstances. The OSFI mortgage stress test, mortgage default insurance rules, and available programs differ depending on where you live and which lender you use. Interest rates change frequently. Verify current rates, terms, and eligibility with a licensed mortgage broker or your financial institution before making any decisions. For advice tailored to your situation, consult a licensed mortgage professional or qualified financial advisor.
Sources
- Mortgages (accessed )
- Home Buying (accessed )
- Key Interest Rate: Target for the Overnight Rate (accessed )
- Principles of Finance (accessed )
Related articles
How Mortgage Payments Change at Renewal in Canada
Learn how your mortgage payment changes at renewal in Canada based on new rates, remaining amortization, and balance - includes 2026 examples.
Should You Renew Your Mortgage for 1 or 5 Years in a Falling Rate Environment in Canada
Compare 1-year vs 5-year mortgage term renewals in a falling rate environment. Learn which term makes sense for Canadian borrowers.
How to Navigate Mortgage Renewals in Canada When Rates Are Higher
Navigate your mortgage renewal when rates are high. Compare fixed vs variable, evaluate term lengths, and learn negotiation strategies for Canadian homeowners.
