How to Navigate Mortgage Renewals in Canada When Rates Are Higher
With mortgage rates elevated and renewal terms tightening, Canadian homeowners face critical decisions. Learn how to evaluate your options, negotiate effectively, and choose the right renewal strategy for your financial situation.
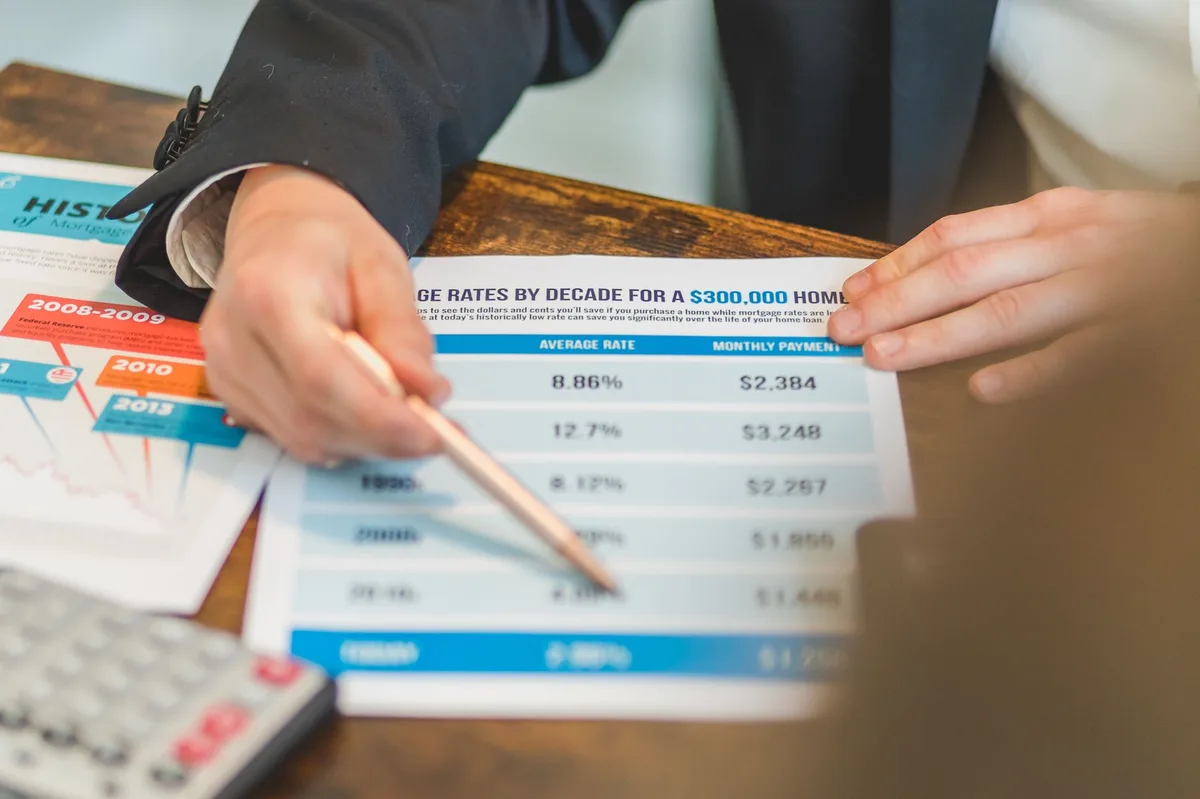
Pexels - RDNE Stock project · original
In this article
Canadian homeowners renewing mortgages in 2026 face a dramatically different landscape than five years ago. Interest rates remain elevated following the Bank of Canada’s aggressive tightening cycle, and lenders have tightened qualification standards under OSFI’s B-20 mortgage stress test. The right renewal strategy can save you thousands of dollars in interest while maintaining financial flexibility, but the wrong choice can lock you into unfavourable terms precisely when you need options most.
What You Will Learn
This guide walks you through the complete mortgage renewal decision process when rates are higher than your current term. You will learn how to assess your current mortgage position, compare fixed versus variable rate options in today’s environment, evaluate term length trade-offs, determine whether switching lenders makes sense, negotiate effectively with your current lender, and align your choice with your broader financial situation and risk tolerance. By the end, you will have a clear framework for making an informed renewal decision that fits your circumstances.
Step 1: Understand Your Current Position
Before evaluating renewal options, gather complete information about your existing mortgage. You need your current interest rate, remaining amortization period, mortgage balance, payment amount, and the exact renewal date. Check whether your mortgage is closed or open, and review any prepayment privileges you have used or have remaining.
Request your renewal notice from your lender at least 120 days before your term ends. According to the Financial Consumer Agency of Canada, lenders must send renewal statements at least 21 days before maturity, but savvy homeowners start earlier (FCAC, 2026). The renewal notice shows the interest rate your lender is offering, but this initial offer is rarely the best rate available and should be viewed as a starting point for negotiation, not a final decision.
Calculate how much interest you have paid over your current term and how much principal you have reduced. This context helps you understand the financial impact of rate changes. If you had a 2.5 per cent five-year fixed rate and are now facing renewal offers around 5.5 per cent, your monthly payment could increase by 40 per cent or more on the same amortization schedule, which significantly affects your budget and long-term interest costs.
Step 2: Compare Fixed Versus Variable Rates
The fixed versus variable decision takes on heightened importance when rates are elevated. A fixed-rate mortgage locks your interest rate for the entire term, providing payment certainty but typically at a premium over variable rates. A variable-rate mortgage fluctuates with the lender’s prime rate, which moves in response to Bank of Canada policy rate changes (Bank of Canada, 2026).
As of October 2026, fixed rates remain higher than variable rates in most cases, reflecting market expectations about the future path of interest rates. If the Bank of Canada is expected to cut rates further, variable rates may decline over your term, potentially saving you thousands. However, if rates remain elevated or rise again, variable-rate holders face payment increases and extended amortization.
Evaluate your personal circumstances honestly. If your budget has minimal room for payment increases, a fixed rate provides essential certainty even if it costs more initially. If you have financial flexibility and believe rates will decline based on economic forecasts, a variable rate offers potential savings. Review current mortgage rate comparisons on platforms like Ratehub to see the spread between fixed and variable offerings (Ratehub, 2026).
Consider a hybrid approach if your lender offers it: split your mortgage between fixed and variable portions. This balances certainty with flexibility, allowing you to benefit partially from rate decreases while capping your exposure to increases.
Step 3: Evaluate Your Term Length Options
Mortgage terms in Canada typically range from one to five years, with five-year terms being most common. When rates are high, term length strategy becomes critical. Shorter terms (one to three years) mean you renew more frequently, giving you opportunities to lock in lower rates if they decline, but you face renewal risk if rates remain elevated or climb higher.
Longer terms (four to five years) lock in your current rate for an extended period. If you secure a competitive rate now and rates rise further, you benefit from long-term certainty. If rates fall sharply, you are locked in at the higher rate unless you pay substantial prepayment penalties to break your mortgage.
As foundational texts such as Principles of Finance explain, the relationship between short-term and long-term interest rates reflects market expectations and risk premiums. When evaluating term length, consider your employment stability, income trajectory, and overall financial plans. If you anticipate major life changes (job transition, relocation, family expansion) within two years, a shorter term preserves flexibility. If your situation is stable and you value payment predictability, a longer term may suit you better.
Calculate the total interest cost over different scenarios. A one-year term at 5.0 per cent followed by a four-year renewal at 4.5 per cent produces different total costs than a five-year term at 5.2 per cent today. Run multiple scenarios to understand the financial implications.
Step 4: Consider Switching Lenders
You are not obligated to renew with your current lender. Switching lenders at renewal can unlock better rates, more favourable terms, or features your current lender does not offer. At renewal, you are switching, not refinancing, so you avoid most closing costs if your mortgage balance stays the same and you do not access additional equity.
Start shopping for rates at least 90 days before renewal. Contact mortgage brokers, who have access to multiple lenders and can compare offerings quickly. Brokers often secure rates below posted rates, particularly for well-qualified borrowers with strong credit and stable income. Obtain rate quotes from major banks, credit unions, and alternative lenders.
Compare not just interest rates but the full package: prepayment privileges (the percentage of principal you can prepay annually without penalty), portability options (the ability to transfer your mortgage to a new property), and penalty calculation methods (interest rate differential versus three months’ interest). A slightly higher rate with generous prepayment privileges can cost less over time if you plan to make lump-sum payments.
Understand the costs of switching. If you are moving your mortgage to a new lender, you may pay legal fees (typically CAD 500 to CAD 1,000), appraisal fees if the new lender requires a property valuation, and discharge fees charged by your current lender (around CAD 300). Calculate your break-even point: how much you save in interest must exceed these costs for switching to make financial sense.
If you have a HELOC (home equity line of credit) bundled with your mortgage, switching becomes more complex. You may need to refinance the entire package or set up separate financing for the HELOC, which can involve higher costs and additional qualification steps.
Step 5: Negotiate With Your Current Lender
The renewal rate your lender first offers is almost never their best rate. Lenders expect negotiation and reserve their most competitive rates for borrowers who ask. Armed with competing offers from other lenders, approach your current lender to negotiate better terms.
Present specific competing offers. Tell your lender, “I have a firm offer from another institution at 4.8 per cent for a five-year fixed term with 20 per cent annual prepayment privileges. Can you match or beat this rate?” Concrete numbers give the lender something to work with and demonstrate you are a serious, informed borrower.
Timing matters. Negotiate 60 to 90 days before your renewal date when you still have time to switch lenders if negotiations fail. If you wait until the last week, your leverage disappears and the lender knows switching is impractical.
Highlight your value as a customer. If you have been with the lender for many years, hold other accounts (chequing, savings, investments), have made all payments on time, and have improved your credit score or increased your home equity, mention these factors. Lenders retain loyal, low-risk customers with better rates because keeping you costs less than acquiring a new borrower.
If your lender will not match competing offers, ask about other concessions: waiving the appraisal fee, offering better prepayment terms, or bundling other products at a discount. Every concession adds value even if the rate itself does not budge.
Step 6: Factor in Your Financial Situation and Risk Tolerance
Your renewal decision must align with your broader financial picture and personal risk tolerance. Assess your household income stability, your emergency fund, other debts, and your timeline to mortgage-free homeownership.
If your income is variable (self-employed, commission-based, contract work), fixed rates provide budgeting certainty that is especially valuable. If you carry high-interest debt (credit cards, unsecured lines of credit), prioritize prepayment privileges so you can direct extra funds to your mortgage when you pay down other debts.
Read also: How to Refinance Your Mortgage in Canada: When It Makes Sense
Evaluate your comfort with uncertainty. Some homeowners lose sleep over variable-rate fluctuations even when they can afford payment increases. The psychological cost of uncertainty can outweigh modest financial savings. If payment predictability gives you peace of mind, a fixed rate is worth the premium.
Consider your long-term plans. If you intend to sell your home within three years, a shorter term or variable rate may make more sense because you avoid large prepayment penalties when you sell. If you plan to stay in your home for a decade or more, a longer term with aggressive prepayment privileges accelerates your path to mortgage freedom.
Review the OSFI mortgage stress test requirements. Even at renewal, if you switch lenders or refinance, you must qualify at the higher of your contract rate plus 2 percentage points or 5.25 per cent. If higher rates make it difficult to qualify elsewhere, staying with your current lender (who does not re-test you at straight renewal) may be your only practical option, making negotiation even more critical.
Practical Tips for Renewal Success
Start early. Begin researching rates and lender options 120 days before renewal. Early preparation gives you time to improve your credit score, gather documentation, and negotiate without pressure.
Improve your credit score before renewal. Pay down credit card balances, avoid new credit applications, and correct any errors on your credit report. A higher credit score can unlock better rates and terms.
Document your income thoroughly. If you are self-employed or have irregular income, gather tax returns, notices of assessment, and financial statements well in advance. Lenders require extensive documentation for self-employed borrowers, and delays can limit your options.
Understand prepayment penalties if you are breaking your current mortgage early to refinance. Closed mortgages charge penalties calculated as the greater of three months’ interest or the interest rate differential (IRD). IRD penalties can be substantial, often tens of thousands of dollars, and can eliminate any savings from refinancing. Calculate this carefully before deciding to break your mortgage mid-term.
Use a mortgage calculator to model different scenarios. Seeing the exact payment amounts, total interest costs, and amortization timelines for each option clarifies the financial impact of your choice.
Common Mistakes to Avoid
Accepting the first renewal offer without negotiating is the most common and costly mistake. Lenders count on inertia, and borrowers who simply sign the renewal notice typically pay 0.5 to 1.0 percentage points more than they could secure through negotiation or switching.
Focusing only on interest rate while ignoring features can backfire. A slightly lower rate with restrictive prepayment penalties or poor prepayment privileges can cost more over time if your circumstances change.
Waiting until the last minute eliminates your leverage. If you receive your renewal notice 21 days before maturity and only then start shopping, you have insufficient time to qualify with a new lender, and your current lender knows it.
Ignoring the impact of amortization changes can lead to payment shock. If your remaining amortization is now 20 years instead of 25, your payments will be higher even at the same interest rate. Understand whether extending your amortization (if permitted) makes sense for your budget.
Overestimating your ability to handle variable-rate risk is dangerous. If you choose variable rates assuming you can absorb payment increases but have no financial cushion, a rate spike can force you into financial distress.
Frequently Asked Questions
Can I negotiate my mortgage renewal rate even if I have poor credit?
Yes, though your negotiating power is weaker. If your credit has declined since you first obtained your mortgage, your current lender is less likely to offer competitive rates, and switching lenders may be difficult or impossible. Focus on demonstrating stability (steady employment, on-time payments) and offering to bundle other products to improve your position.
What happens if I do nothing and let my mortgage renew automatically?
If you do not sign a renewal agreement or make other arrangements, your mortgage typically converts to your lender’s standard variable rate, which is usually much higher than negotiated rates. This can cost you thousands in unnecessary interest. Always take action before your renewal date.
Should I renew early if I see rates dropping?
Most lenders allow you to lock in a renewal rate 120 days in advance. If rates are declining, wait as long as possible before locking in. If rates are rising, locking in early can protect you. Monitor Bank of Canada announcements and economic forecasts to time your decision strategically.
Is it worth paying a penalty to break my mortgage and refinance to a lower rate?
Calculate the penalty (contact your lender for the exact figure), compare it to the interest savings over your remaining term, and factor in any refinancing costs. If your net savings exceed CAD 5,000 to CAD 10,000, refinancing may make sense. If savings are marginal, the risk and hassle usually are not worth it.
Conclusion
Mortgage renewal in a high-rate environment demands active decision-making, not passive acceptance. By understanding your current position, comparing fixed and variable options thoughtfully, evaluating term lengths against your personal timeline, shopping aggressively among lenders, negotiating confidently with your current lender, and aligning your choice with your financial reality and risk tolerance, you can navigate this challenging landscape successfully.
Start your renewal process 120 days before your term ends, gather competing offers, and negotiate assertively. The difference between a passively accepted renewal and an actively managed one can save you tens of thousands of dollars over the life of your mortgage.
Important: This article provides general educational information about mortgage renewals in Canada and should not be considered personalized financial, lending, legal, or tax advice. Mortgage products, rates, qualification requirements, and provincial regulations vary significantly by lender, province, and individual circumstances. The OSFI mortgage stress test, prepayment privileges, and penalty calculations differ depending on your lender and the specific mortgage product. Rates and economic conditions change frequently. Before making any mortgage renewal decision, consult with a licensed mortgage broker or financial professional who can assess your personal situation, confirm current rates and terms, and provide advice tailored to your specific needs and location. This information is current as of October 2026.
Sources
- Mortgages (accessed )
- Key Interest Rate: Target for the Overnight Rate (accessed )
- Mortgages (accessed )
- Principles of Finance (accessed )
Related articles
How to Refinance Your Mortgage in Canada: When It Makes Sense
Learn when refinancing your Canadian mortgage makes sense, how it differs from renewal, and what costs to consider before breaking your term.
How to Negotiate Your Best Mortgage Renewal Rate in Canada (2026-2027)
Navigate the 2026-2027 mortgage renewal surge in Canada. Learn proven negotiation tactics to secure your best rate and save thousands on your term.
Renewing Your Mortgage in Canada: What to Expect in 2026
Learn what to expect when renewing your Canadian mortgage in 2026, including rate options, qualification rules, and how to prepare for the best terms.
