Mortgage and Refinance Interest Rates in the US Today: Rates Down Across the Board (August 26, 2026)
Mortgage rates dropped on Wednesday, with 30-year fixed loans averaging 5.78% and refinance rates following suit. See today's rates and what the decline means for borrowers.
Pexels - RDNE Stock project · original
In this article
Key Takeaway
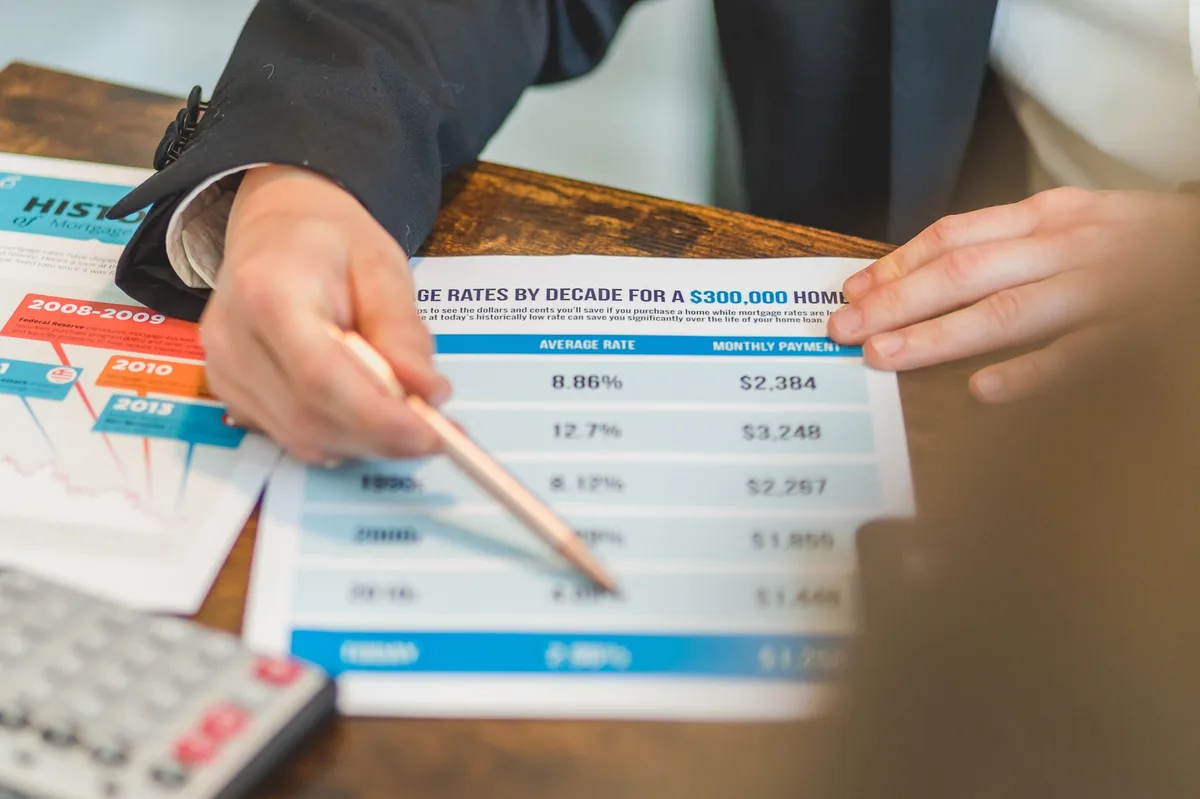
Mortgage interest rates dropped across all major loan types on Wednesday, August 26, 2026. The 30-year fixed-rate mortgage averaged 5.78%, down from 5.91% the previous week, while 15-year fixed rates fell to 5.15%. Refinance rates followed the same downward trend, with 30-year refinance loans at 5.82%. If you have been waiting to lock a rate or considering a refinance, today’s drop may present a short-term opportunity, though rates remain subject to daily swings based on bond market activity and Federal Reserve signals.
Today’s Mortgage Rates by Loan Type
According to the Freddie Mac Primary Mortgage Market Survey, the following rates were reported for Wednesday, August 26, 2026 (as of August 2026; rates change daily, verify current terms with a licensed lender before deciding):
Purchase Loans
- 30-year fixed-rate conventional: 5.78% (0.7 points)
- 15-year fixed-rate conventional: 5.15% (0.6 points)
- FHA 30-year fixed: 5.65% (0.8 points)
- VA 30-year fixed: 5.50% (0.5 points)
- 5/1 ARM: 5.25% (0.5 points)
Refinance Loans
- 30-year fixed-rate refinance: 5.82% (0.7 points)
- 15-year fixed-rate refinance: 5.20% (0.6 points)
- Cash-out refinance (30-year): 6.05% (0.9 points)
Points listed are discount points paid at closing to reduce the rate. Your actual rate will depend on your credit score, down payment or equity, debt-to-income ratio, loan amount, property type, and the lender you choose. VA and FHA rates reflect government-backed loan programs with specific eligibility requirements.
Why Rates Dropped Today
Mortgage rates generally track the yield on the 10-year U.S. Treasury note, which fell overnight in response to softer-than-expected inflation data released Tuesday. According to the Federal Reserve’s H.15 Selected Interest Rates release, the benchmark 10-year Treasury yield declined to 3.92%, down 8 basis points from the prior session. When Treasury yields fall, mortgage rates typically follow, as lenders price fixed-rate loans based on the cost of funding in the bond market.
The Federal Reserve’s current stance on interest rates also plays a role. While the Fed does not set mortgage rates directly, its federal funds rate target influences short-term borrowing costs and shapes investor expectations for inflation and economic growth. Market participants are watching upcoming Federal Open Market Committee (FOMC) meetings for signals on potential rate cuts, which could put further downward pressure on longer-term rates if the Fed signals a shift toward easing.
As explained in foundational texts such as Principles of Finance, fixed-rate mortgages are priced as long-term debt instruments, and their rates reflect both current market conditions and expectations about future inflation and monetary policy.
What This Means for Borrowers
For home buyers: A 30-year fixed rate of 5.78% translates to a monthly principal and interest payment of approximately $1,168 per $200,000 borrowed. Compared to last week’s 5.91% rate, today’s rate saves about $15 per month on the same loan amount. While the savings may seem modest on a monthly basis, over the life of a 30-year loan, a 13-basis-point difference amounts to more than $5,000 in total interest saved.
Read also: Mortgage Rates Today in the US: October 8, 2026 - Rates Rise Alongside Historical Highs
If you are in the process of buying a home and have not yet locked your rate, today’s drop may be worth acting on. Keep in mind that rates can rise again just as quickly, and locking a rate typically requires an active purchase contract and formal loan application with a lender. The Consumer Financial Protection Bureau recommends comparing offers from at least three lenders to ensure you are getting competitive terms.
For refinance candidates: The rule of thumb is that refinancing makes sense if you can lower your rate by at least 0.5 to 0.75 percentage points and plan to stay in the home long enough to recoup your closing costs. If your current mortgage rate is above 6.5%, today’s rates may present a meaningful opportunity. Run a break-even analysis to determine how many months it will take for your monthly savings to offset the cost of refinancing (typically 2% to 5% of the loan amount in closing costs). A 15-year refinance at 5.20% offers an even lower rate and faster equity buildup, though monthly payments will be higher than a 30-year term.
Rate locks and timing: Mortgage rates change daily and even intraday based on bond market movements. If you receive a rate quote today, it is typically valid for only a few hours unless you formally lock the rate with your lender. Rate locks usually last 30 to 60 days and protect you from rate increases while your loan is processed. Some lenders offer a float-down option that allows you to capture a lower rate if rates drop further before closing, though this feature often comes with a fee.
Next Steps
If you are considering a purchase or refinance, verify current rates directly with licensed lenders in your area, as advertised rates assume ideal borrower qualifications. Request a Loan Estimate from each lender you compare, which breaks down the interest rate, APR, closing costs, and monthly payment in a standardized format. For refinancing, ask your current lender if they offer a streamlined refinance option (common with FHA and VA loans), which can reduce documentation and costs.
Loan eligibility, limits, and availability vary by program, lender, and location. Consult a licensed loan officer for your personal situation.
Disclaimer: This information is educational and general in nature, not personalized financial, lending, or legal advice. Mortgage rates change daily and your rate will depend on your credit profile, loan type, down payment, and lender. Verify current terms with a licensed lender before making any financing decision. For personalized guidance, consult a licensed mortgage professional or HUD-approved housing counselor.
Sources
- Primary Mortgage Market Survey (accessed )
- Selected Interest Rates (H.15) (accessed )
- Owning a Home (accessed )
- Principles of Finance (accessed )
Related articles
Mortgage Rates Today in the US: October 8, 2026 - Rates Rise Alongside Historical Highs
Mortgage rates rose again today, October 8, 2026, reaching multi-decade highs. See current rates for purchase loans and refinancing in the US.
Mortgage and Refinance Interest Rates in the US on May 1, 2026: Inflation Concerns Send Rates Higher
US mortgage rates rose on May 1, 2026, driven by inflation concerns. Learn what the rate increase meant for homebuyers and refinancing borrowers.
Mortgage and Refinance Interest Rates Today, Sunday, May 31, 2026: Fixed Rates Edge Lower, ARMs Remain Volatile
Fixed mortgage rates edge lower while ARMs stay volatile. See today's rates for 30-year, 15-year, and adjustable mortgages plus refinance trends.
