Mortgage
Mortgage and Refinance Interest Rates Today in the US: October 27, 2026
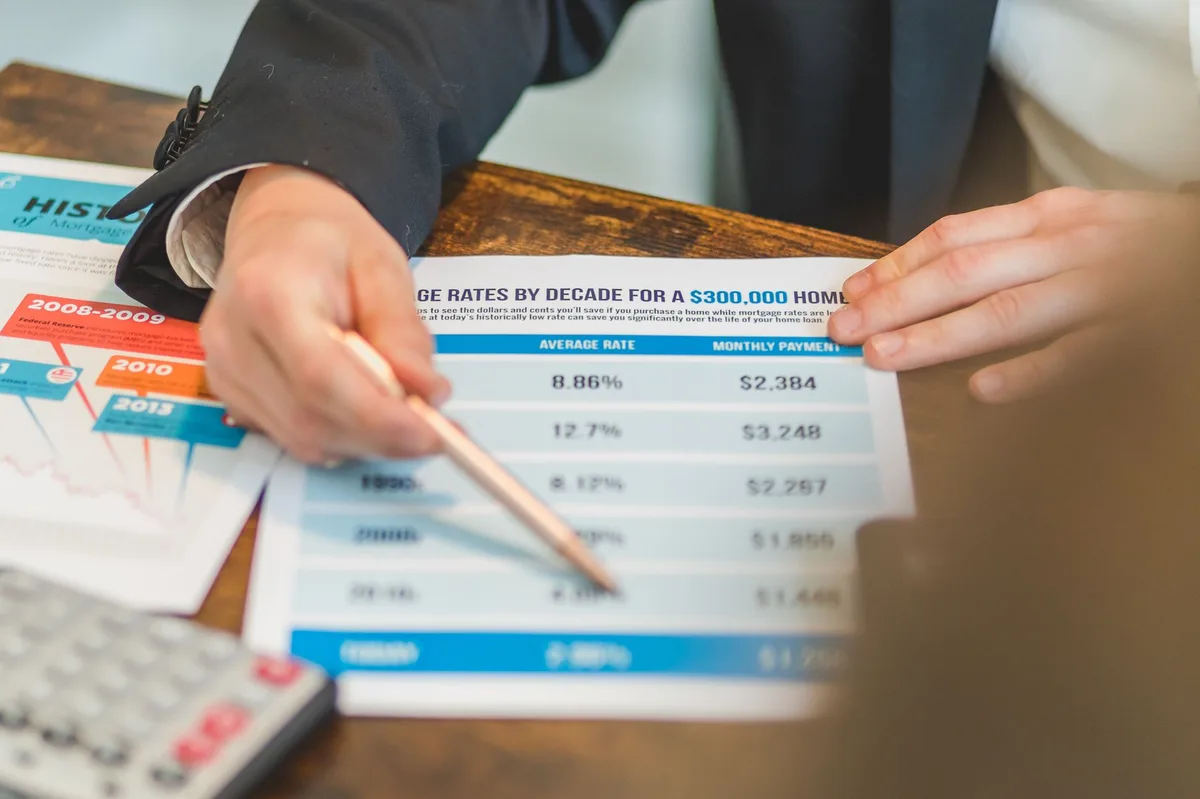
Mortgage rates climbed higher this week as markets digest recent economic data and Federal Reserve signals.
Author
Mortgage rate writer. Tracks Federal Reserve policy decisions, 10-year Treasury yields, and their downstream effect on 30-year fixed and adjustable mortgage rates for US buyers.
Mortgage rates climbed higher this week as markets digest recent economic data and Federal Reserve signals.
Purchase mortgage rates are running higher than refinance rates today, with the spread reflecting lender pricing strategies and market conditions heading into the final quarter of 2026.
A Trump administration executive order targeting mortgage insurance premiums and refinance closing costs could lower monthly payments and make it cheaper to refinance for eligible borrowers.
Mortgage rates remain elevated today even as bond market buying activity typically signals lower borrowing costs - what this disconnect means for homebuyers and refinancers.
Fixed-rate mortgage rates fell sharply this week while adjustable-rate mortgages remained unchanged, creating new opportunities for borrowers.
After six weeks of steady increases, mortgage rates pulled back slightly, offering a brief window for borrowers considering a home purchase or refinance.
Mortgage rates dropped on Wednesday, with 30-year fixed loans averaging 5.78% and refinance rates following suit. See today's rates and what the decline means for borrowers.
Learn how discount points work, calculate the break-even period, and decide whether buying down your mortgage rate makes financial sense.
Understand the key differences between fixed-rate and adjustable-rate mortgages to choose the right loan structure for your home purchase in the United States.
Compare refinancing scenarios to determine when the timing and cost savings justify replacing your current home loan.
Win your dream home this fall with strategic offers that stand out without overpaying - here is how to compete smart in the 2026 US market.
Forbearance temporarily pauses your mortgage payments during financial hardship, but interest continues to accrue and other homeownership costs remain your responsibility.
Lenders and the IRS classify second homes and investment properties differently, and those distinctions affect your down payment, interest rate, and tax deductions.
Escrow shortages happen when property taxes or insurance premiums increase more than your lender anticipated, forcing your monthly mortgage payment higher.
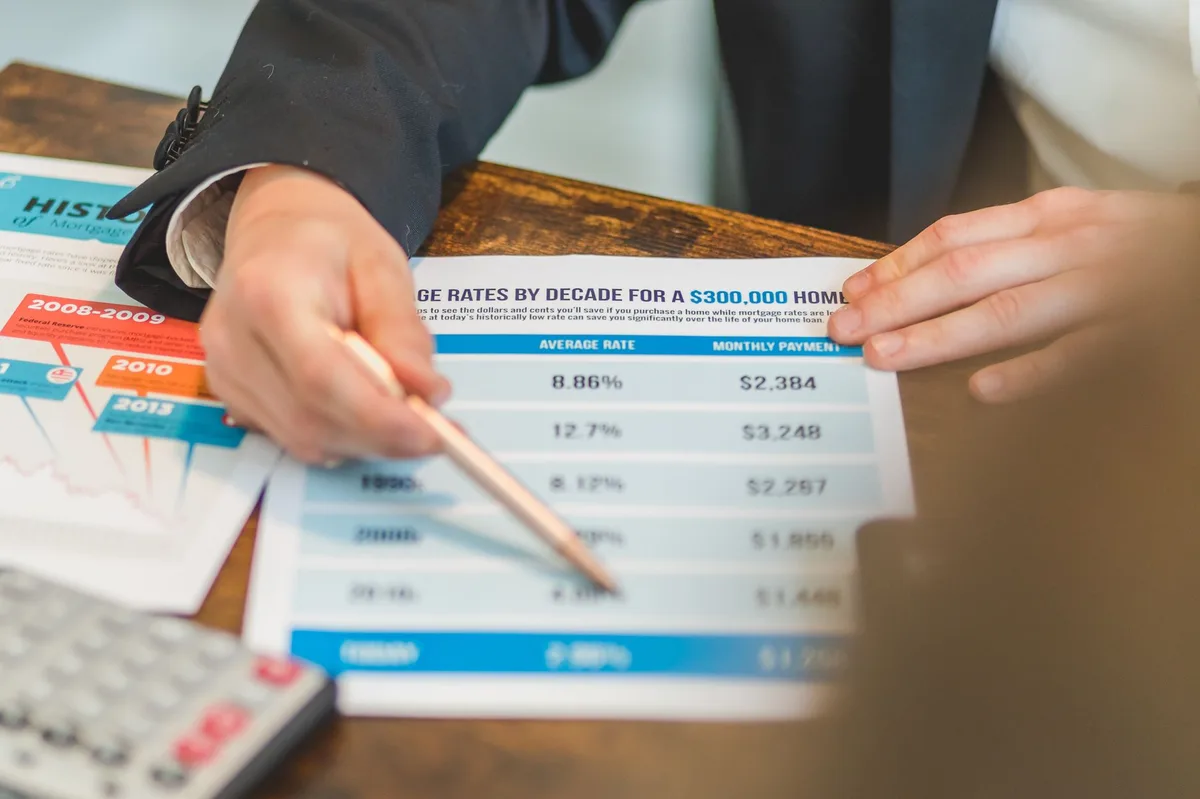
Learn whether to lock your mortgage rate now or wait until after the Federal Reserve's September meeting, and how FOMC decisions impact your rate strategy.
Learn the formulas for gross and net rental yield, understand what each number reveals about your investment property's performance, and see how to compare properties effectively.
Switching from monthly to bi-weekly mortgage payments accelerates payoff and cuts total interest by making one extra full payment per year through the calendar math of 26 half-payments instead of 12 full ones.
See exactly how much of each mortgage payment goes to principal versus interest over the life of your loan.
Compare HELOCs and cash-out refinancing to decide which option works best for tapping your home equity in today's market.
Understand the critical differences between mortgage pre-qualification and pre-approval, and learn what sellers prioritize when evaluating competing offers in today's US housing market.
USDA loans offer zero-down financing for eligible rural and suburban homebuyers with competitive rates and flexible credit requirements.
August presents unique opportunities and challenges for home buyers as families prioritize settling before school starts, often reducing competition and creating potential for better deals.
First-time buyers in the US typically choose between FHA loans (3.5% down, easier credit standards) and conventional mortgages (higher credit requirements, lower costs with 20% down). Your best option depends on your credit score, down payment savings, and how long you plan to stay in the home.
Mortgage rates remain elevated following the July 2026 FOMC meeting, with the Federal Reserve holding rates steady as inflation persists above target.
Learn the service, credit, and property requirements to qualify for a VA home loan in 2026.
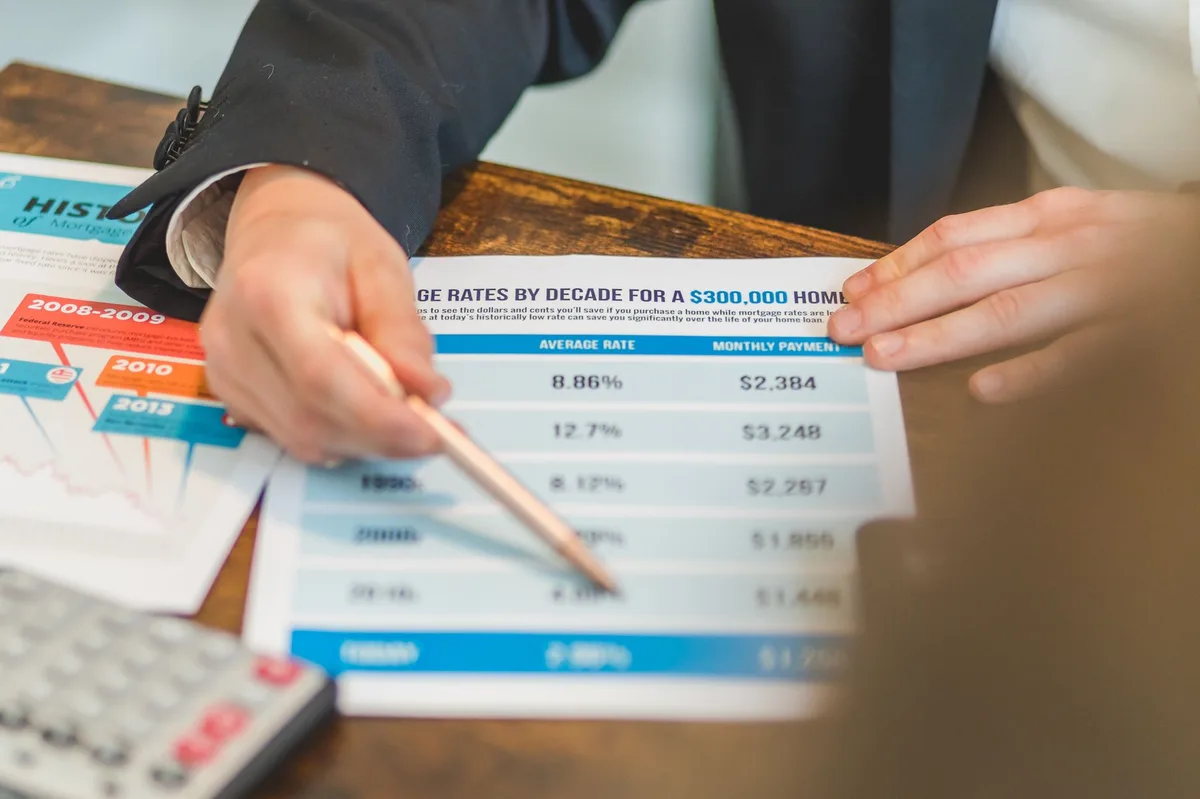
Refinancing your mortgage can save you thousands, but timing matters. Learn the five key scenarios when refinancing makes financial sense for US homeowners.
Learn who qualifies for a VA home loan in 2026, from service requirements to credit standards and how to get your Certificate of Eligibility.
When mortgage rates are elevated, choosing between a HELOC and a cash-out refinance requires careful analysis of rate structures, costs, and your existing mortgage terms.
Understanding the 2026 conforming loan limits helps you choose between conventional and jumbo financing and potentially save thousands on your mortgage.
A HELOC lets you borrow against your home equity with a revolving credit line, offering flexible access to funds for major expenses.
Choosing between a stable interest rate and a fluctuating one is a critical housing decision. Learn how fixed-rate and adjustable-rate mortgages work in the US to make an informed choice.
Learn how first-time home buyers can navigate the mortgage process in the US, from pre-approval through closing, with clear explanations of loan types, qualification requirements, and available programs.
VA loan eligibility starts with your service history, but approval also depends on the property, occupancy, credit, income, and lender underwriting. Here is the summer 2026 checklist veterans can use before shopping for a home.
Mortgage and refinance rates were slightly lower than earlier in the week, but affordability remains tight. Borrowers should compare APRs, points, and closing costs before locking.
Fed rate cuts do not automatically make mortgage rates fall. In 2026, buyers should watch Treasury yields, inflation, and lender quotes more closely than headlines alone.
US mortgage rates reversed recent declines today, with 30-year fixed rates climbing back above recent lows as bond markets react to stronger-than-expected economic data.
Fixed-rate mortgage rates in the United States have declined for the third consecutive week as of June 20, 2026, creating opportunities for both homebuyers and refinance candidates.
Fixed-rate mortgages decline modestly while adjustable-rate mortgages show continued volatility as markets digest recent Federal Reserve signals and economic data.
Learn how to choose between a fixed-rate mortgage and an adjustable-rate mortgage by evaluating your budget, timeline, and risk tolerance.
FHA loans accept credit scores as low as 500. Learn the exact qualification requirements, down payment rules, and steps to get approved even with challenged credit.
Learn how to refinance your mortgage with this complete guide covering credit checks, break-even calculations, rate shopping, and closing the deal.
Essential tax deductions and planning steps every property investor should review before filing to maximize savings and stay compliant with IRS rules.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.