Mortgage and Refinance Interest Rates Today in the US: October 27, 2026
Mortgage rates climbed higher this week as markets digest recent economic data and Federal Reserve signals.
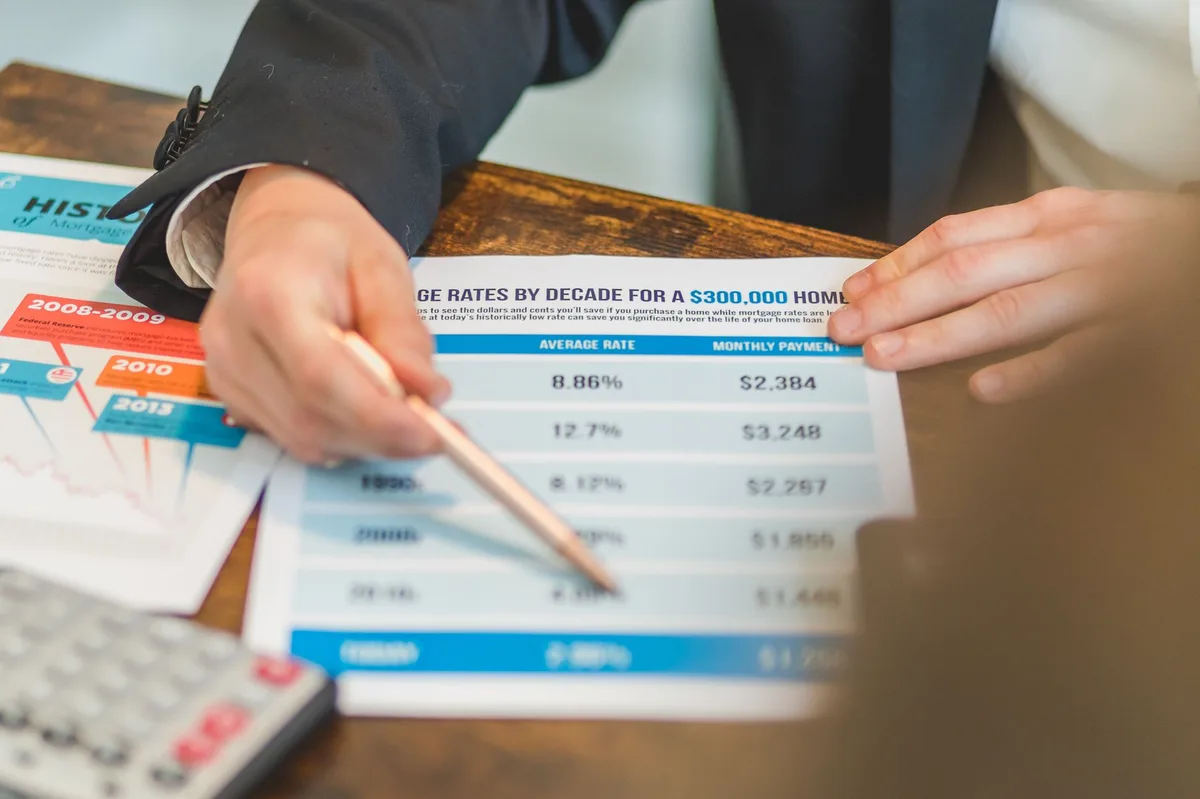
Pexels - RDNE Stock project · original
In this article
Key Takeaway
Mortgage rates moved higher on Tuesday, October 27, 2026, continuing an upward trend that began in mid-October. The average 30-year fixed-rate mortgage now sits near 6.89 percent, up from 6.72 percent the prior week, while 15-year fixed rates climbed to approximately 6.21 percent. This marks the fourth consecutive week of rate increases as bond markets react to stronger-than-expected economic data and Federal Reserve commentary signaling a cautious approach to future rate cuts.
Current Mortgage Rates for October 27, 2026
As of Tuesday, October 27, 2026, benchmark mortgage rates in the United States stand at the following levels, according to data tracked by Freddie Mac:
- 30-year fixed-rate mortgage: 6.89 percent (up 0.17 percentage points from last week)
- 15-year fixed-rate mortgage: 6.21 percent (up 0.14 percentage points)
- 5/1 adjustable-rate mortgage (ARM): 6.18 percent (up 0.09 percentage points)
These are average rates for borrowers with strong credit (typically a FICO score of 740 or higher), a debt-to-income ratio below 43 percent, and a down payment of at least 20 percent on a conventional loan. Your personal rate quote will depend on your credit profile, loan-to-value ratio, the lender, and whether you pay discount points to buy down the rate.
Rates change daily and can vary significantly between lenders. Verify current terms with a licensed mortgage lender before making any decision.
Why Rates Are Rising Again
Mortgage rates have climbed steadily since mid-October as financial markets digest recent signals from the Federal Reserve and incoming economic data. The primary drivers behind the current upward trend include:
Federal Reserve policy stance. The Fed has maintained its federal funds rate target in a restrictive range to keep inflation pressures in check. Recent commentary from Federal Open Market Committee (FOMC) members suggests the central bank is in no rush to lower rates further, keeping upward pressure on longer-term borrowing costs. As covered in foundational texts such as Principles of Finance, mortgage rates tend to track the yield on the 10-year U.S. Treasury note, which moves in response to expectations about Fed policy and inflation (OpenStax, 2022).
Stronger economic data. September and early October employment and retail sales figures came in above forecasts, indicating continued economic resilience. While good news for the broader economy, strong data reduces the urgency for rate cuts and can push Treasury yields higher, pulling mortgage rates along with them.
Bond market volatility. The yield on the 10-year Treasury note has risen roughly 35 basis points over the past three weeks, reflecting investor concerns about persistent inflation and the path of federal deficits. Mortgage rates typically move in tandem with this benchmark, and the recent spike has translated directly into higher borrowing costs for homebuyers and those refinancing.
According to the Federal Reserve, these dynamics are likely to keep rates elevated in the near term unless inflation cools more decisively or economic growth slows sharply.
Read also: Mortgage Rates Today in the US: June 4, 2026 Update
What Borrowers Should Consider
If you are shopping for a mortgage or considering a refinance, the current rate environment calls for a few strategic steps:
Lock your rate promptly if you are buying. Mortgage rate locks typically last 30 to 60 days. If you are under contract on a home and rates continue to climb, locking sooner rather than later can protect you from further increases before closing. Ask your lender about the cost of extending the lock if your closing date shifts.
Reevaluate refinance timing. A cash-out refinance or rate-and-term refinance makes sense only if the new rate is low enough to justify closing costs. Calculate your break-even point (the time it takes for monthly savings to offset the upfront fees). If rates have risen since you last checked, you may want to wait for a pullback before refinancing. The Consumer Financial Protection Bureau provides tools to compare refinance scenarios and estimate costs.
Consider discount points carefully. Paying points (each point equals 1 percent of the loan amount) can lower your interest rate, but only if you plan to stay in the home long enough to recoup the upfront cost through lower monthly payments. In a rising-rate environment, points can make sense for long-term owners, but less so if you expect to move or refinance within a few years.
Shop multiple lenders. Rate quotes can vary by 0.25 to 0.50 percentage points or more between lenders on the same day. Compare offers from at least three lenders, including credit unions and online lenders, and review both the interest rate and the annual percentage rate (APR), which includes fees.
Next Steps
If you are in the market for a mortgage or refinance, request personalized rate quotes from licensed lenders as soon as possible. Rates can shift daily, and your individual terms will depend on your credit score, loan amount, down payment, and the lender’s pricing. A HUD-approved housing counselor can also provide guidance if you are uncertain about loan programs or qualification requirements.
Financial Disclaimer: This article provides educational information only and is not personalized financial, lending, or legal advice. Mortgage rates change daily and eligibility varies by program, lender, location, and individual financial profile. Consult a licensed mortgage lender or housing counselor for guidance specific to your situation.
Sources
- Selected Interest Rates (Daily) - H.15 (accessed )
- Freddie Mac Research and Insights (accessed )
- Consumer Tools: Mortgages (accessed )
- Principles of Finance (accessed )
Related articles
Mortgage Rates Today in the US: June 4, 2026 Update
US mortgage rates stayed near 6.5% on June 4, 2026. See what that means for purchase loans, refinance decisions, and rate locks.
Mortgage and Refinance Interest Rates Today, Sunday, May 31, 2026: Fixed Rates Edge Lower, ARMs Remain Volatile
Fixed mortgage rates edge lower while ARMs stay volatile. See today's rates for 30-year, 15-year, and adjustable mortgages plus refinance trends.
What the October 2026 FOMC Decision Means for Mortgage Rates in the US
The FOMC met October 27-28, 2026. Learn how Federal Reserve decisions affect mortgage rates and what US homebuyers should do now.
