When to Lock Versus Float Your Mortgage Rate Before the September FOMC Meeting in the US
Learn whether to lock your mortgage rate now or wait until after the Federal Reserve's September meeting, and how FOMC decisions impact your rate strategy.
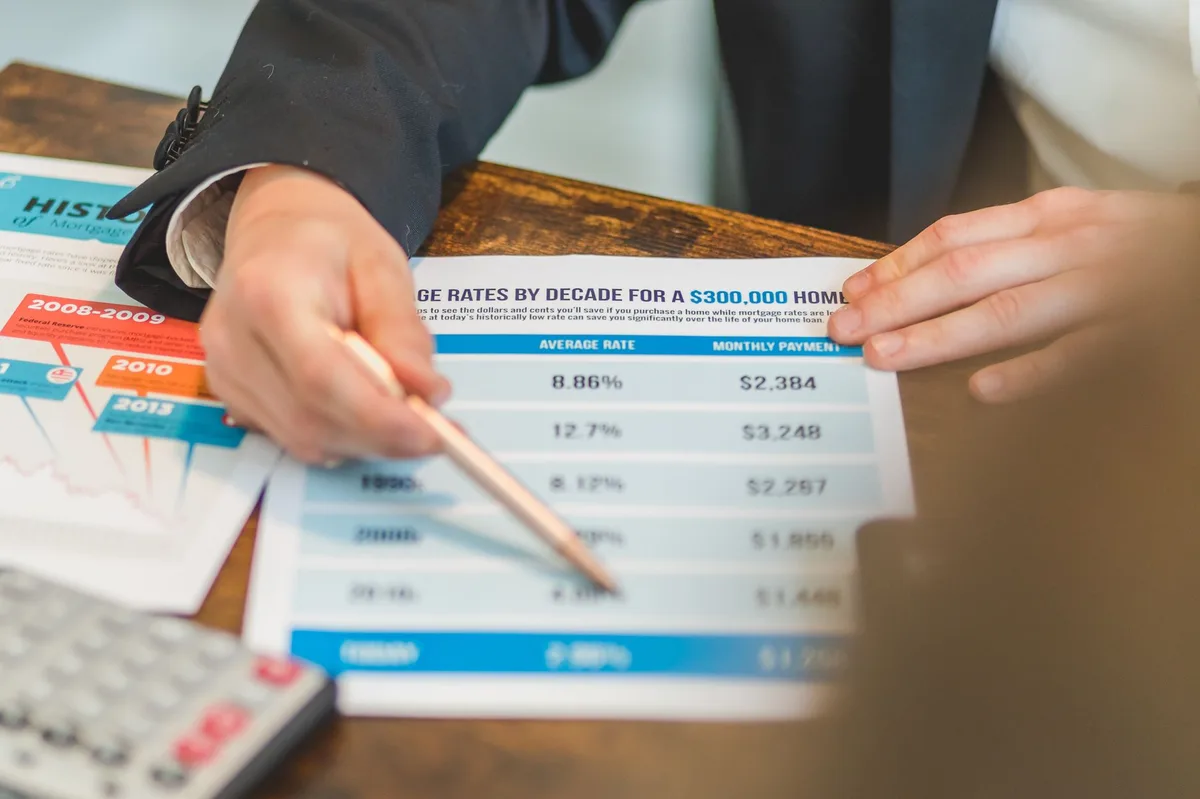
Pexels - Arturo Añez. · original
In this article
Key Takeaway
If the Federal Reserve is widely expected to cut rates at the September FOMC meeting and mortgage rates have already dropped in anticipation, locking before the meeting often makes sense because the market has priced in the cut. If the Fed’s decision is uncertain or inflation data suggests rates could move higher, floating until after the announcement may offer a better rate, but you accept the risk of rates rising instead.
How FOMC Meetings Affect Mortgage Rates
The Federal Open Market Committee (FOMC) meets eight times per year to set the federal funds rate, which influences short-term borrowing costs across the economy. While the Fed does not directly control mortgage rates, its policy decisions signal the direction of monetary policy and impact investor expectations for long-term interest rates, including the 10-year Treasury yield that mortgage rates track closely (Federal Reserve, 2026).
Mortgage markets typically react to FOMC guidance weeks before the actual meeting. If the Fed has signaled a rate cut and inflation data supports that outlook, mortgage rates often decline in advance as lenders price in the expected change. By the time the FOMC announces the decision, much of the rate movement has already occurred.
When to Lock Before the September FOMC Meeting
Lock your rate before the September FOMC meeting if mortgage rates have already fallen and market consensus expects a rate cut. Once the market prices in a policy change, locking protects you from any post-announcement volatility or unexpected statements from the Fed that could push rates back up.
Lock if you are within 30 to 45 days of closing and have found a rate you can afford. Rate locks typically last 30, 45, or 60 days, and extending a lock can cost additional fees. If your closing date aligns with the FOMC meeting window, locking earlier eliminates the risk of rates rising while you wait for the announcement (Consumer Financial Protection Bureau, 2026).
Lock if recent inflation reports or employment data suggest the Fed may hold rates steady or signal caution about future cuts. If the economic data is mixed, the FOMC may adopt a wait-and-see approach, which can cause rates to drift higher.
When to Float Until After the FOMC Meeting
Float your rate if the Fed’s decision is uncertain and there is a realistic chance of a larger-than-expected rate cut. If inflation has cooled faster than anticipated or the Fed’s prior statements hint at more aggressive easing, waiting until after the announcement could result in a lower rate.
Read also: How Federal Reserve Rate Changes Affect Mortgage Rates in the US
Float if you have more than 60 days until closing and can afford to wait. Floating gives you flexibility to lock after the FOMC decision if rates drop, but you must be prepared to lock immediately if rates move against you. Most lenders allow you to lock at any point during your loan process, but some charge higher fees for locks requested close to closing.
Float if you are refinancing rather than purchasing. Refinance borrowers often have more time flexibility than purchase borrowers and can wait out short-term volatility. If rates rise after the FOMC meeting, you can delay the refinance without losing a home purchase contract.
Balancing Risk and Timing
As covered in foundational texts such as Principles of Finance, interest rate risk is the possibility that rates will move unfavorably between the time you apply for a loan and the time you close. Locking eliminates that risk but costs you the opportunity to capture a lower rate if the market drops. Floating keeps your options open but exposes you to the risk of higher rates.
According to Freddie Mac’s historical rate data, mortgage rates can swing 0.25 to 0.50 percentage points in the days following an FOMC announcement, depending on how the decision compares to market expectations (Freddie Mac, 2026). A quarter-point rate increase on a 400,000 dollar mortgage adds roughly 60 dollars to your monthly payment and more than 20,000 dollars in total interest over 30 years.
Next Step
Discuss your rate lock options with your loan officer before the FOMC meeting. Ask whether your lender offers a float-down option (which lets you lock now and capture a lower rate later if rates drop before closing) and what the cost and eligibility requirements are. Confirm your lock expiration date and any extension fees so you can time your decision around the Fed’s announcement.
Financial Disclaimer: This article provides general educational information about mortgage rate lock strategy and Federal Reserve policy. It is not personalized financial, lending, or legal advice. Mortgage rates change daily and vary by lender, loan type, credit profile, and location. FOMC decisions and their impact on mortgage rates are subject to market conditions and cannot be predicted with certainty. Consult a licensed mortgage lender or financial advisor for guidance specific to your situation. Rate lock terms, fees, and availability vary by lender and loan program; confirm all details with your lender before making a decision.
Sources
- Owning a Home (accessed )
- Selected Interest Rates (H.15) (accessed )
- Research and Insights (accessed )
- Principles of Finance (accessed )
Related articles
Should You Lock Your Mortgage Rate Now After the FOMC September Decision in the US
The Fed's September FOMC decision impacts mortgage rates. Learn whether you should lock your rate now or wait, with expert guidance for US borrowers.
FOMC October 27-28 Decision: What It Means for Mortgage Rates in the US
How the Federal Reserve's October 27-28 FOMC decision affects US mortgage rates, what borrowers should watch, and timing considerations for locks.
Mortgage Rates Today in the US: October 8, 2026 - Rates Rise Alongside Historical Highs
Mortgage rates rose again today, October 8, 2026, reaching multi-decade highs. See current rates for purchase loans and refinancing in the US.
