Mortgage and Refinance Interest Rates Today in the US: October 17, 2026
Refinance rates declined across most loan types today, while purchase mortgage rates showed mixed movement. See current rates and what they mean for borrowers.
Pexels - RDNE Stock project · original
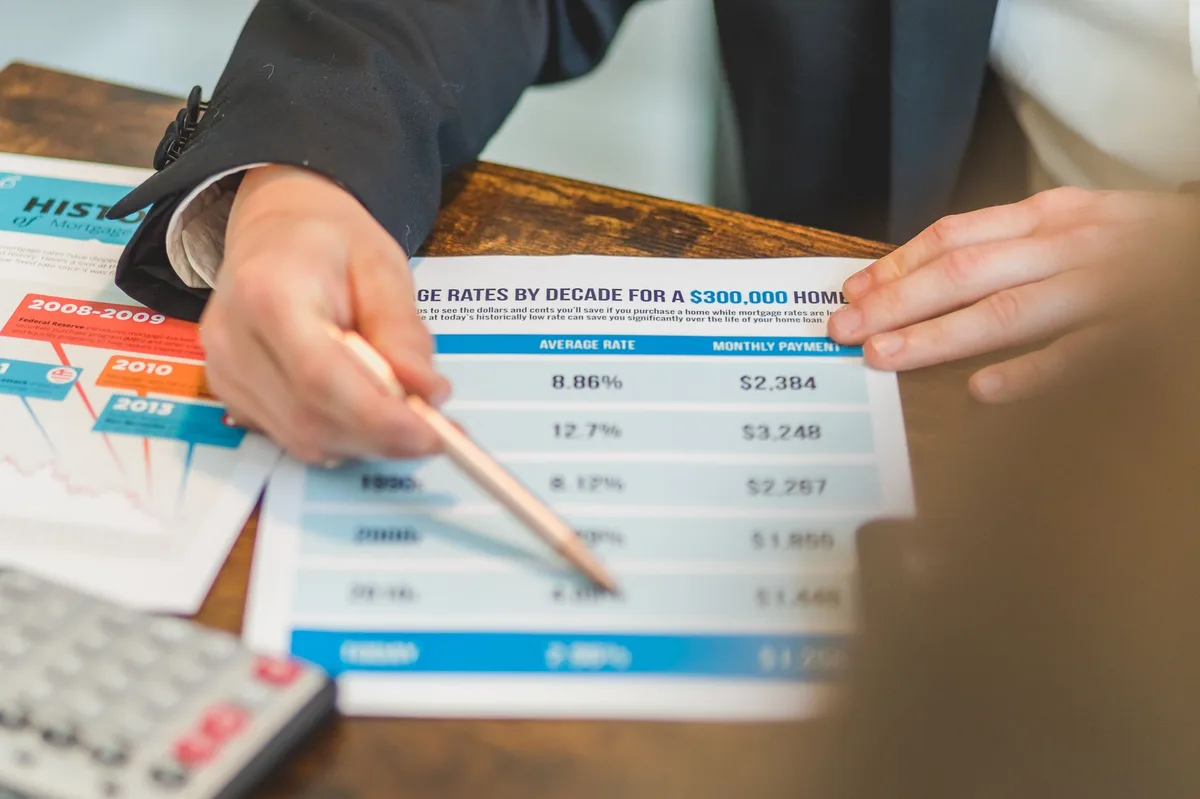
Refinance rates moved lower across most loan types today, Saturday, October 17, 2026, while purchase mortgage rates showed mixed movement. The 30-year fixed refinance rate dropped to 6.42 percent, down from 6.51 percent yesterday, and the 15-year fixed refinance rate fell to 5.68 percent from 5.75 percent. Purchase rates held steadier, with the 30-year fixed purchase rate at 6.48 percent and the 15-year at 5.71 percent.
Current Purchase Mortgage Rates
The benchmark 30-year fixed-rate mortgage for home purchases stands at 6.48 percent as of this morning, essentially unchanged from yesterday’s 6.49 percent. The 15-year fixed purchase rate sits at 5.71 percent, down slightly from 5.73 percent. Adjustable-rate mortgages (5/1 ARMs) for purchase are averaging 6.12 percent, according to the latest data from Freddie Mac.
These rates apply to conventional conforming loans (loan amounts up to $766,550 in most US counties for 2026) and assume a borrower with a credit score of 740 or higher, a loan-to-value ratio of 80 percent, and a 20 percent down payment. Actual rates vary by lender, loan amount, credit profile, property location, and whether you pay discount points at closing.
Current Refinance Rates
Refinance rates declined more noticeably today. The 30-year fixed refinance rate dropped to 6.42 percent, representing a savings of about 9 basis points compared to yesterday. The 15-year fixed refinance rate fell to 5.68 percent. Homeowners with existing mortgages above 7 percent may find today’s rates worth exploring, particularly for rate-and-term refinancing to lower monthly payments.
As covered in Principles of Finance, mortgage interest rates respond to movements in the broader bond market, particularly the 10-year Treasury yield, which influences long-term borrowing costs across the economy. Recent Federal Reserve policy adjustments and inflation data continue to drive rate volatility.
What This Means for Borrowers
If you are shopping for a purchase mortgage, rates remain elevated compared to the 3 to 4 percent environment of 2020 to 2021, but have stabilized compared to the sharper increases seen in 2022 and 2023. Locking your rate protects you from further increases during your closing period, typically 30 to 60 days. According to the Consumer Financial Protection Bureau, a rate lock agreement should specify the locked rate, the lock period, and any fees.
For refinancing, calculate your break-even point before proceeding. Divide your total closing costs (typically 2 to 5 percent of the loan amount) by your monthly savings to see how many months it takes to recover the cost. If you plan to stay in the home longer than the break-even period and your current rate is at least 0.5 to 0.75 percentage points higher than today’s rates, refinancing may save money over the loan’s life.
Rates change daily based on economic data, Federal Reserve policy, and market conditions tracked by the Federal Reserve’s H.15 release. Verify current rates directly with licensed lenders, as published averages represent snapshots and individual quotes depend on your specific financial profile, property type, and loan structure.
This information is educational and general in nature. Mortgage rates as of October 17, 2026; rates change daily and vary by lender, loan type, credit score, down payment, property location, and discount points paid at closing. Consult a licensed mortgage lender or broker for personalized rate quotes and to confirm eligibility for specific loan programs based on your financial situation.
Sources
- Primary Mortgage Market Survey (accessed )
- Selected Interest Rates (Daily) - H.15 (accessed )
- Consumer Tools for Mortgages (accessed )
- Principles of Finance (accessed )
Related articles
Mortgage and Refinance Interest Rates Today, Sunday, May 31, 2026: Fixed Rates Edge Lower, ARMs Remain Volatile
Fixed mortgage rates edge lower while ARMs stay volatile. See today's rates for 30-year, 15-year, and adjustable mortgages plus refinance trends.
Mortgage Rates Update for the US: Mixed Movement on Friday Heading into the Weekend (October 23, 2026)
Mortgage rates in the US showed mixed movement on Friday, October 23, 2026. See current rates for purchase loans and refinancing.
Mortgage Rates Hold Steady at 7.4% in the US: October 2026 Update
Mortgage rates held steady at 7.4% this week. See current rates for 30-year fixed, 15-year, ARMs, and refinance loans in the US market.
