Mortgage
How Escrow Accounts Work on US Mortgages: Required vs Optional
Compare lender-managed escrow accounts with self-managing your property taxes and insurance to decide which option fits your mortgage situation.
Author
Writes about US residential lending. Breaks down rates, points, escrow, and loan types (conventional, FHA, VA) so buyers and homeowners can decide with confidence.
Compare lender-managed escrow accounts with self-managing your property taxes and insurance to decide which option fits your mortgage situation.
VA home loans offer veterans and active service members zero down payment, no PMI, and competitive rates. Learn the key benefits, eligibility rules, and costs.
In a competitive fall housing market, buyers need smart strategies to stand out. Learn proven tactics to strengthen your offer and beat other buyers.
When your adjustable-rate mortgage reset approaches, refinancing to a fixed rate often makes sense if the new rate will be significantly higher and you plan to stay in the home long enough to recover closing costs.
The Federal Reserve's September decision affects mortgage timing. Here's what borrowers need to know about locking rates now.
The Federal Reserve's September FOMC meeting drives mortgage rate expectations. Here's what the decision means for home financing in the coming months.
Understanding the conforming loan limit and how crossing it changes your mortgage requirements, rates, and qualification standards.
FHA loans allow credit scores as low as 500, but most lenders require 580 or higher. Compare FHA, conventional, and credit-improvement paths to find the right approach for buying with imperfect credit.
Learn the two ways to eliminate private mortgage insurance on a conventional loan in the United States, plus the equity milestones and timing rules you need to know.
When using gift money for a down payment, lenders require a signed gift letter and a complete paper trail documenting the transfer from donor to buyer.
Learn how switching to bi-weekly mortgage payments can help you pay off your home loan years ahead of schedule and save thousands in interest.
A mortgage comparison calculator reveals how term length affects your monthly payment and total interest cost, helping you choose the right loan for your budget and goals.
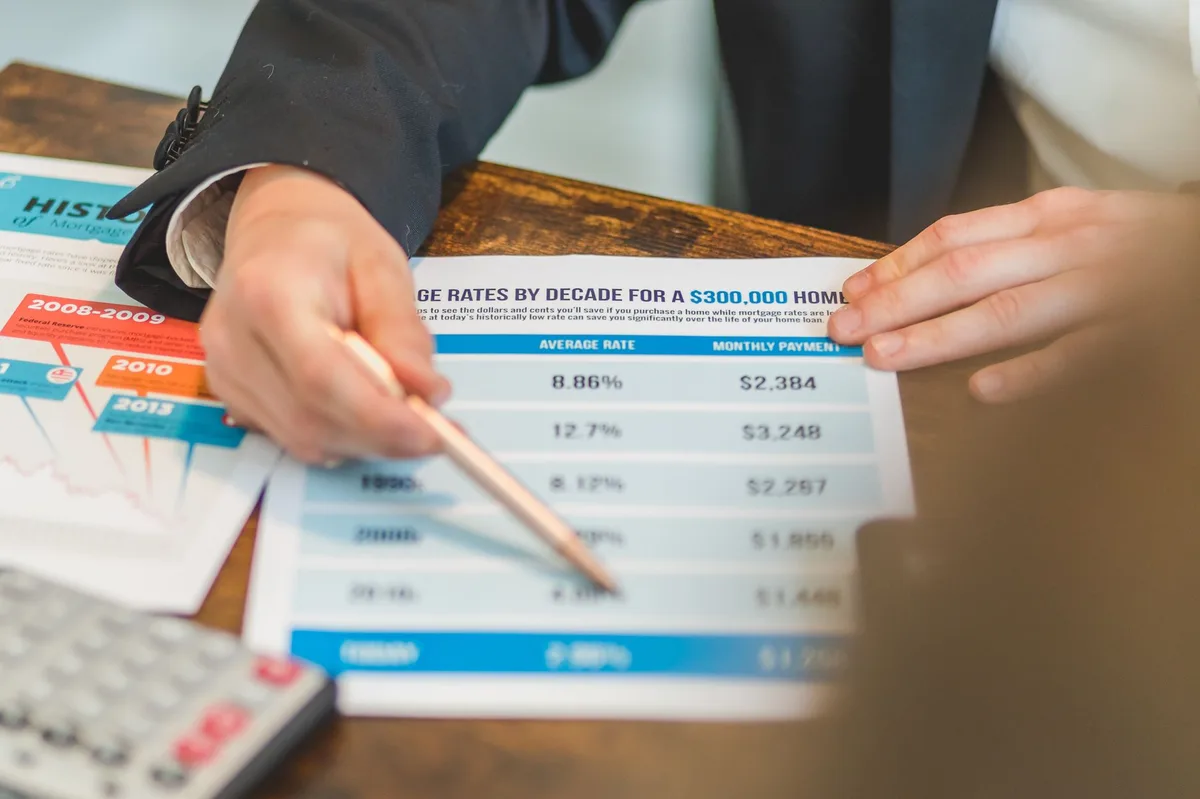
Understand how adjustable-rate mortgage payments change at adjustment and calculate your new payment amount.
Learn how to calculate your home equity, understand what drives it, and see why this number matters for refinancing, borrowing, and building wealth.
A bridge loan is a short-term financing solution that lets you buy a new home before your current home sells, using your existing equity as collateral.
When mortgage rates are elevated, deciding between a HELOC and cash-out refinance requires careful analysis of costs, flexibility, and your financial timeline.
Deciding how to tap your home equity? Learn the key differences between a cash-out refinance and a home equity loan in the US.
A steady Federal Reserve does not make an adjustable-rate mortgage risk-free. ARM borrowers still need to watch reset dates, indexes, margins, caps, and refinance timing.
Most US homeowners should not refinance solely because of the July FOMC meeting. Compare today's lender quotes against your break-even point, loan timeline, and fall rate risk before deciding.
A Federal Reserve rate cut can help some borrowing costs, but mortgage rates do not move in lockstep with the Fed's policy rate. Here is why home loan rates may stay high even after the Fed cuts.
Debt-to-income ratio helps estimate how much mortgage payment may fit your budget. This calculator shows how income, debts, taxes, insurance, and loan assumptions work together.
Purchase and refinance mortgage rates are tracking closely together as of Monday, June 8, 2026, offering similar terms for both homebuyers and existing homeowners.
Learn the essential questions to ask mortgage lenders and how to compare loan offers to find the best terms for your home purchase.
Current mortgage and refinance rates show mixed trends as of late June 2026, with some loan products seeing slight increases while others edge lower.
Mortgage rates fell to multi-month lows this week as diplomatic progress in Iran eased geopolitical risk and sent investors toward US Treasury bonds, lowering borrowing costs for homebuyers and those refinancing.
Learn when and how to lock your mortgage rate if you are buying a home this summer with an August closing date.
Understanding how the Federal Reserve's June 16-17, 2026 policy decision impacts mortgage refinancing opportunities and timing strategies for homeowners.
Compare HELOC and cash-out refinance options to tap your home equity in 2027, and learn which strategy fits your financial goals and risk tolerance.

Learn the key factors that determine whether refinancing your mortgage is the right financial move, including break-even analysis, rate comparisons, and timing considerations.
A clear comparison of FHA and conventional loans, including down payments, credit requirements, mortgage insurance, and which fits first-time buyers.
Understand discount points and origination points, how buying points lowers your rate, and how to know if paying for points is worth it.
Learn how to decide whether a mortgage refinance is worth it, how to calculate your break-even point, and which refinance type fits your goals.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.