Mortgage Points Strategy in a Falling Rate Environment in the US
When mortgage rates are trending downward, buying discount points often works against you - learn when to skip them and when they might still make sense.
Pexels - RDNE Stock project · original
In this article
Key takeaway: When mortgage rates are falling, buying discount points is usually a poor strategy. You pay upfront to lock in a lower rate, but if rates continue to drop, you can refinance to an even better rate without having paid those points. The money you spend on points may never be recovered, especially if you refinance or sell within a few years. In a declining rate environment, skip the points and keep your cash for closing costs or future refinancing fees.
What Mortgage Points Are
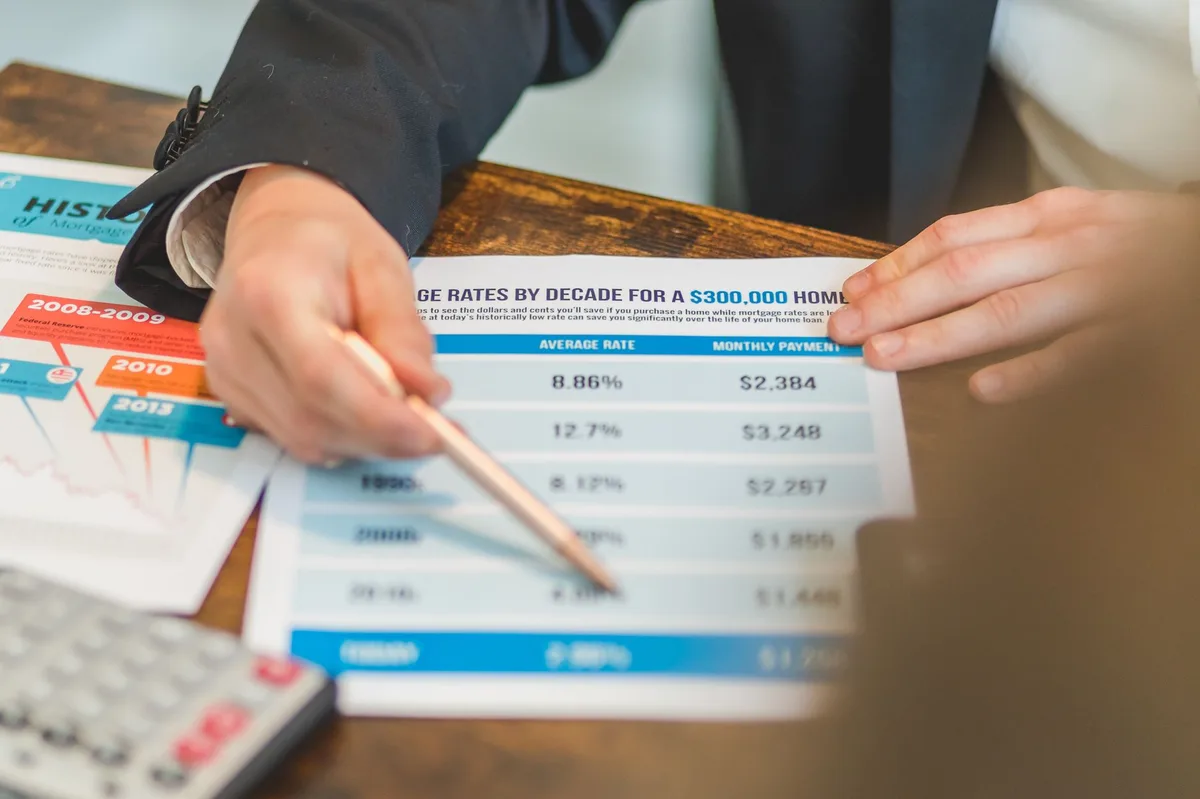
Mortgage discount points are an upfront fee you pay at closing to buy down your interest rate. One point costs 1% of your loan amount and typically reduces your rate by about 0.25%. On a $300,000 loan, one point costs $3,000. According to the Consumer Financial Protection Bureau, points are paid at closing and immediately lower your monthly payment (CFPB, 2026).
The concept of using upfront payments to reduce borrowing costs is covered in foundational finance texts such as Principles of Finance, which explains how present-value calculations determine whether prepaying interest makes economic sense.
Why Falling Rates Change the Calculation
Buying points locks in a rate reduction for the life of your loan. That commitment makes sense when rates are stable or rising, but works against you when rates are falling.
If you pay $3,000 for a 0.25% rate reduction today and rates drop another 0.5% within a year, you will likely refinance to capture the lower market rate. When you refinance, you get a new loan with new terms, and the points you paid on the old loan do not transfer. You spent $3,000 to save perhaps $40 per month, but you only kept that loan for 12 months. You paid $3,000 to save $480, a net loss of $2,520.
According to Federal Reserve data on mortgage rate trends, rate environments shift based on monetary policy, inflation expectations, and economic conditions (Federal Reserve, 2026). When the Federal Reserve signals rate cuts or inflation moderates, mortgage rates typically follow downward. In such periods, locking in a rate with points means betting rates will not fall further. History shows that bet often loses.
When Points Might Still Make Sense
Even in a falling rate environment, a few scenarios justify buying points:
You plan to stay in the home for many years. If you intend to keep the loan for 10 to 15 years regardless of rate movements, the cumulative monthly savings can exceed the upfront cost. Calculate your break-even point: divide the cost of points by the monthly savings. If you will own the home well past that break-even date and do not plan to refinance, points may work.
Read also: How Mortgage Points Work in the United States
Rates have already fallen significantly and are stabilizing. If rates dropped from 7% to 5% and economic forecasts suggest they will hold near current levels, buying points to lock in a 4.75% rate carries less refinance risk. Verify current rate forecasts with a licensed lender before deciding.
You have extra cash and no better use for it. Points are a guaranteed return equal to the interest saved. If your alternative is leaving the money in a low-yield savings account, buying points may offer a better effective return over the loan’s life, even with some refinance risk.
When to Skip Points
Avoid points if you expect to refinance within three to five years, if you plan to sell the home soon, or if you need that cash for an emergency fund or home repairs. Closing costs (including points) are paid upfront and are not recoverable if you refinance or sell early. According to Fannie Mae’s research on borrower behavior, many homeowners refinance or move within seven years, making long break-even periods risky (Fannie Mae, 2026).
Also skip points if the rate environment shows signs of continued decline. Watch Federal Reserve announcements, inflation data, and mortgage rate forecasts. If the consensus is that rates will fall another 0.5% to 1% within the next year, paying for a small rate reduction today is likely wasted money.
Next Step
Before deciding, ask your lender for a break-even analysis showing how many months it takes for the monthly savings to offset the cost of points. Compare that to how long you realistically expect to keep the loan. If the break-even period exceeds your likely hold time, skip the points and keep your cash. If rates do fall, you can refinance without having prepaid for a rate you no longer have.
Financial Disclaimer: This article provides general educational information about mortgage points and rate strategy in the United States. It is not personalized financial or lending advice. Mortgage rates change daily, loan terms vary by lender and program, and individual circumstances differ. Consult a licensed mortgage lender or HUD-approved housing counselor to evaluate whether buying discount points fits your specific financial situation, loan type, and timeline. Rate forecasts are not guarantees, and refinancing involves closing costs and qualification requirements that may change.
Sources
- Consumer Tools: Mortgages (accessed )
- Research and Insights (accessed )
- Selected Interest Rates (H.15) (accessed )
- Principles of Finance (accessed )
Related articles
How Mortgage Points Work in the United States
Discover how mortgage points work in the US, when buying points saves money, and how to calculate your break-even point on discount points.
Understanding Mortgage Points and Whether to Buy Them Down in the US
Calculate whether buying mortgage discount points saves money. Understand the break-even period and true cost of buying down your rate.
Understanding Mortgage Points and Whether to Buy Them Down in the US
Mortgage points let you pay upfront to lower your interest rate. Learn how they work and whether buying them down makes sense for your situation.
