The Impact of Rising Interest Rates on Mortgage Borrowing in the US
Rising interest rates reduce borrowing power by increasing monthly payments and tightening debt-to-income ratios, pushing many qualified buyers below approval thresholds.
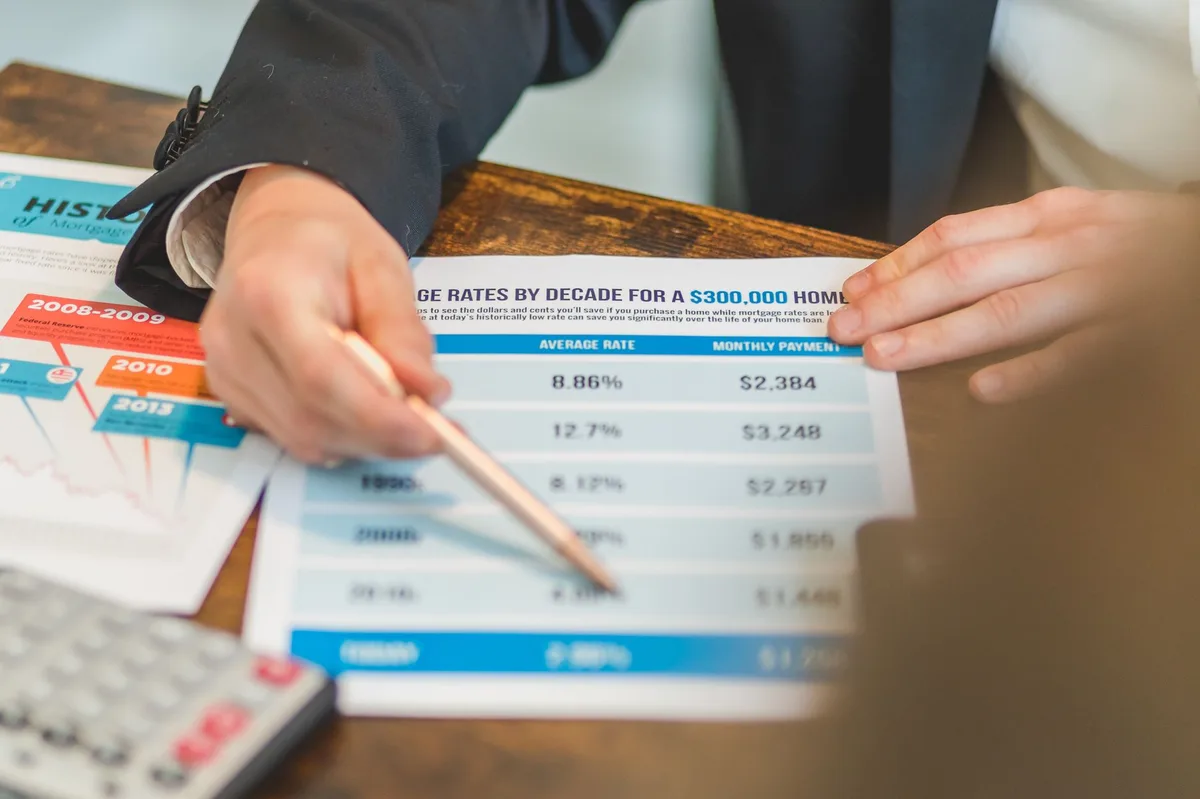
Pexels - RDNE Stock project · original
In this article
When interest rates climb, the monthly payment on the same loan amount rises substantially. A borrower who qualified for a $400,000 mortgage at 3.5 percent may fail to meet debt-to-income requirements at 6.5 percent, even with identical income and credit. Rising rates effectively shrink purchasing power, push marginal applicants below approval thresholds, and force many to revise home-buying budgets downward or delay purchases altogether.
What “Failing the Threshold” Means
Mortgage lenders evaluate borrowers using debt-to-income (DTI) ratios, which compare total monthly debt payments to gross monthly income. Conventional loans typically require a back-end DTI of 43 percent or lower, while FHA loans allow up to 50 percent in some cases. When interest rates rise, the monthly principal-and-interest payment on a given loan amount increases, consuming a larger share of the borrower’s income and pushing the DTI ratio higher.
A borrower with a gross monthly income of $8,000 and existing monthly debts of $600 (car loan, student loan, credit cards) can allocate roughly $2,840 to total monthly debt under a 43 percent conventional DTI cap. If the maximum housing payment (principal, interest, taxes, insurance, and HOA fees) is $2,240 after accounting for the $600 in existing obligations, a 3.5 percent rate on a 30-year fixed mortgage supports a loan amount of approximately $400,000. At 6.5 percent, the same $2,240 housing payment supports only about $280,000, a reduction of $120,000 in borrowing capacity.
This dynamic is what “failing the threshold” describes: a borrower who met DTI requirements at lower rates no longer qualifies for the same loan amount when rates rise, even though income, credit score, and down payment remain unchanged.
How Rising Rates Tighten Borrowing Capacity
According to foundational finance principles covered in Principles of Finance, interest rates directly influence the present value of future cash flows and the cost of borrowing. In mortgage lending, higher rates mean higher monthly payments for the same principal, which translates to reduced affordability.
The mechanics are straightforward. A $300,000 loan at 3.5 percent carries a monthly principal-and-interest payment of approximately $1,347. The same loan at 6.5 percent costs roughly $1,896 per month, an increase of $549. For a borrower near the DTI limit, that additional $549 can push total monthly obligations above the 43 percent threshold, disqualifying the application.
Rate increases also affect adjustable-rate mortgages (ARMs). Borrowers who qualified for an ARM at an initial rate of 3 percent may face payment shock when the rate adjusts upward after the fixed period ends. If the new rate exceeds the borrower’s capacity to service the debt under existing DTI constraints, refinancing or selling the home may become necessary.
Real-World Impact on US Borrowers
Rising interest rates compress the pool of eligible borrowers and reduce transaction volume in the housing market. Fannie Mae research shows that rate movements of 1 to 2 percentage points can shift hundreds of thousands of households from qualified to unqualified status, particularly among first-time buyers with limited down payments and moderate incomes (Fannie Mae, 2026).
For example, a household earning $75,000 per year (approximately $6,250 per month gross) with $500 in existing monthly debt can afford a maximum housing payment of around $2,188 under a 43 percent DTI cap. At 3.5 percent, this supports a loan of roughly $310,000. At 6.5 percent, the same payment supports only about $205,000. The borrower must either reduce the purchase price, increase the down payment to keep the loan amount within reach, or wait for rates to decline.
Read also: How Rising Interest Rates Impact Mortgage Borrowing in the US
The Consumer Financial Protection Bureau emphasizes that borrowers should verify current rates and loan limits with a licensed lender before making purchase decisions, as rates change daily and qualification thresholds vary by loan program, lender overlay, and location (CFPB, 2026).
The Federal Reserve tracks interest rate movements through its H.15 daily release, which provides benchmark data for mortgage pricing. Rate increases by the Federal Reserve to combat inflation directly feed through to mortgage rates, tightening credit conditions and reducing affordability for rate-sensitive buyers (Federal Reserve, 2026).
Strategies for Borrowers Facing Higher Rates
Borrowers who fail the DTI threshold at prevailing rates have several options. One is to pay down existing debt to free up room under the DTI cap. Eliminating a $300 monthly car payment, for instance, can restore $300 in housing payment capacity, potentially adding tens of thousands of dollars to the supportable loan amount.
Another approach is to consider loan programs with more flexible DTI limits. FHA loans allow up to 50 percent DTI for well-qualified borrowers, and VA loans often approve DTI ratios above 50 percent when compensating factors (high credit score, substantial residual income, significant reserves) are present. Adjustable-rate mortgages also offer lower initial rates than fixed-rate loans, though borrowers must plan for potential rate increases after the initial fixed period.
Increasing the down payment reduces the loan amount required, which lowers the monthly payment and improves the DTI ratio. A borrower unable to qualify for a $350,000 loan with 5 percent down may qualify for a $320,000 loan with 15 percent down, assuming the same purchase price is no longer feasible and a lower-priced home is chosen instead.
Conclusion
Rising interest rates reduce mortgage borrowing capacity by increasing monthly payments and tightening debt-to-income ratios, often pushing otherwise qualified borrowers below lender approval thresholds. Understanding the relationship between rates, payments, and DTI is essential for realistic budgeting and successful home financing. Borrowers facing higher rates should evaluate their debt levels, explore loan programs with flexible qualification standards, and consult a licensed lender to determine the maximum supportable loan amount under current market conditions.
Financial Disclaimer: This article provides general educational information about mortgage borrowing and interest rates. It is not personalized financial, lending, or legal advice. Loan eligibility, interest rates, and qualification standards vary by lender, loan program, and location, and rates change daily. Consult a licensed mortgage lender or housing counselor approved by the U.S. Department of Housing and Urban Development (HUD) for guidance specific to your financial situation.
Sources
- Owning a Home (accessed )
- Selected Interest Rates (Daily) - H.15 (accessed )
- Research and Insights (accessed )
- Principles of Finance (accessed )
Related articles
How Rising Interest Rates Impact Mortgage Borrowing in the US
Rising interest rates reduce mortgage borrowing power by increasing monthly payments, pushing borrowers past debt-to-income limits and shrinking loan approval amounts.
Mortgage and Refinance Interest Rates Today in the US: Rates Edge Lower on October 21, 2026
Mortgage rates edged lower on October 21, 2026. See today's rates for purchase loans and refinancing, what's driving the shift, and what borrowers should do next.
US Mortgage Rates Hit Highest Levels in Over a Year
US mortgage rates surged above 7.2% this week, the highest in over a year. Learn what's driving rates up and what it means for buyers and refinancers.
