Canada's Mortgage Stress Test Explained
Understanding OSFI's mortgage stress test requirement and how it affects your borrowing power in Canada.
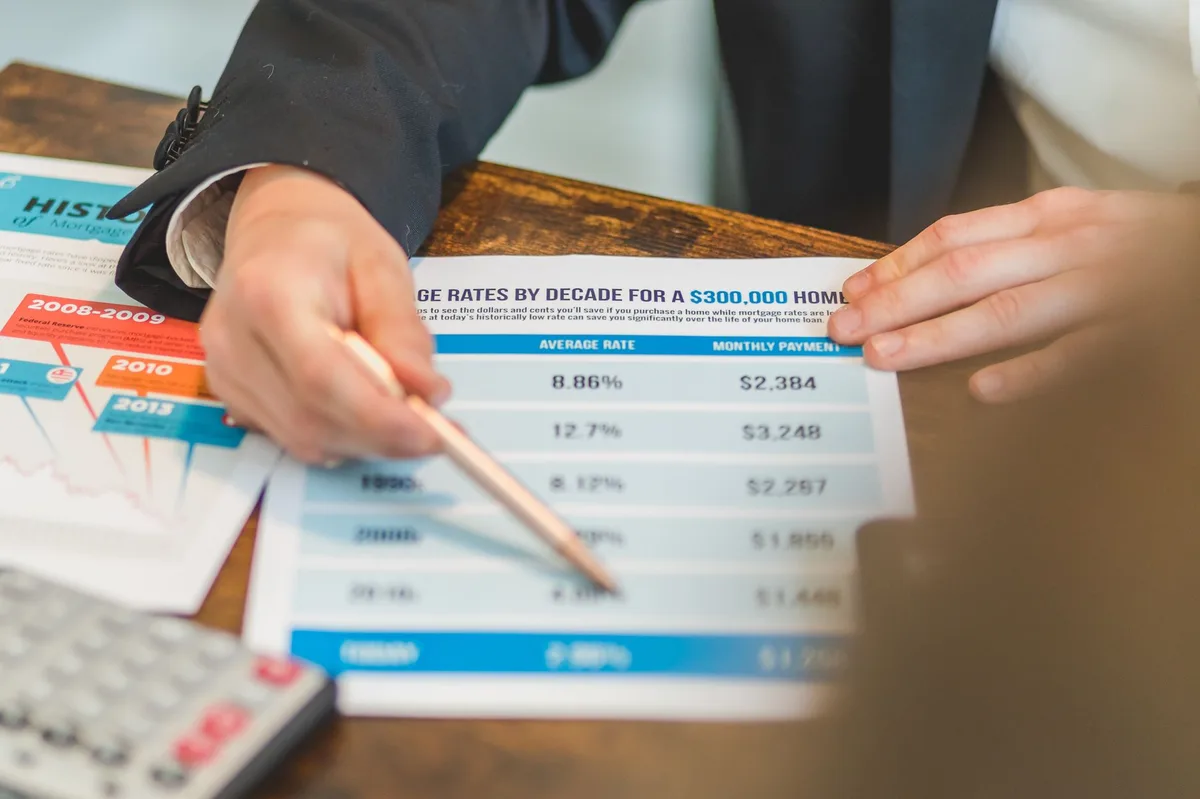
Pexels - RDNE Stock project · original
In this article
Key Takeaway
Canada’s mortgage stress test requires all homebuyers to qualify for their mortgage at a rate higher than their actual contract rate. You must prove you can afford payments at either 5.25 per cent or your contract rate plus 2 percentage points, whichever is higher. This federally mandated requirement, set by the Office of the Superintendent of Financial Institutions (OSFI) under Guideline B-20, applies to all federally regulated lenders and significantly reduces the maximum amount most Canadians can borrow.
What the Mortgage Stress Test Is
The mortgage stress test is a financial safeguarding measure that tests whether you can still afford your mortgage payments if interest rates rise. Rather than qualifying you based solely on the interest rate in your mortgage contract, lenders must verify that you can handle payments calculated at a higher “qualifying rate.”
According to the Office of the Superintendent of Financial Institutions, the stress test qualifying rate is the greater of either the Bank of Canada’s five-year benchmark rate (currently 5.25 per cent as of October 2026) or your actual mortgage rate plus two percentage points (OSFI, 2026).
This means if you are offered a five-year fixed rate at 4.5 per cent, you must qualify at 6.5 per cent (your rate plus 2 percentage points). If your rate is 3 per cent, you still qualify at 5.25 per cent (the benchmark floor).
Why Canada Introduced the Stress Test
OSFI introduced the stress test in 2018 to protect both borrowers and the financial system from the risks of rising interest rates and over-leveraged households. The measure addresses a core vulnerability in the Canadian mortgage market: the gap between the mortgage term and the amortization period.
Unlike the American 30-year fixed mortgage model, Canadian mortgages typically lock in rates for much shorter terms (one to five years), even though the amortization may stretch to 25 or 30 years. When your term ends, you renew at the prevailing market rate. If rates have climbed significantly during your term, your payments can jump sharply at renewal, as covered in foundational finance texts such as Principles of Finance.
The stress test ensures you can weather this rate volatility. It reduces the risk of payment shock at renewal and lowers the chance of default during economic downturns.
Who Must Pass the Stress Test
The stress test applies to all uninsured mortgages (those with a down payment of 20 per cent or more) at federally regulated lenders, which include the major Canadian banks, federally chartered trust companies, and most credit unions operating under federal oversight.
It also applies to insured mortgages (those with less than 20 per cent down, requiring CMHC mortgage default insurance). In fact, insured mortgages have been subject to stress testing since 2016, two years before the rule extended to uninsured mortgages.
Mortgage refinances and renewals where you switch lenders are also subject to the stress test. Only straight renewals with your existing lender at the end of your term are exempt.
How the Stress Test Affects Your Borrowing Power
The stress test substantially reduces the maximum mortgage amount you can qualify for. The Financial Consumer Agency of Canada notes that the requirement can lower your purchasing power by 15 to 20 per cent compared to qualifying at your actual contract rate (FCAC, 2026).
Worked Example
Assume you earn $100,000 annually (gross household income) and have no other debts. Your lender uses a maximum total debt service ratio of 44 per cent, meaning your housing costs (mortgage principal, interest, property taxes, heating, and 50 per cent of condo fees if applicable) cannot exceed $44,000 per year, or roughly $3,667 per month.
Property taxes, heating, and condo fees might total $800 per month, leaving $2,867 for your mortgage payment (principal and interest).
Read also: How the Mortgage Stress Test Works in Canada
At your contract rate of 4.5 per cent over 25 years: A monthly payment of $2,867 supports a mortgage of approximately $515,000.
At the stress test rate of 6.5 per cent over 25 years: The same $2,867 monthly payment supports a mortgage of only $420,000.
The stress test cuts your maximum borrowing capacity by nearly $95,000 in this scenario, even though your actual payments at the 4.5 per cent contract rate would be comfortably affordable.
Common Questions About the Stress Test
Does the stress test rate change? Yes. The Bank of Canada’s five-year benchmark rate is reviewed regularly and adjusts with the broader interest rate environment. The stress test qualifying rate rises and falls accordingly, though the floor mechanism (contract rate plus 2 percentage points) ensures the test remains rigorous even when rates are low.
Can I avoid the stress test? Most Canadians cannot. The stress test applies at all federally regulated lenders. Some provincially regulated credit unions and alternative lenders are not bound by OSFI’s B-20 guideline, but they typically charge higher interest rates to offset the additional risk, and you sacrifice the rate competitiveness and product choice of the major banks.
What if I fail the stress test? You have several options: increase your down payment to reduce the mortgage amount you need, add a co-borrower with additional income to boost your qualifying capacity, pay down existing debts to improve your debt service ratios, or wait and save longer to build a larger down payment. You might also consider a less expensive property that fits within your stress-tested borrowing limit.
The Stress Test at Renewal
When your mortgage term ends and you renew with the same lender, you do not face the stress test again. Your lender will typically offer you a renewal at current market rates without re-qualifying your income or running a new credit check.
However, if you want to switch lenders at renewal to secure a better rate, the new lender must apply the stress test as if you were a new borrower. This can trap some homeowners with their current lender, particularly if their financial situation has changed (reduced income, new debts, or property values that have not kept pace with inflation). The Canada Mortgage and Housing Corporation emphasizes the importance of understanding these renewal dynamics when choosing your initial mortgage term (CMHC, 2026).
Conclusion
Canada’s mortgage stress test is a permanent feature of the qualification process, designed to build resilience into household finances and protect the stability of the financial system. While it reduces your immediate borrowing power, it ensures you enter homeownership with a sustainable debt load that can withstand rising rates at renewal.
Understanding the mechanics of the stress test and planning your purchase, down payment, and budget around the qualifying rate rather than the contract rate positions you for long-term success as a Canadian homeowner.
Financial Disclaimer: This article provides general educational information about Canada’s mortgage stress test and is not personalized financial, lending, or legal advice. Mortgage qualification rules, stress test rates, lending criteria, and affordability calculations vary by lender, province, and your individual financial circumstances. The stress test qualifying rate and the Bank of Canada benchmark rate change over time; verify current rates and requirements with a licensed mortgage broker or your financial institution before making decisions. For advice specific to your situation, consult a licensed mortgage professional or financial adviser.
Sources
- Residential Mortgage Underwriting Practices and Procedures - Guideline B-20 (accessed )
- Mortgages (accessed )
- Home Buying (accessed )
- Principles of Finance (accessed )
Related articles
How the Mortgage Stress Test Works in Canada
The Canadian mortgage stress test ensures you can afford payments if rates rise. Learn how it works and how to prepare.
Understanding Canada's Mortgage Stress Test: A Complete Guide
Canada's mortgage stress test requires you to qualify at a higher rate than your actual mortgage rate. Learn how it works and how to pass it.
Canada B-20 Mortgage Stress Test: A Guide for First-Time Buyers in 2026
Learn how Canada's B-20 mortgage stress test works for first-time buyers, comparing insured vs uninsured mortgages and qualifying rates in 2026.
