Understanding the Mortgage Stress Test Exemption for Switching Lenders in Canada
Canadian homeowners can now switch mortgage providers without passing the stress test, making it easier to access better rates and terms at renewal.
Pexels - RDNE Stock project · original
In this article
Key Takeaway
Canadian homeowners can now switch their mortgage to a different lender at renewal without having to pass the federal mortgage stress test, as long as they stay within their original amortization period and do not borrow additional funds. This policy change, implemented by the Office of the Superintendent of Financial Institutions (OSFI), removes a significant barrier that previously prevented many borrowers from accessing better rates when their mortgage term ended.
What the Mortgage Stress Test Exemption Means
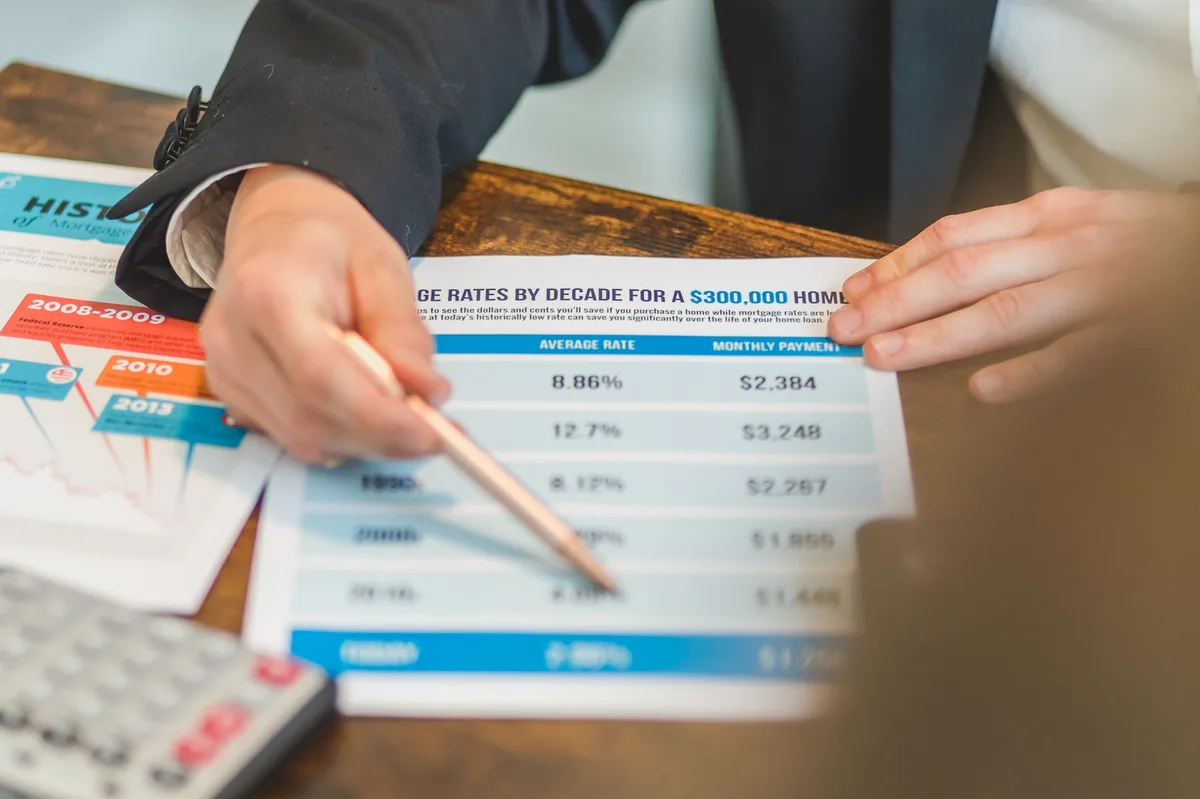
A recent regulatory adjustment has made it substantially easier for Canadian homeowners to switch mortgage providers when their term comes up for renewal. Under the revised OSFI guidelines, borrowers who simply want to transfer their existing mortgage balance to a new lender no longer need to qualify at the higher stress test rate.
This change addresses a long-standing friction point in the Canadian mortgage market. Previously, even homeowners with perfect payment histories and substantial home equity faced the stress test hurdle when trying to move their business to a competitor offering better terms. The exemption now puts switching borrowers on more equal footing with those who simply renew with their current lender.
Understanding the Mortgage Stress Test
The mortgage stress test, formally part of OSFI’s B-20 guidelines, requires borrowers to qualify for a mortgage at a rate higher than what they will actually pay. According to the Office of the Superintendent of Financial Institutions (OSFI), this qualifying rate is typically either the contract rate plus 2 percentage points or the Bank of Canada’s five-year benchmark rate, whichever is higher (OSFI, 2026).
The stress test was introduced to ensure borrowers could still afford their payments if interest rates rose significantly or their financial situation changed. As covered in foundational texts such as Principles of Finance, lenders assess borrower capacity by stress-testing scenarios beyond the current contract terms to protect both the borrower and the financial system from over-leverage.
When the stress test applies, a household earning C$100,000 annually might qualify for a mortgage of C$450,000 at a 5 per cent contract rate, but only C$380,000 after applying the stress test at 7 per cent. This gap has prevented many homeowners from switching lenders even when competitors offered rates a full percentage point lower.
Who Benefits From the Exemption
The exemption specifically helps homeowners who meet these conditions:
The mortgage is at the end of its term and due for renewal. The borrower wants to switch to a new lender without increasing the outstanding principal balance. The new mortgage maintains or reduces the remaining amortization period from the original loan.
This typically includes borrowers who took out a five-year fixed mortgage, made regular payments throughout the term, and now want to shop around for a better rate. It does not apply to borrowers refinancing to access home equity, extend their amortization, or consolidate other debts, all of which still require passing the full stress test.
Homeowners with strong credit and payment histories stand to benefit most. If your current lender quotes you 5.2 per cent at renewal but a competitor offers 4.6 per cent, you can now make the switch without requalifying under the stress test, provided you meet the other conditions.
How to Take Advantage When Switching Lenders
Start shopping for rates at least 120 days before your renewal date. Most lenders allow you to lock in a rate four months in advance, and you are not obligated to accept your current lender’s renewal offer.
Read also: Do You Need a Stress Test to Switch Mortgage Providers in Canada?
Request quotes from at least three to five lenders, including both the major banks and alternative lenders or mortgage brokers who may have access to better rates. Make it clear you are transferring an existing mortgage balance at renewal, not refinancing or borrowing additional funds.
Confirm with the new lender that the switch qualifies for the stress test exemption. While the OSFI guideline is federal, individual lenders apply their own underwriting policies, and you want written confirmation that you will not face the higher qualifying rate.
Review all associated costs. Switching lenders at renewal typically involves legal fees, appraisal fees, and sometimes a discharge fee from your current lender. These costs usually range from C$800 to C$1,500. Calculate whether the interest savings from the lower rate over your next term will exceed these upfront costs.
Important Considerations and Limitations
The exemption applies only to straight switches at renewal. If you want to increase your mortgage balance, access home equity, or extend your remaining amortization, you will still need to pass the stress test. According to the Financial Consumer Agency of Canada, refinancing to consolidate debt or fund renovations requires a full application under the standard qualifying criteria (FCAC, 2026).
Your current lender is under no obligation to match a competitor’s rate, although many will negotiate rather than lose your business. Use competing offers as leverage in renewal discussions, but be prepared to follow through on a switch if your lender will not move on price.
Rates and qualification rules change frequently. The exemption and the stress test parameters themselves are subject to adjustment by OSFI based on economic conditions and housing market stability. Always confirm current requirements with your lender or a licensed mortgage broker before making decisions.
Finally, the Canada Mortgage and Housing Corporation recommends that all borrowers carefully review the terms, prepayment privileges, and penalties of any new mortgage, not just the interest rate (CMHC, 2026). A slightly higher rate with flexible prepayment options may serve you better than a rock-bottom rate with restrictive terms.
Conclusion
The mortgage stress test exemption for switches represents a meaningful shift in Canadian mortgage policy, giving homeowners more flexibility and bargaining power at renewal. By removing the qualification barrier for borrowers who are simply moving their existing mortgage to a new lender, OSFI has made it easier to access competitive rates and terms. As with any mortgage decision, verify your eligibility, compare total costs, and confirm the details with a licensed mortgage professional.
Disclaimer: This article provides general educational information about Canadian mortgage policy and is not personalized financial, legal, or lending advice. Mortgage qualification rules, interest rates, and available products vary by lender, province, and individual circumstances. The OSFI stress test exemption for switches applies only under specific conditions and is subject to change. Consult a licensed mortgage broker or your financial institution to confirm current requirements and determine the best approach for your personal situation before making any mortgage decisions.
Sources
- Residential Mortgage Underwriting Practices and Procedures (accessed )
- Mortgages (accessed )
- Home Buying Guide (accessed )
- Principles of Finance (accessed )
Related articles
Mortgage Stress Test Requirement Lifted for Renewing Borrowers Who Switch Lenders in Canada
Learn how the 2024 policy change lets renewing Canadian borrowers switch lenders without the stress test, what it means for your renewal, and key limitations.
Do You Need a Stress Test to Switch Mortgage Providers in Canada?
Learn when Canadian homeowners can switch mortgage providers without a stress test, and when refinancing still requires qualification.
OSFI Stress Test on Mortgage Switches Ends in Canada: What You Need to Know
Learn what OSFI's mortgage switch stress test change means in Canada, who qualifies, and when borrowers still need to requalify.
