Mortgage Stress Test Requirement Lifted for Renewing Borrowers Who Switch Lenders in Canada
Canadian borrowers renewing their mortgage can now switch lenders without passing the stress test, removing a barrier that previously limited rate shopping at renewal.
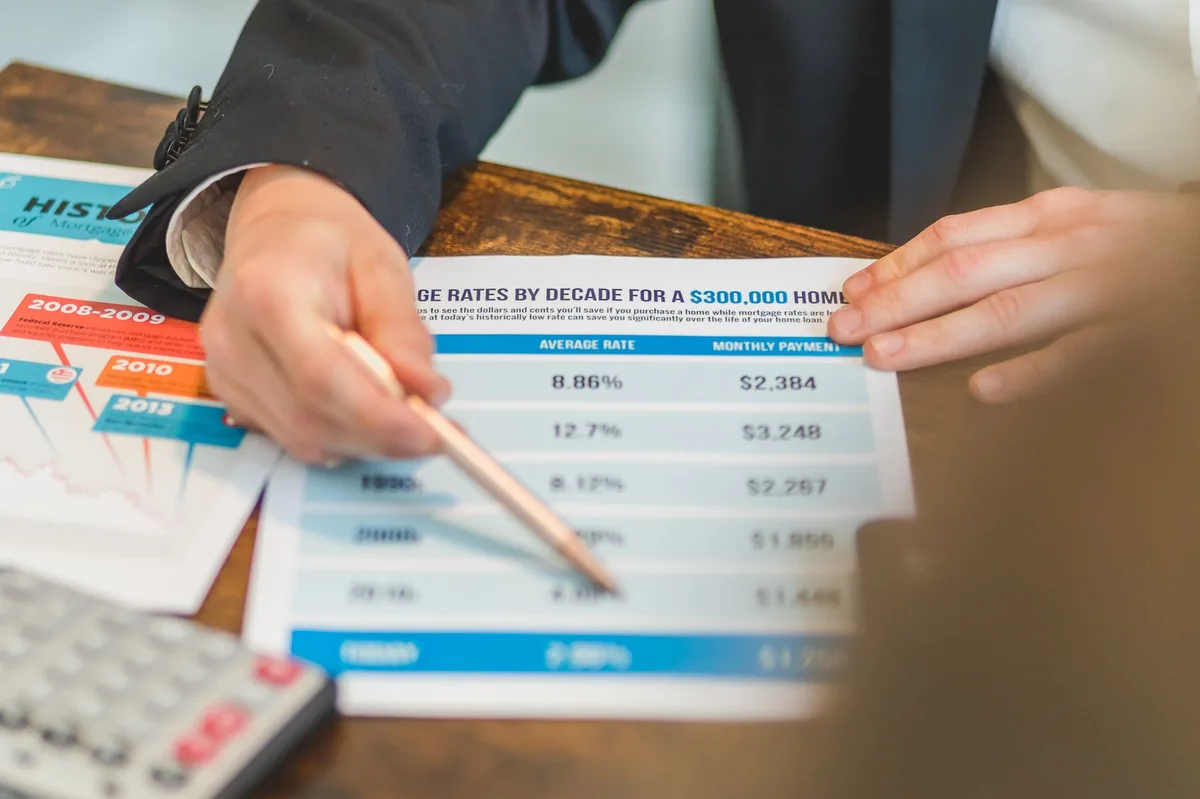
Pexels - RDNE Stock project · original
In this article
As of 2024, Canadian borrowers renewing their mortgage can now switch lenders without having to pass the federal mortgage stress test, provided they stay within their original amortization schedule and do not increase their principal. This regulatory change removes a major barrier that previously trapped many borrowers with their existing lender at renewal time, even when better rates were available elsewhere. The policy shift applies to straight renewals only, not refinances that access equity or extend amortization.
What Changed and Why It Matters
For years, Canadian mortgage holders faced an unusual dilemma at renewal time. If they wanted to switch to a new lender offering a lower rate, they had to qualify under the federal mortgage stress test, the same hurdle faced by brand-new buyers. Borrowers staying with their current lender, however, could renew without retesting, even if their financial situation had weakened since the original approval.
According to the Office of the Superintendent of Financial Institutions, this asymmetry created an unintended lock-in effect (OSFI, 2024). Borrowers who had proven they could carry their mortgage for years were blocked from accessing better rates simply because interest rates had risen and they could no longer qualify at the inflated stress-test rate. The 2024 policy update corrects this: renewing borrowers can now switch lenders on equal terms with those who stay put, as long as the renewal is a true like-for-like replacement.
Understanding the Mortgage Stress Test
The mortgage stress test, introduced federally in 2018 under OSFI Guideline B-20, requires borrowers to prove they can afford their mortgage payments at a higher qualifying rate. Currently, lenders must qualify you at either your contract rate plus 2 percentage points, or the Bank of Canada’s posted benchmark rate (whichever is higher). If your actual mortgage rate is 5.5 per cent, for instance, you would need to demonstrate you could still make payments if the rate were 7.5 per cent or higher.
The stress test serves as a buffer against financial shocks. It ensures that if rates rise sharply, or if your income drops, you have enough margin to keep paying. As covered in foundational financial texts such as Principles of Finance, qualifying borrowers at a rate above the contract rate is a prudent risk-management practice that protects both lenders and borrowers from overleveraging.
Who This Change Affects
The stress-test exemption for switching lenders applies specifically to borrowers whose mortgage term is ending and who are renewing under these conditions:
- The mortgage amount stays the same or decreases (no additional borrowing or equity withdrawal).
- The remaining amortization period does not increase beyond the original schedule.
- The property remains owner-occupied.
- The lender holds the mortgage in its own portfolio or sells it to an entity that meets OSFI capital requirements.
This means a borrower with a five-year fixed-rate mortgage who is reaching the end of the term, still has 20 years of amortization remaining, and simply wants a new five-year term at a competitive rate can now shop across lenders without retesting. The Financial Consumer Agency of Canada notes that this flexibility gives renewing borrowers the same competitive advantage as those refinancing internally, encouraging rate shopping and market discipline (FCAC, 2024).
What This Does Not Cover
The exemption is narrow. It does not apply to refinancing transactions where you access home equity, extend your amortization beyond the original end date, or convert from a rental property mortgage to an owner-occupied mortgage. If you want to pull out C$50,000 in equity at renewal time, or if you want to reset your amortization from 20 years remaining back to 25 or 30 years, you are refinancing, not renewing, and the stress test still applies in full.
Read also: How the Mortgage Stress Test Affects Your Renewal in Canada
Similarly, if you are switching from a variable-rate mortgage to a fixed-rate mortgage or vice versa but keeping everything else the same, the exemption can still apply, because the product type is not the determining factor. The key tests are: same or lower principal, same or shorter remaining amortization, and no equity withdrawal.
Practical Implications for Renewing Borrowers
This policy shift has several real-world effects. First, it restores competition at renewal time. Lenders can no longer count on inertia to retain customers who might not qualify under current stress-test rules. Borrowers who have been making payments reliably for five years can now threaten to leave if their existing lender does not offer a competitive rate, and follow through on that threat without hitting a qualification wall.
Second, it reduces the penalty for rising interest rates. Between 2022 and 2024, the Bank of Canada raised its policy rate sharply to fight inflation, and many borrowers who took out mortgages in the low-rate environment of 2020 or 2021 found themselves unable to qualify under the stress test when their term ended, even though they had never missed a payment. The exemption ensures that a temporary rate spike does not permanently trap borrowers with one lender.
Third, it aligns Canadian mortgage rules more closely with the economic reality that a renewing borrower is a known quantity. A borrower five years into a mortgage, with a clean payment history and stable income, represents lower risk than a brand-new applicant, yet before this change the switcher faced a higher qualification bar. The Canada Mortgage and Housing Corporation has highlighted that reducing unnecessary friction in the mortgage market supports housing affordability by letting borrowers access the best available terms (CMHC, 2024).
Important Limitations and Next Steps
The exemption does not override a lender’s internal credit policies. Even without the stress test, a lender switching you in at renewal will still verify your income, check your credit score, confirm the property value, and assess whether you meet their underwriting standards. If your credit has deteriorated significantly, or if you have taken on substantial new debt since your original approval, the new lender can still decline you, just not on stress-test grounds alone.
Prepayment penalties also remain a consideration. If you are breaking your existing mortgage term early to switch (rather than waiting until the true maturity date), your current lender can charge you an interest rate differential penalty, which can be substantial on a fixed-rate mortgage. The stress-test exemption does not waive or reduce that penalty. Always confirm your maturity date and calculate any penalties before committing to switch.
Conclusion
The 2024 removal of the stress-test requirement for straight renewals when switching lenders restores a level playing field for Canadian mortgage holders. Borrowers who have demonstrated their ability to carry a mortgage can now shop freely at renewal time, access better rates, and avoid being locked in by a qualification rule designed for new borrowers. This change is limited to true renewals (same principal, same or shorter remaining amortization, no equity access), and lenders will still verify credit and income, but the core barrier has been lifted. If your mortgage term is ending soon, you now have real leverage to negotiate, and the freedom to move if your existing lender will not match the market.
This article provides general educational information about Canadian mortgage regulations and does not constitute personalized financial, lending, or legal advice. Mortgage products, qualification requirements, and prepayment penalties vary by lender, province, and individual circumstances. Interest rates and regulatory rules change frequently. Consult a licensed mortgage broker or your financial institution to confirm current terms, eligibility, and costs specific to your renewal situation before making any decisions.
Sources
- Residential Mortgage Underwriting Practices and Procedures - Guideline B-20 (accessed )
- Mortgages - Financial Consumer Agency of Canada (accessed )
- Home Buying - Consumer Resources (accessed )
- Principles of Finance (accessed )
Related articles
How the Mortgage Stress Test Affects Your Renewal in Canada
Learn how the OSFI mortgage stress test applies at renewal in Canada and whether you need to re-qualify when your term ends.
Understanding the Mortgage Stress Test Exemption for Switching Lenders in Canada
Learn how the mortgage stress test exemption works for Canadians switching lenders, who qualifies, and how to use it to secure better rates.
Do You Need a Mortgage Stress Test to Switch Lenders in Canada?
Learn when Canadian homeowners can switch mortgage lenders without a stress test, and when refinancing still triggers qualification.
