The OSFI Stress Test Exemption for Insured Mortgage Switches in Canada
A largely unknown OSFI exemption allows borrowers with insured mortgages to switch lenders at renewal without passing the mortgage stress test, potentially saving thousands in interest.
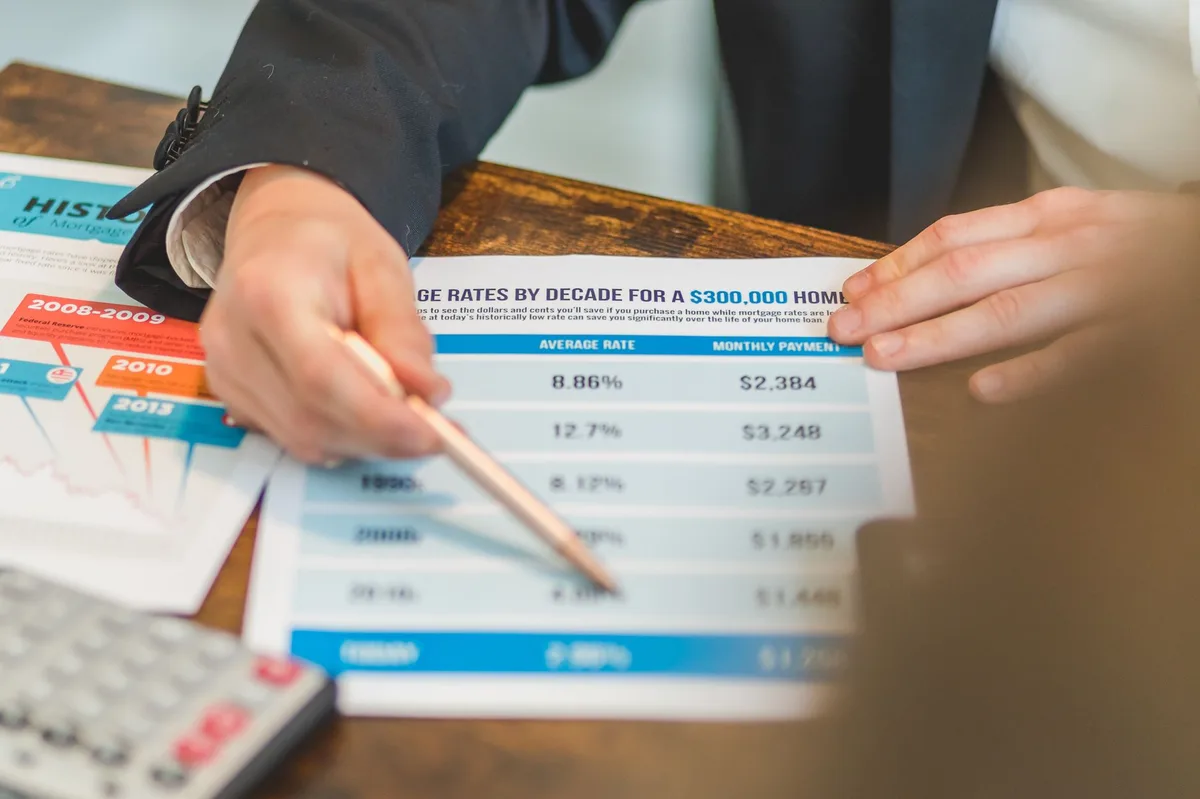
Pexels - RDNE Stock project · original
In this article
Key Takeaway: Canadian homeowners with insured mortgages (those who put down less than 20 per cent and paid for CMHC mortgage default insurance) can switch to a new lender at renewal without passing the OSFI mortgage stress test, provided the mortgage balance does not increase. This exemption, detailed in OSFI’s B-20 guideline, allows qualifying borrowers to access better rates even if their income no longer meets current stress test requirements.
What OSFI Revealed About Insured Mortgage Switches
The Office of the Superintendent of Financial Institutions oversees mortgage lending standards in Canada through its B-20 guideline, which includes the mortgage stress test requirement. According to the Financial Consumer Agency of Canada, most borrowers must prove they can afford mortgage payments at either the contract rate plus two percentage points or the Bank of Canada’s qualifying rate, whichever is higher (FCAC, 2024). This stress test applies to new mortgages, refinances, and most renewals when switching lenders.
However, OSFI reporting has drawn attention to a little-known exemption: borrowers with insured mortgages who switch lenders at renewal are exempt from the stress test, as long as they are not increasing their mortgage balance. This exemption exists because the mortgage insurance provided by CMHC or other approved insurers already protects the lender against default risk, as foundational finance texts such as Principles of Finance explain when discussing risk mitigation in lending.
Understanding Insured Mortgages and the Switch Process
An insured mortgage is one where the borrower made a down payment of less than 20 per cent of the purchase price and purchased mortgage default insurance to protect the lender. The Canada Mortgage and Housing Corporation is the primary provider of this insurance in Canada, though private insurers also operate in this space (CMHC, 2024).
When your mortgage term ends (typically after one to five years), you have three options: renew with your current lender, switch to a new lender while keeping the same mortgage balance (called a straight switch), or refinance by increasing your mortgage balance or changing other terms. A straight switch means you are simply moving your existing insured mortgage to a new lender without borrowing additional funds.
The stress test exemption applies specifically to straight switches of insured mortgages. If you refinance and increase your balance, the exemption no longer applies, and you must pass the current stress test.
How the Stress Test Normally Works
The OSFI mortgage stress test, implemented under guideline B-20, requires borrowers to qualify at a rate higher than their actual contract rate. As of October 2026, borrowers must qualify at the greater of their contract rate plus two percentage points or 5.25 per cent, the qualifying rate set by the Bank of Canada (rates change periodically and should be verified with a licensed mortgage professional before making decisions).
For example, if you are offered a mortgage at 4.5 per cent, the lender must verify that you can afford the payments calculated at 6.5 per cent (4.5 per cent plus 2 percentage points). This ensures borrowers have a buffer if rates rise at renewal time.
This requirement significantly affects how much you can borrow. A household with a gross annual income of C$100,000 might qualify for a mortgage of approximately C$450,000 under current stress test rules, but the same household could potentially have qualified for C$520,000 or more before the stress test was implemented.
Why the Exemption Exists for Insured Switches
The exemption for insured mortgage switches exists because of the risk profile difference between insured and uninsured mortgages. According to the Office of the Superintendent of Financial Institutions, insured mortgages carry mortgage default insurance that protects lenders in the event of borrower default (OSFI, 2024). This insurance, paid for by the borrower at the time of purchase, remains in place for the life of the mortgage even as the loan-to-value ratio decreases over time.
Because the insurance mitigates the lender’s risk, OSFI determined that requiring a stress test for straight switches of insured mortgages would create an unnecessary barrier to competition among lenders without meaningfully reducing systemic risk. The exemption allows borrowers to shop for better rates at renewal time without being locked into their current lender simply because their income has not kept pace with stress test requirements.
Who Benefits and What the Constraints Are
This exemption primarily benefits homeowners who purchased with less than 20 per cent down and whose financial circumstances have changed since they first qualified. Common scenarios include:
Households where one income earner has reduced hours or stopped working to care for children or family members. While their income may have decreased, their payment history demonstrates they can afford their existing mortgage.
Self-employed borrowers whose reported income fluctuates year to year but who have maintained consistent mortgage payments.
Borrowers in markets where home prices have risen dramatically since purchase, making it difficult to qualify under current stress test rules even though they are comfortably making payments on their existing mortgage.
Read also: BMO Brings Back the OSFI Stress Test for Uninsured Mortgage Switches in Canada
The key constraint is that you cannot increase your mortgage balance. If you want to access home equity, consolidate debt, or borrow additional funds, you must refinance and pass the current stress test. The exemption applies only when you are moving your existing mortgage balance to a new lender.
Additionally, the mortgage must actually be insured. If you purchased with less than 20 per cent down but your lender obtained portfolio insurance (a different type of insurance not paid for by the borrower), you may not qualify for this exemption. Confirm your mortgage insurance status with your current lender before assuming you are eligible.
Practical Implications at Renewal Time
When your mortgage term approaches its end, your current lender will offer you a renewal rate. This rate is often higher than what new customers receive, because lenders know many borrowers will simply accept the renewal offer without shopping around.
If you have an insured mortgage and want to switch to a competitor offering a lower rate, you can do so without passing the stress test, provided you are not increasing your balance. This process typically involves:
Contacting competing lenders or a mortgage broker to obtain rate quotes 120 to 180 days before your renewal date.
Completing a mortgage application with the new lender, which will verify your payment history, confirm your mortgage is insured, and ensure the balance is not increasing.
Working with the new lender to transfer the mortgage, a process that typically takes two to four weeks and involves minimal legal fees (often C$200 to C$400, which some lenders cover as a promotional incentive).
The new lender will not charge you a prepayment penalty because you are switching at renewal, when your term has ended. If you attempt to switch before your term ends, you will face prepayment penalties calculated using the interest rate differential method, which can amount to thousands of dollars.
Common Misconceptions About the Exemption
Many borrowers mistakenly believe the stress test exemption applies to all renewal situations or that it allows them to access equity without qualifying. Neither is accurate. The exemption is narrow: it applies only to insured mortgages, only when switching lenders, and only when the balance does not increase.
Renewing with your current lender does not require a stress test regardless of whether your mortgage is insured, because you are continuing an existing relationship and the lender already holds your mortgage. The exemption matters specifically when you want to move to a competitor for a better rate.
Another misconception is that the exemption allows you to skip income verification entirely. While you do not need to meet the stress test qualifying rate, lenders will still verify that you have sufficient income to make the actual mortgage payments at the contract rate and that your payment history is satisfactory.
Conclusion
The OSFI stress test exemption for insured mortgage switches represents a meaningful opportunity for Canadian homeowners who purchased with less than 20 per cent down. By allowing these borrowers to move to competitive lenders at renewal without passing the stress test, the exemption promotes lender competition and helps households secure lower rates even when their income has not kept pace with stress test requirements.
If your mortgage term is ending soon and you put down less than 20 per cent when you purchased, confirm with your lender that your mortgage carries CMHC or private mortgage default insurance, then shop competing offers. You may qualify for rates significantly lower than your renewal offer, saving thousands of dollars over your next term without needing to meet current stress test thresholds.
Financial Disclaimer: This article provides general educational information about Canadian mortgage rules and is not personalized financial, lending, legal, or tax advice, and not an offer or commitment to lend. Mortgage stress test rules, insurance requirements, and lender policies vary by province, territory, and individual lender. Rates and qualification requirements change frequently. Consult a licensed mortgage broker or your financial institution to confirm current rules, verify your mortgage insurance status, and determine your personal eligibility for the stress test exemption before making mortgage decisions.
Sources
- Residential Mortgage Underwriting Practices and Procedures (Guideline B-20) (accessed )
- Mortgage loan insurance (accessed )
- Mortgages (accessed )
- Principles of Finance (accessed )
Related articles
OSFI's Stress Test Exemption for Mortgage Switches in Canada: What You Need to Know
OSFI removed the stress test for mortgage switches in Canada. Learn what changed, who benefits, and how to switch lenders at renewal for better rates.
BMO Brings Back the OSFI Stress Test for Uninsured Mortgage Switches in Canada
BMO now applies the OSFI stress test to uninsured mortgage switches in Canada, ending an industry exemption and tightening qualification for borrowers.
Mortgage Stress Test Requirement Lifted for Renewing Borrowers Who Switch Lenders in Canada
Learn how the 2024 policy change lets renewing Canadian borrowers switch lenders without the stress test, what it means for your renewal, and key limitations.
