Mortgage
Ubank's 10% Deposit Home Loan with No LMI in Australia
NAB-owned Ubank has launched a home loan requiring just a 10% deposit without lenders mortgage insurance (LMI) for eligible borrowers in Australia.
Articles about purchase under Mortgage.
NAB-owned Ubank has launched a home loan requiring just a 10% deposit without lenders mortgage insurance (LMI) for eligible borrowers in Australia.
Learn how to secure finance and prepare for unconditional auction bids when buying property at auction in Australia, from pre-approval to settlement.
Compare loan types, qualification criteria, and key features for Australian investment property loans to find the right finance for your rental property purchase.
A practical guide to the essential steps, deposit requirements, and government schemes that help first home buyers secure a home loan in Australia.
Compare five strategies to avoid or reduce LMI costs when buying a home in Australia, from saving a larger deposit to using government schemes and professional exemptions.
Spring is Australia's busiest property season. A strategic pre-approval gives you a clear budget, competitive edge at auction, and the confidence to act quickly when the right home appears.
Spring is Australia's busiest property season. Learn how to position your mortgage approval to move fast and win in a competitive market.
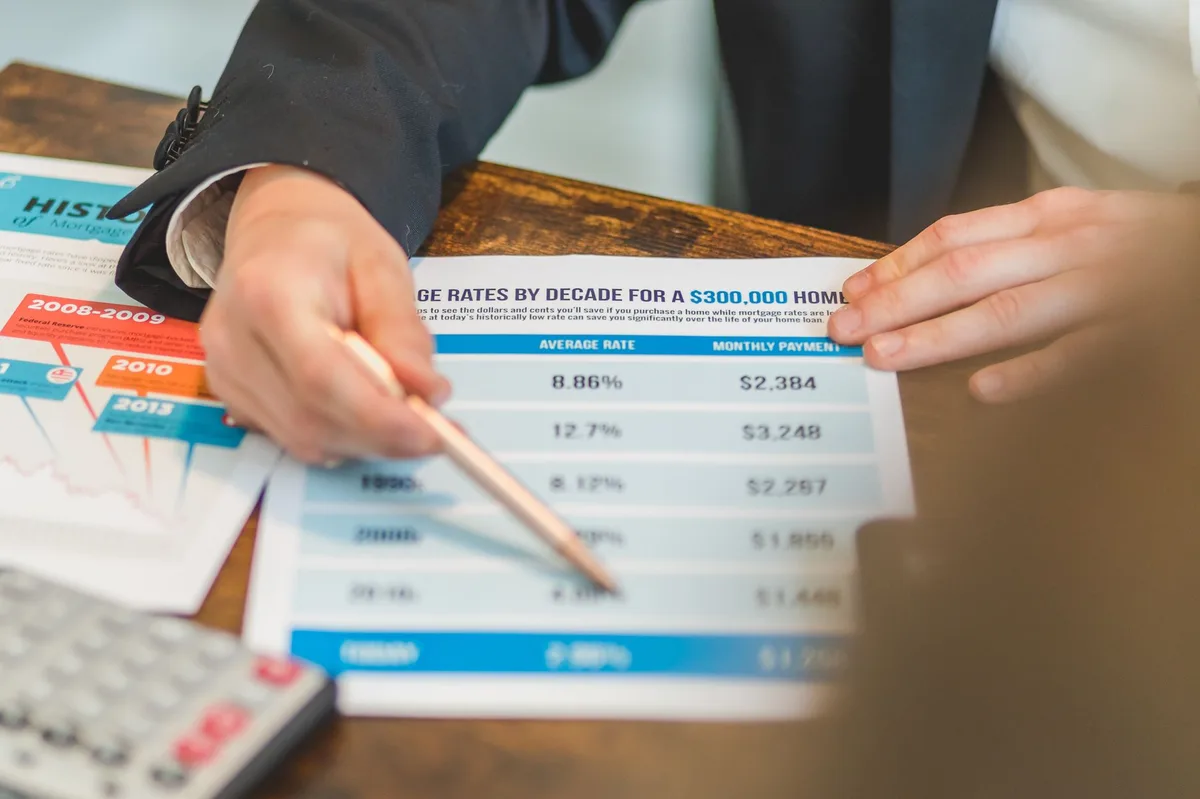
Compare principal and interest loans with interest-only loans to understand repayment structures, costs, and which option suits your financial situation.
Learn how bridging finance lets Australian property owners purchase their next home before settling the sale of their current property.
Essential checklist covering how construction loans work in Australia, from progress payments to practical completion.
Understand the difference between land tax and stamp duty, two major costs Australian property buyers need to know about when purchasing real estate.
When a bank's valuation comes in below your purchase price, your deposit and loan approval are at risk. Understand the options and calculate your real position.
Australian lenders accept gifted deposits from family but require a statutory declaration, proof of funds, and transfer evidence before settlement.
Rentvesting lets Australians enter the property market by purchasing an investment property in an affordable area while continuing to rent where they prefer to live.
Compare SMSF limited recourse borrowing against standard home loans to understand which structure suits your investment property strategy.
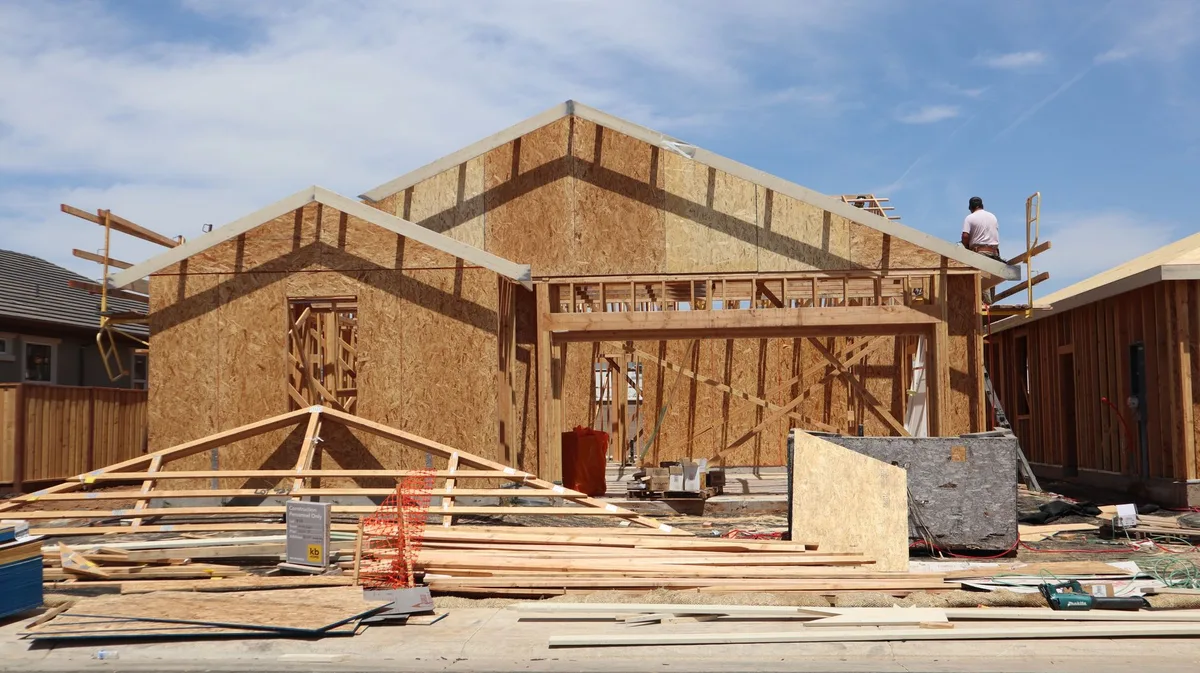
Learn how construction loan progress payments work in Australia and how interest is charged during the building phase.
A family guarantee lets first home buyers enter the market with a smaller deposit by using a parent's or relative's property as additional security, reducing or eliminating lenders mortgage insurance.
LMI protects lenders when you borrow more than 80 per cent of a property's value. Learn how it works, what it costs, and practical strategies to avoid or reduce this one-time premium.
Compare the three main construction loan types in Australia, understand how progress payments work, and find the right option for your building project.
A clear guide to understanding stamp duty and land tax obligations when buying property in Australia, including state variations and exemptions.
Bridging loans let you buy your next home before selling your current property, but they come with higher costs and risks you need to understand first.
Learn how rental yield helps you assess investment property performance and what metrics separate strong property investments from weak ones in the Australian market.
Learn to decode your mortgage amortisation schedule and understand exactly how much interest you'll pay over the life of your Australian home loan.
Understand how LMI premiums are calculated on high-LVR home loans in Australia and use our calculator to estimate your cost before you apply.
An amortisation schedule reveals exactly how much of each home loan repayment goes toward interest versus principal. Learn how to track your equity growth and make informed decisions about extra repayments.
Understand the key differences between using a mortgage broker and approaching lenders directly to make an informed decision for your Australian home loan.
A practical guide to choosing between interest-only and principal and interest repayments for your Australian investment property loan.
Compare the true cost of paying LMI to enter the market sooner against waiting to save a 20 per cent deposit, with worked examples for Australian home buyers.
Discover how green home loans reward borrowers who buy or renovate energy-efficient properties with lower rates, discounts, and stacking government incentives across Australia.
Understand what Australian lenders assess during pre-approval, the documents you need, and how long conditional approval remains valid before you buy.
LMI can add thousands to your home loan. Learn what triggers it, strategies to avoid it, and how to calculate your potential cost.
Lenders mortgage insurance can add thousands of dollars to a high-LVR home loan. Use an LMI estimate to compare buying sooner with a smaller deposit against waiting and saving more.
Learn how to time your fixed-rate lock when planning summer settlement, protect against rate rises, and avoid costly mistakes during peak property season.
Lenders mortgage insurance (LMI) is a one-off fee that protects your lender if you default on your home loan, typically required when your deposit is less than 20 per cent.
Learn how to structure investment property loans for tax efficiency, cash flow optimisation, and long-term wealth building in the Australian property market.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.
