Mortgage
FOMC October 27-28 Decision: What It Means for Mortgage Rates in the US
The Federal Reserve's upcoming October FOMC meeting could signal the direction for mortgage rates through year-end and into 2027.
Mortgage, refinance, and home-financing guidance for US buyers and owners.
The Federal Reserve's upcoming October FOMC meeting could signal the direction for mortgage rates through year-end and into 2027.
Mortgage rates show mixed movement this morning as markets digest recent economic data and Federal Reserve signals.
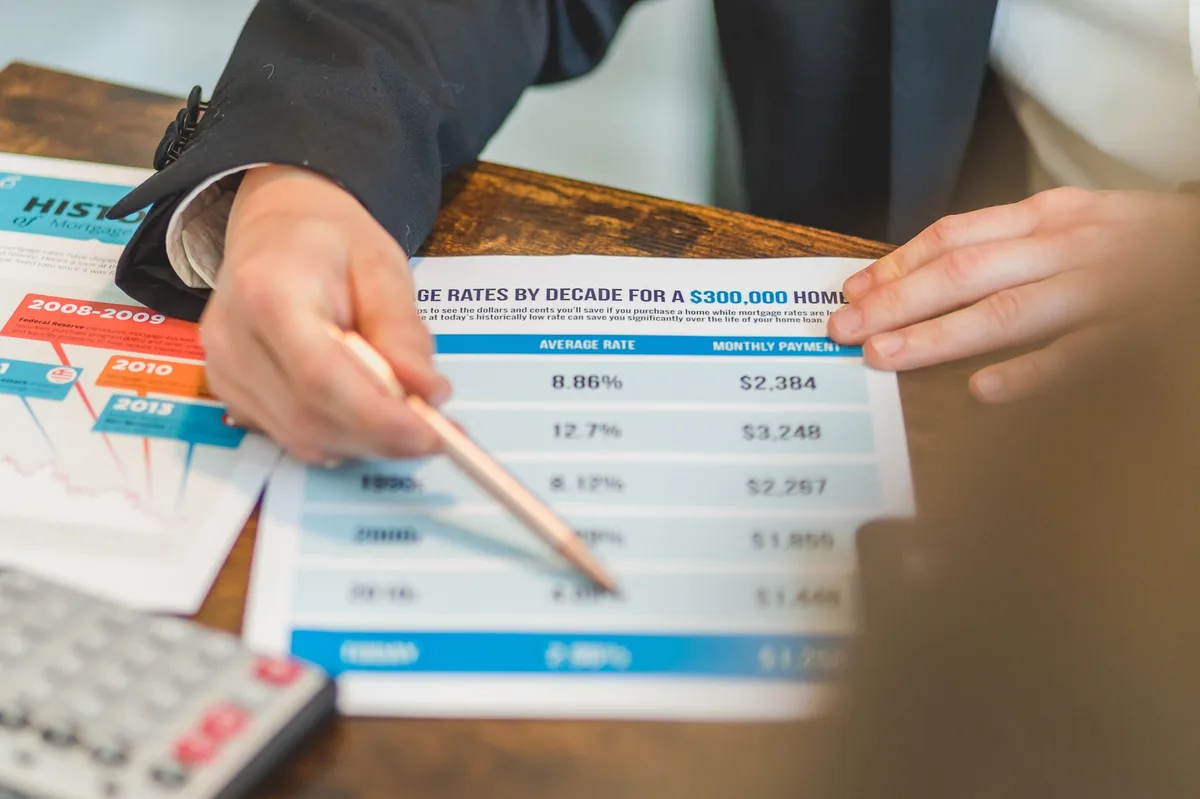
Mortgage rates dropped on Wednesday, with 30-year fixed loans averaging 5.78% and refinance rates following suit. See today's rates and what the decline means for borrowers.
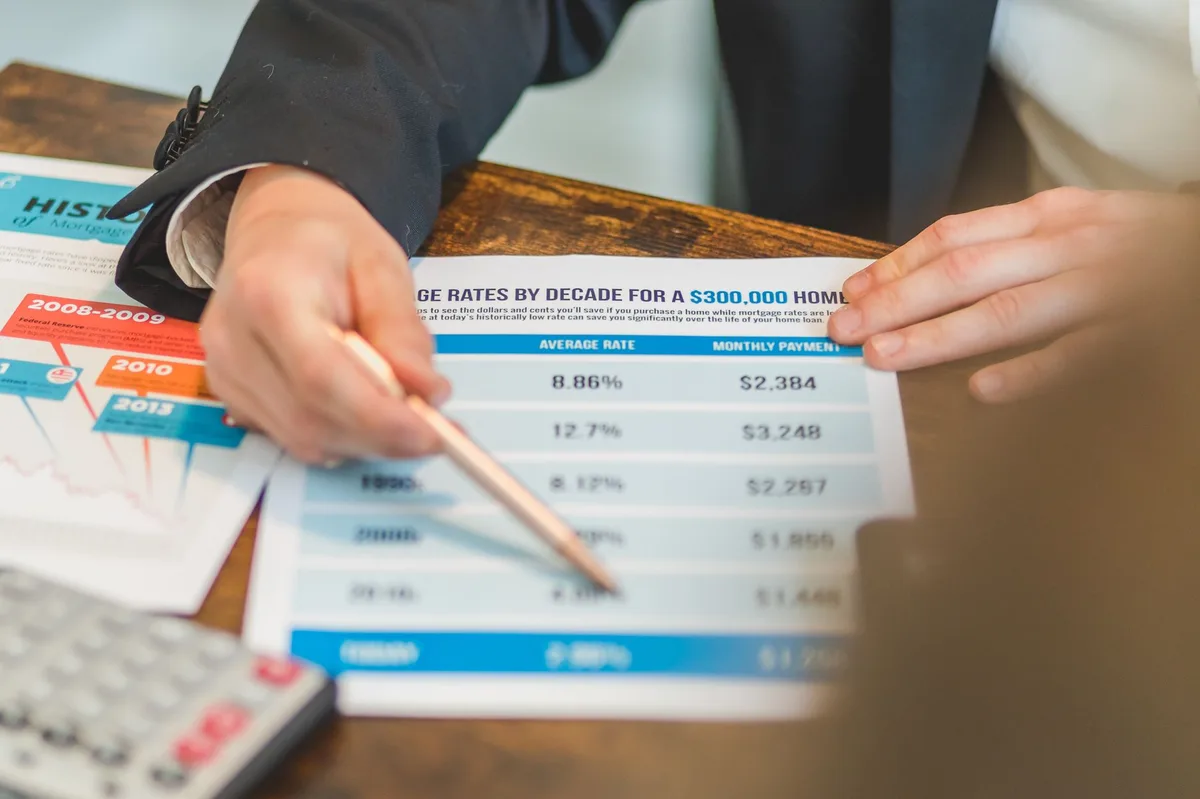
When mortgage rates are trending downward, buying discount points often works against you - learn when to skip them and when they might still make sense.
Mortgage and refinance rates continue climbing today, reaching levels not seen since the early 2000s as the Federal Reserve maintains its restrictive monetary policy.
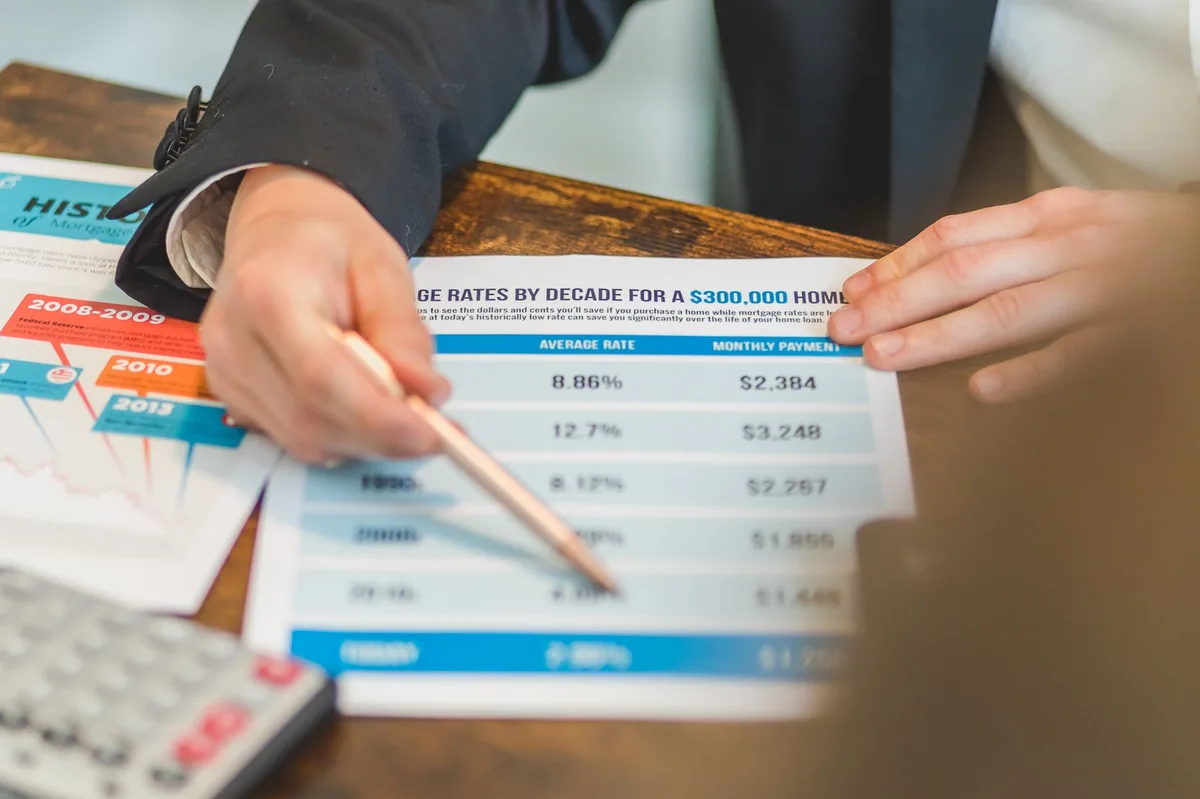
Learn how discount points work, calculate the break-even period, and decide whether buying down your mortgage rate makes financial sense.
Comparing home equity loans and HELOCs for your renovation project, with guidance on fixed versus variable rates, costs, and which option fits your timeline and budget.
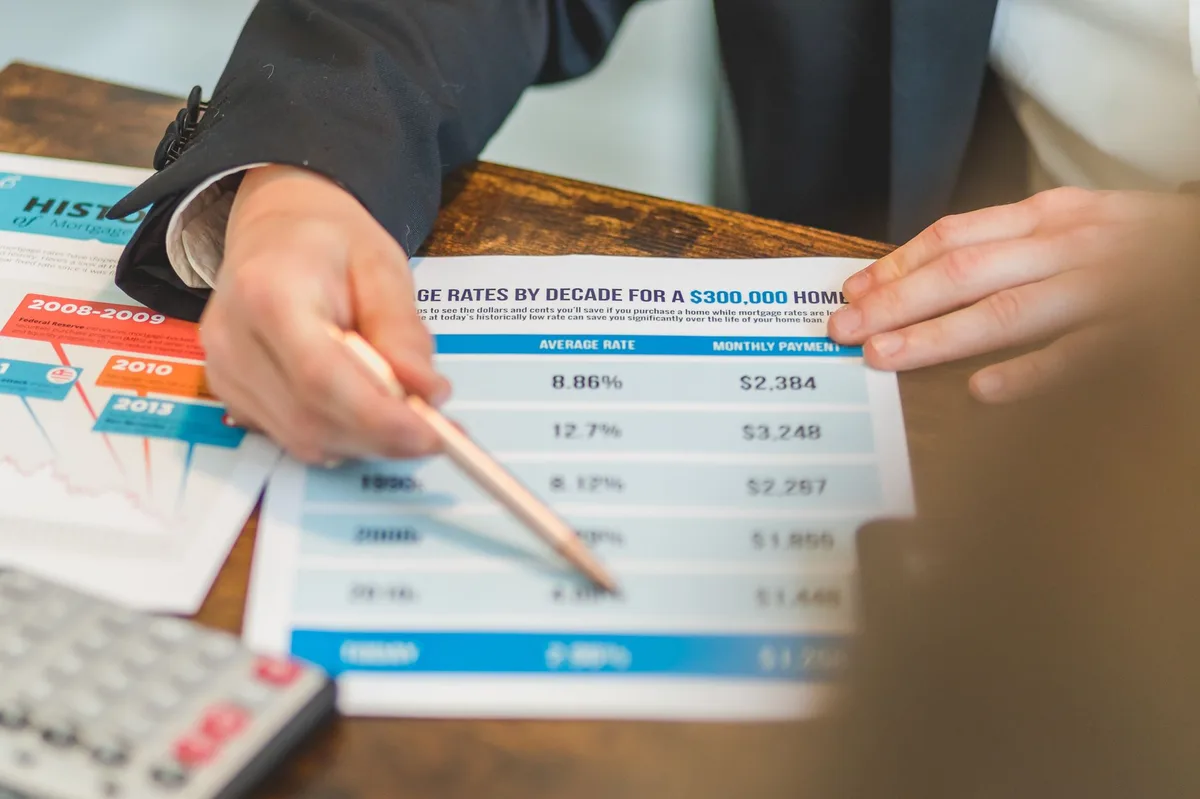
Compare cash-out refinancing and home equity loans to decide which financing option works best for your situation and financial goals.
Compare a HELOC to a cash-out refinance to decide which home equity option works best for your financial goals, timeline, and borrowing needs.
Learn how FHA-insured HECM reverse mortgages let homeowners 62 and older convert home equity into cash without monthly payments.
Learn the simple formula to calculate how much equity you can tap from your home for a HELOC or cash-out refinance, and understand the loan-to-value limits that determine your borrowing power.
Learn how interest accrues during a HELOC's draw and repayment periods and what you'll pay over the life of the loan.
FHA loans are government-backed mortgages that allow qualified buyers to purchase a home with as little as 3.5% down and lower credit scores than conventional loans require.
VA home loans offer veterans and active service members zero down payment, no PMI, and competitive rates. Learn the key benefits, eligibility rules, and costs.
Forbearance temporarily pauses your mortgage payments during financial hardship, but interest continues to accrue and other homeownership costs remain your responsibility.
Understanding the conforming loan limit and how crossing it changes your mortgage requirements, rates, and qualification standards.
FHA loans allow credit scores as low as 500, but most lenders require 580 or higher. Compare FHA, conventional, and credit-improvement paths to find the right approach for buying with imperfect credit.
Self-employed workers can qualify for a mortgage using bank statement loans or P&L documentation instead of traditional W-2 income verification.
Applying for a mortgage in fall brings different lender scrutiny than summer applications, from year-to-date income verification to post-summer employment stability.
Learn the five essential steps to secure your first home loan, from checking your credit to closing day.
In a competitive fall housing market, buyers need smart strategies to stand out. Learn proven tactics to strengthen your offer and beat other buyers.
Win your dream home this fall with strategic offers that stand out without overpaying - here is how to compete smart in the 2026 US market.
Lenders and the IRS classify second homes and investment properties differently, and those distinctions affect your down payment, interest rate, and tax deductions.
Compare assumable mortgage options - FHA, VA, and USDA loans - versus getting a new conventional loan, and learn when taking over a seller's low rate makes financial sense.
Compare refinancing scenarios to determine when the timing and cost savings justify replacing your current home loan.
When your adjustable-rate mortgage reset approaches, refinancing to a fixed rate often makes sense if the new rate will be significantly higher and you plan to stay in the home long enough to recover closing costs.
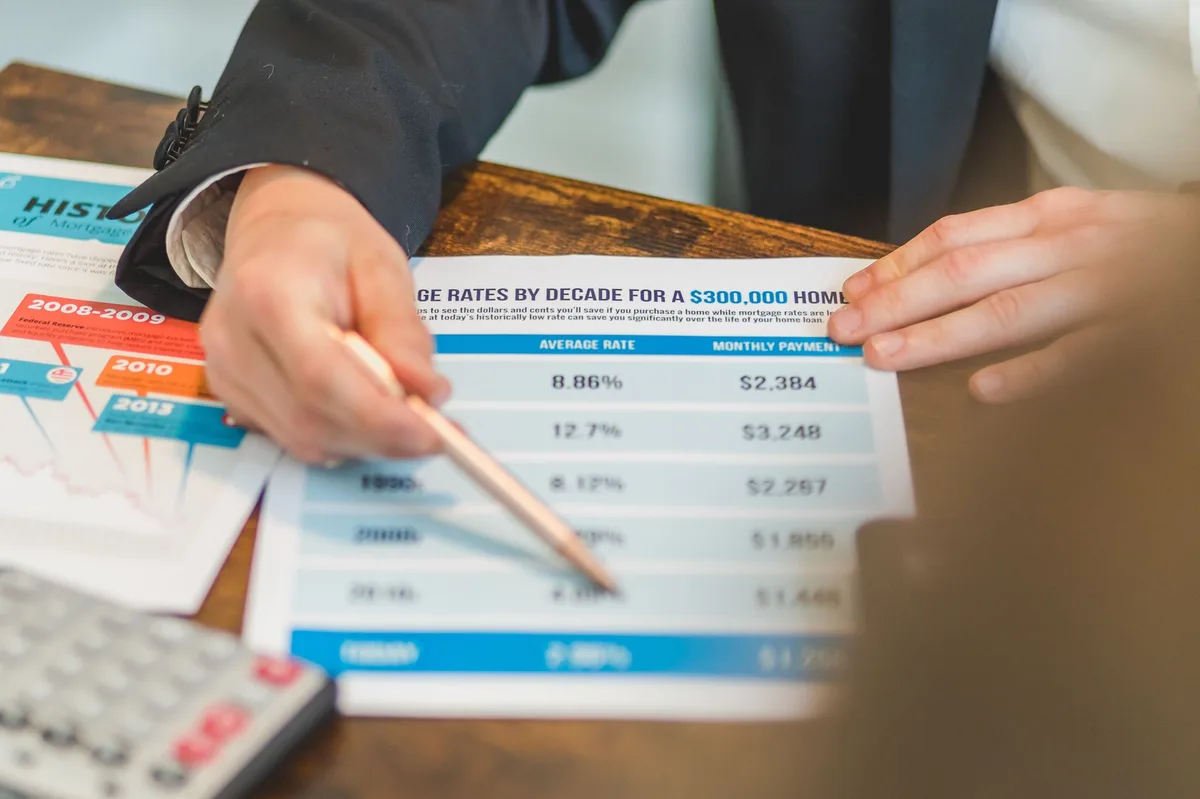
Learn the step-by-step process to evaluate whether refinancing your mortgage at current rates will save you money or cost more in the long run.
Compare mortgage recasting and refinancing to find the most cost-effective way to reduce your monthly payment without starting a new 30-year term.
Whether to refinance now or wait depends on your break-even timeline, how long you plan to stay in the home, and the real cost of waiting versus the potential savings from a future rate drop.
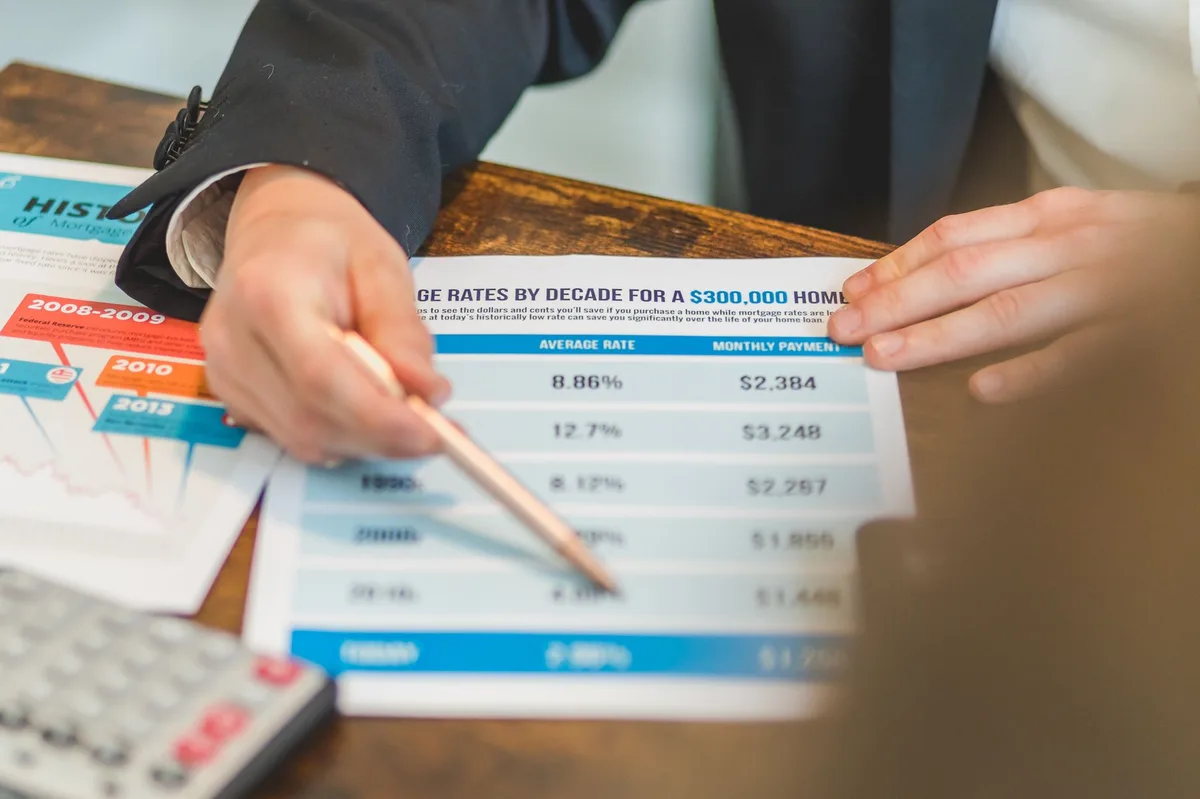
Refinancing your mortgage can save you thousands, but timing matters. Learn the five key scenarios when refinancing makes financial sense for US homeowners.
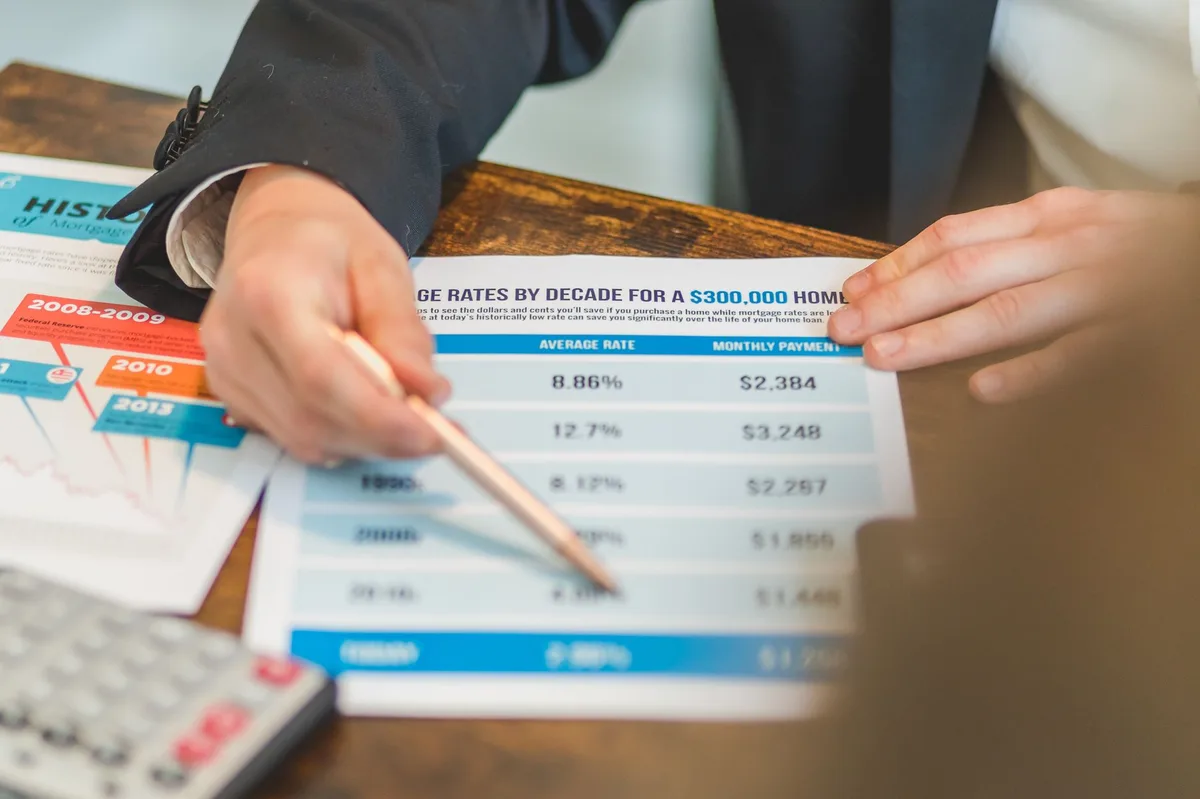
Learn the timeline and essential steps to close on your home purchase before December 31, 2026, to maximize tax benefits and meet your year-end deadline.
Learn what closing costs include, how much to expect, and proven strategies to reduce these fees when buying a home in the United States.
Compare lender-managed escrow accounts with self-managing your property taxes and insurance to decide which option fits your mortgage situation.
Understand the real costs you'll pay when buying or refinancing a home in the United States, from lender fees to title insurance.
Deciding between buying mortgage points or keeping cash for closing costs depends on your break-even timeline, emergency reserves, and how long you plan to stay in the home.
An escrow account is a separate account your lender manages to pay property taxes and homeowners insurance on your behalf, ensuring these critical costs are covered on time.
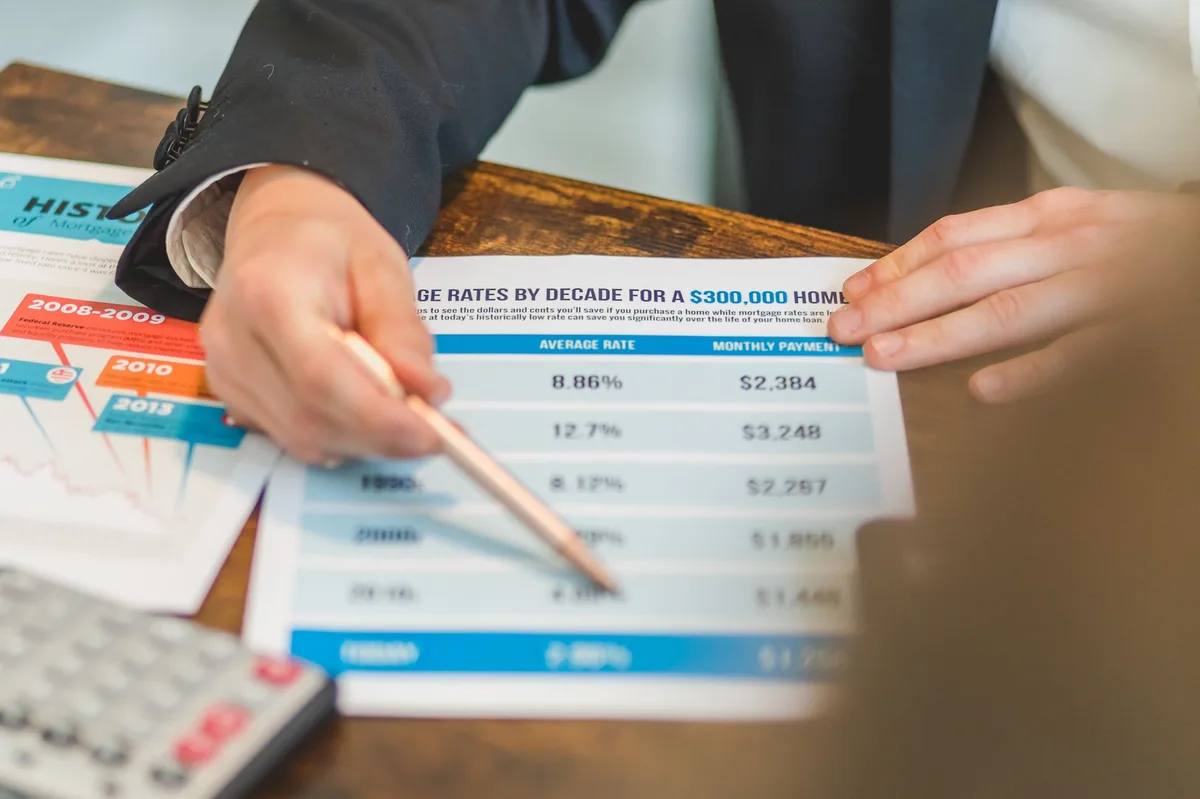
Learn the proven strategies to boost your credit score before applying for a home loan and qualify for better mortgage rates and terms.
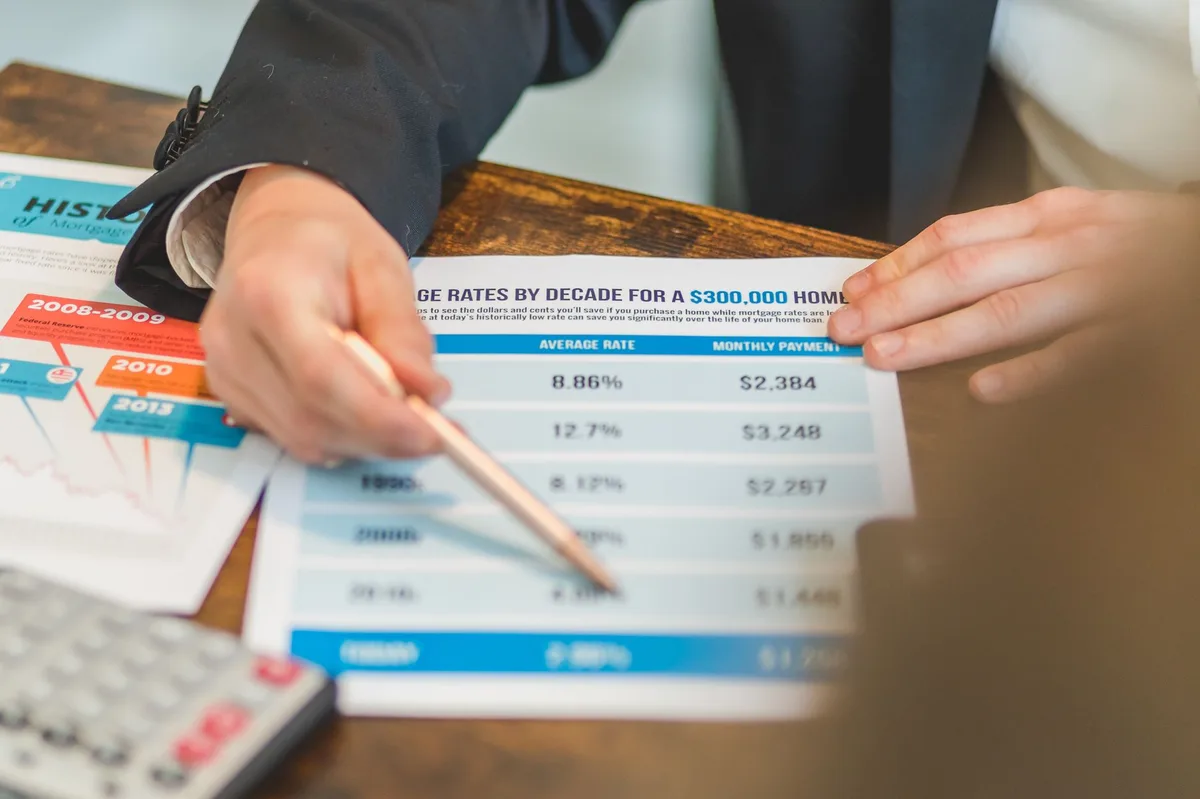
Learn how debt-to-income ratios determine how much home you can afford and what monthly payment fits your budget.
Your debt-to-income ratio is one of the most critical factors lenders evaluate when deciding whether to approve your mortgage application and at what terms.
Debt-to-income ratio helps estimate how much mortgage payment may fit your budget. This calculator shows how income, debts, taxes, insurance, and loan assumptions work together.
Compare five proven strategies to accelerate mortgage payoff and save thousands in interest without the cost and hassle of refinancing.
Escrow shortages happen when property taxes or insurance premiums increase more than your lender anticipated, forcing your monthly mortgage payment higher.
Learn how switching to bi-weekly mortgage payments can help you pay off your home loan years ahead of schedule and save thousands in interest.
Learn the formulas for gross and net rental yield, understand what each number reveals about your investment property's performance, and see how to compare properties effectively.
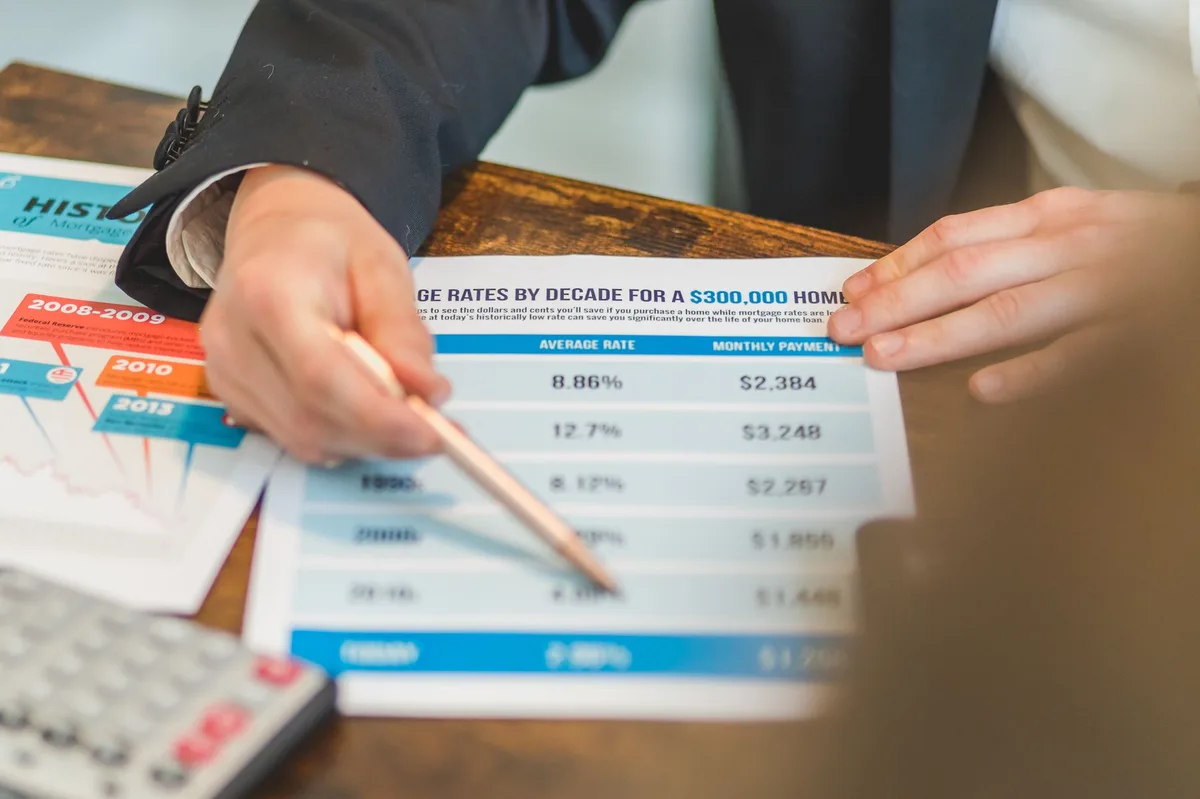
Learn to decode your amortization schedule, understand how each payment splits between principal and interest, and see exactly how much interest you'll pay over the life of your loan.
Essential tax deductions and planning steps every property investor should review before filing to maximize savings and stay compliant with IRS rules.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.
