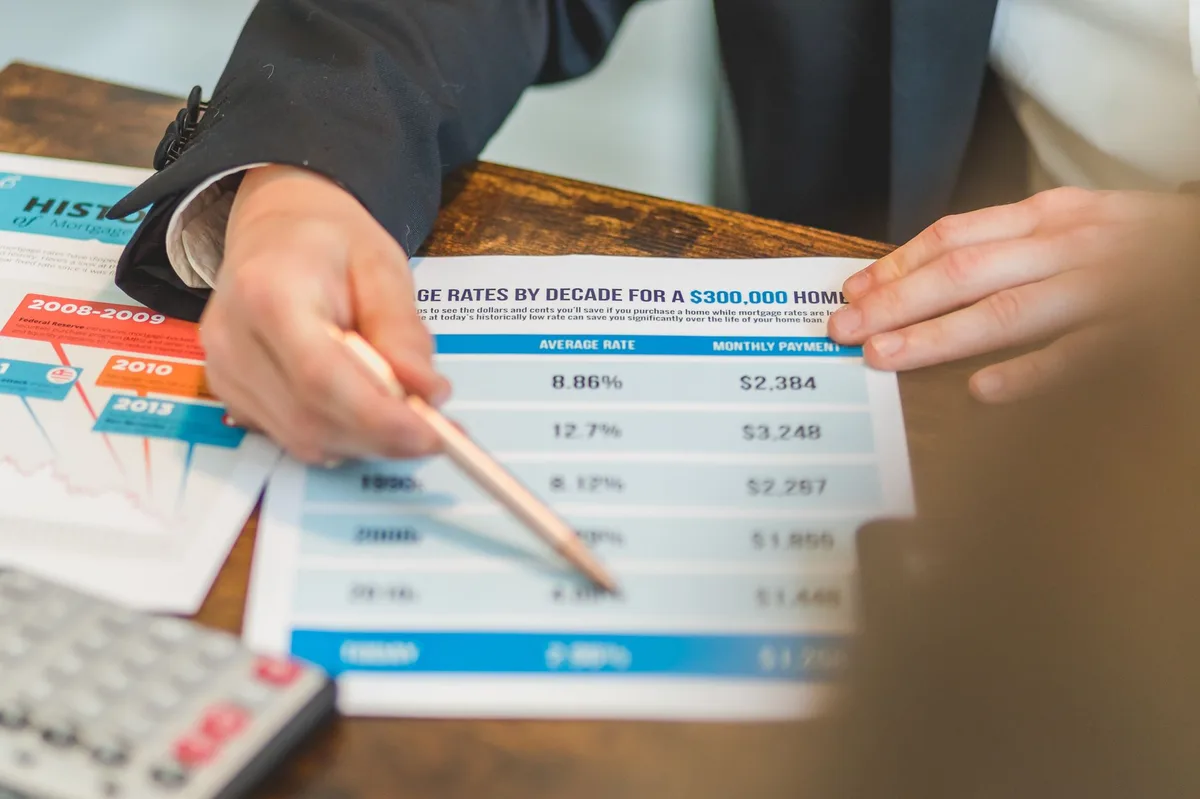
Mortgage
Understanding CIBC Mortgage Rates in Canada
Learn how CIBC structures its mortgage rates, what affects your rate offer, and how to compare fixed versus variable options at one of Canada's major banks.
Mortgage, refinance, and home-financing guidance for Canadian buyers and owners.
Learn how CIBC structures its mortgage rates, what affects your rate offer, and how to compare fixed versus variable options at one of Canada's major banks.
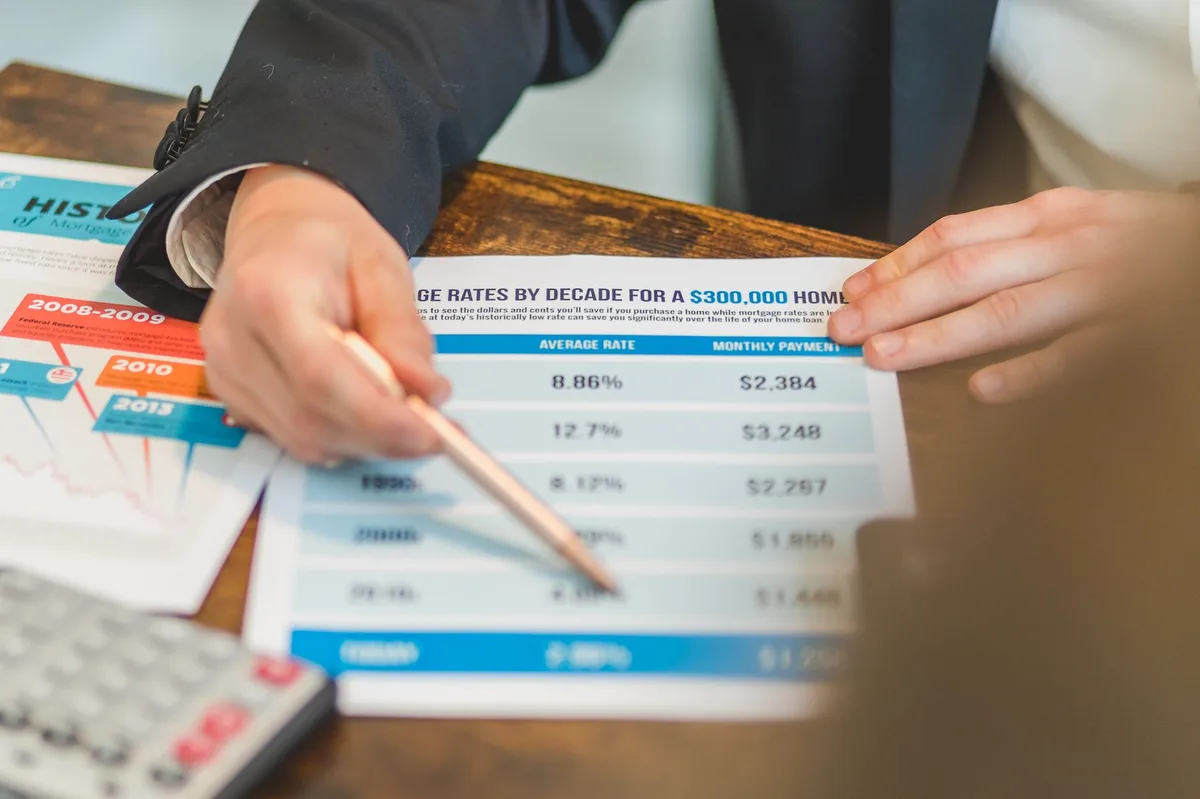
A comprehensive guide to Manulife's mortgage rate structure, products, and what Canadian borrowers need to know when comparing rates.
When major Canadian banks disagree on future interest rates, your mortgage renewal strategy needs to account for uncertainty - here is what the split forecasts mean and how to prepare.
The International Monetary Fund has flagged bond-market volatility as a global threat, while major Canadian lenders like BMO respond by raising fixed mortgage rates.
The Bank of Canada announces its policy rate decision on October 28. Here's what Canadian mortgage holders and borrowers need to know about this key rate decision.
U.S. Federal Reserve rate changes can influence Canadian mortgage rates through bond markets and capital flows, but the Bank of Canada sets policy independently based on Canadian economic conditions.
With mortgage rates elevated and renewal terms tightening, Canadian homeowners face critical decisions. Learn how to evaluate your options, negotiate effectively, and choose the right renewal strategy for your financial situation.
Mortgage renewal in 2026 will require careful planning as homeowners face changing rate environments, new lender options, and updated qualification requirements.
OSFI has removed the mortgage stress test requirement for straight switches, making it easier for Canadian homeowners to move their mortgage to a new lender at renewal for a better rate.
Bank of Montreal now requires borrowers switching their uninsured mortgage to qualify at the higher stress-test rate, reversing an industry practice that had made switches easier.
A largely unknown OSFI exemption allows borrowers with insured mortgages to switch lenders at renewal without passing the mortgage stress test, potentially saving thousands in interest.
Canadian borrowers renewing their mortgage can now switch lenders without passing the stress test, removing a barrier that previously limited rate shopping at renewal.
The OSFI mortgage stress test remains a cornerstone of Canadian lending, but rising rates and changing market conditions have renewed debate about its role and effectiveness.
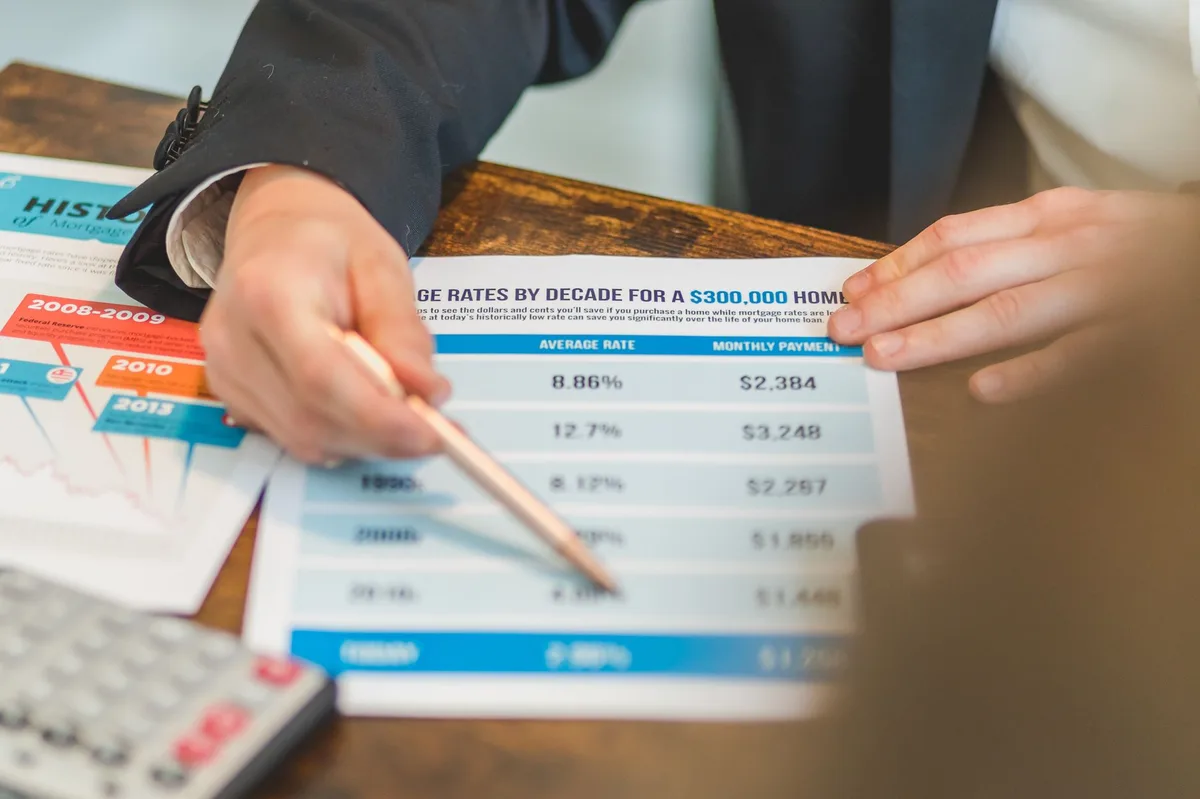
Understanding OSFI's mortgage stress test requirement and how it affects your borrowing power in Canada.
Canada's mortgage stress test may see adjustments to qualification rates, exemption policies, and regional application as economic conditions evolve and affordability concerns mount.
Recent changes to OSFI's mortgage stress test have created uncertainty among lenders, brokers, and borrowers across Canada's mortgage industry.
Learn how the OSFI mortgage stress test affects your home buying power in Canada, including the qualifying rate, calculation examples, and strategies to pass.
OSFI has identified an imbalance in how the mortgage stress test applies at renewal versus new mortgages, but rule changes are not imminent. Here's what Canadian borrowers need to know.
An in-depth look at Home Trust's mortgage products, rates, and services for self-employed borrowers, newcomers, and alternative credit applicants across Canada.
The First Home Savings Account offers Canadian first-time buyers a triple tax advantage for down payment savings, combining the best features of RRSPs and TFSAs.
Co-signing a mortgage lets parents use their income and credit to help an adult child qualify, but it carries serious financial and legal obligations for both parties.
Understanding the difference between open and closed mortgages helps you choose the right prepayment flexibility for your financial situation.
Compare the FHSA and RRSP HBP to find the best tax-advantaged savings strategy for your first home purchase in Canada.
Compare the RRSP Home Buyers Plan and the First Home Savings Account to decide which down payment strategy works best for your first home purchase in Canada.
Learn how to combine the FHSA and RRSP Home Buyers' Plan to maximize your down payment savings for your first home in Canada.
CMHC mortgage default insurance is required when your down payment is less than 20 per cent, protecting lenders while helping buyers enter the market with a smaller deposit.
Compare insured and uninsured mortgages in Canada and understand how the 20 per cent down payment threshold determines your mortgage insurance costs, rates, and qualification rules.
Use the Home Buyers Plan to withdraw up to $60,000 from your RRSP for a down payment, then repay it over 15 years. The calculator shows your exact repayment timeline and annual obligations.
Learn how the Home Buyers Plan calculator helps you determine your RRSP withdrawal limit and repayment schedule when buying your first home in Canada.
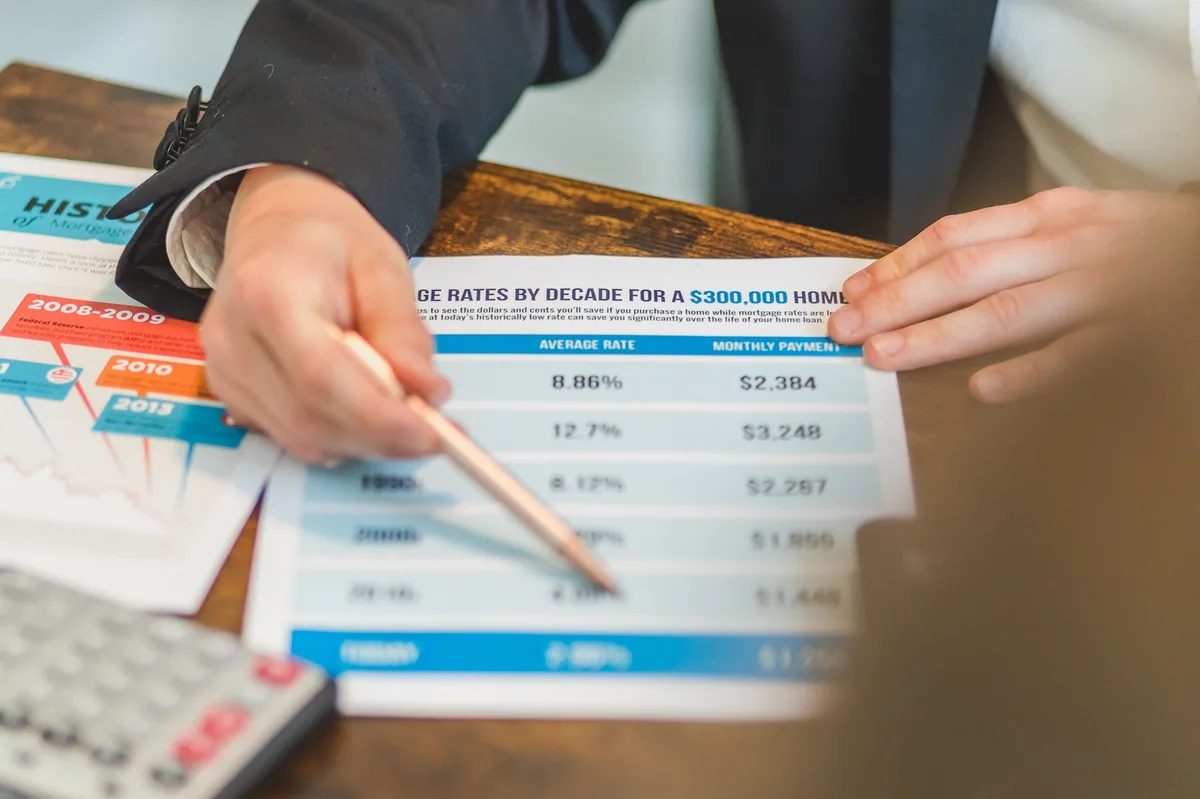
Learn how CMHC mortgage insurance premiums are calculated based on your down payment and purchase price, and use our calculator to estimate your cost.
A HELOC lets you borrow against your home equity as you need it, with flexible repayment and variable interest rates tied to the lender's prime rate.
Comparing a HELOC and mortgage refinancing for accessing home equity in Canada, with guidance on which product fits specific financial situations.
Understand how CHIP reverse mortgages let Canadian homeowners 55+ access home equity without monthly payments, what you'll pay in setup and interest costs, and how to calculate your proceeds.
A tax strategy that converts non-deductible mortgage debt into deductible investment debt through a readvanceable mortgage and disciplined reborrowing.
Comparing HELOCs and mortgage refinancing to help Canadian homeowners choose the right way to access their home equity.
Learn how a HELOC works in Canada, the regulations that govern borrowing limits, and smart strategies for accessing your home equity responsibly.
Understanding the tax implications of mortgage closing dates in Canada and what year-end timing actually affects.
Land transfer tax rates and first-time buyer rebates vary significantly across Canadian provinces, with Ontario and British Columbia charging the highest rates while most provinces levy no transfer tax at all.
Ontario charges land transfer tax on every property purchase. Learn how the progressive tax rates work and whether you qualify for the first-time buyer rebate.
Ontario land transfer tax is a closing cost based on the home's purchase price. First-time buyers may qualify for a provincial rebate, and Toronto buyers may also owe municipal land transfer tax.
Prepayment privileges let you pay down your mortgage ahead of schedule without breaking your term. Learn how lump-sum payments and increased payment amounts can save you thousands in interest and years off your amortization.
Discover how to use prepayment privileges to reduce your mortgage term, save thousands in interest, and own your home sooner.
Learn how to calculate gross and net rental yield to measure the return on your Canadian investment property and compare opportunities.
Learn how to maximize deductions and meet CRA requirements with strategic tax planning before December 31 and the filing deadline.
Bank of Canada analysis reveals which Canadian homeowners face the steepest payment increases at renewal in 2026, and what the data shows about managing the shock.
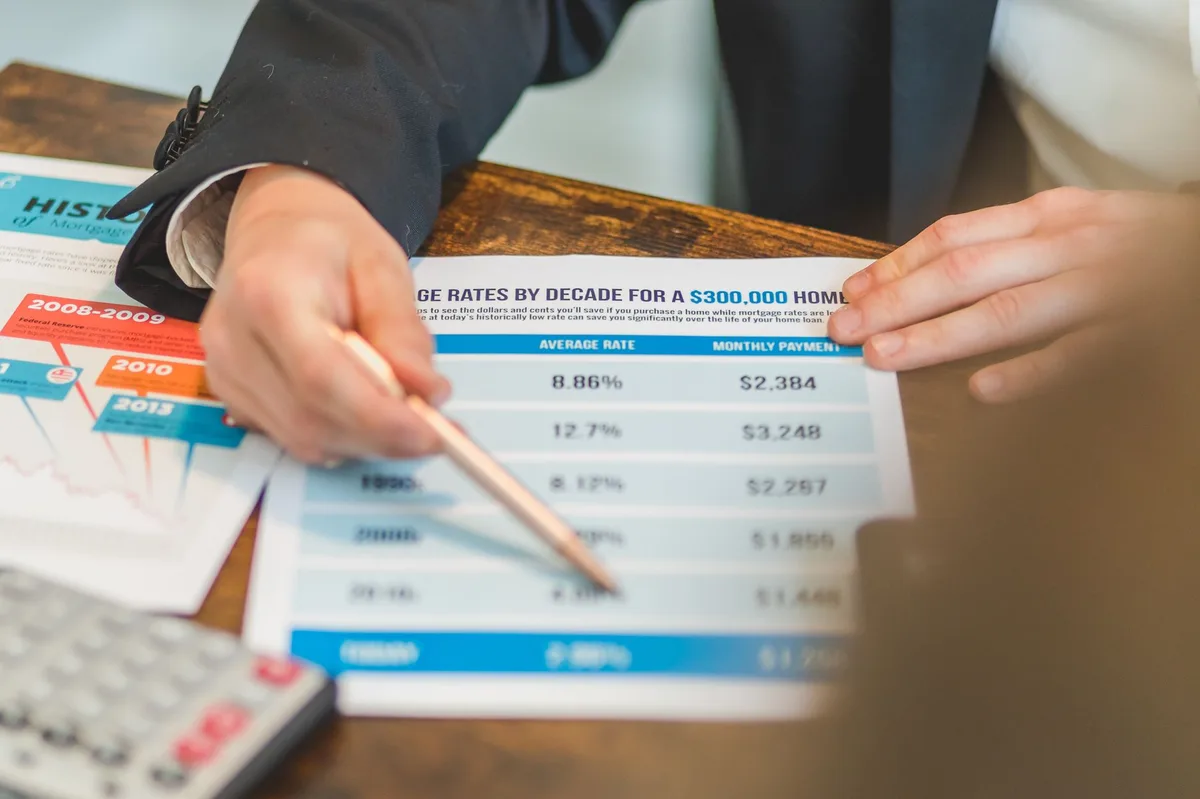
A mortgage deferral pauses your payments temporarily, but interest keeps adding up and your amortization extends. Here's what that pause actually costs you.
Learn how to evaluate rental property returns using gross and net rental yield calculations to make informed Canadian real estate investment decisions.
Learn to decode your mortgage amortization schedule and see exactly how much of each payment goes to interest versus principal over your loan's life.
Compare mortgage life insurance and term life insurance to choose the right coverage for your home financing and family protection needs in Canada.
Get new articles?
Want notifications about new articles and tools? You can unsubscribe anytime, and we store no personal data about you.
